


Hotel Properties Limited (“HPL”) has returned to the SGD bond market after issuing the HPLSP 4.400% Perpetual Corp (SGD) in October last year. The new 5-year senior unsecured bond is launched under the issuer’s S$1 billion multicurrency debt issuance program dated 3 Mar 17. Coupons are paid on a semi-annual basis and the note matures in May 2025.
About HPL
Headquartered in Singapore, the principal business activities of HPL include hotel ownership, management and operation, property development and investment holding. The hotelier has an interest in 36 hotels across 15 countries that are run under a number of brands like Four Seasons, Hilton International, Como Hotels, Marriott International and InterContinental Hotels Group.
In Singapore, the group’s property developments include Tomlinson Heights, Robertson Blue, Cuscaden Residences, Scotts 28, Nassim Jade, Four Seasons Park, and joint-venture projects such as Interlace and d’Leedon. In addition, HPL owns a number of prime commercial real estate along Orchard Road and The Met condominium in Bangkok, Thailand. HPL is also establishing its presence in London through a series of joint-venture freehold developments, comprising of the Burlington Gate, Holland Park Villa, Paddington Square and Bankside Yards.
Financials and credit performance
In the year ending 31 Dec 19, the group reported an annual revenue of S$556.4m, down 4.0% from S$579.5m in 2018 and S$659.2m in 2017. The decline was driven mainly by lower property development sales, which decreased from S$45.6m in 2018 to S$1.3m in 2019. Income contributions from associates and jointly controlled entities fell 68.8% to S$28.9m due to lower profits from the Holland Park Villas project in London, leading to a 56.1% plunge in net profit to S$54.7m for 2019.
Earnings before interest and taxes (“EBIT”) decreased 32.1% to S$123.0m, while finance costs climbed to S$38.5m from S$27.5m in 2018. The firm’s ability to service interest expense, or EBIT over interest, dropped from 6.6x in 2018 to 3.2x in 2019, which is still decent in our opinion.
Net cash from operating activities (“CFO”) declined 13.7% to S$134.0m during 2019 but remained in positive territory. HPL reported net CFO of S$283.8m and S$155.2m in 2017 and 2018 respectively. After factoring in capital expenditures, free cash flows were also positive in the last three years (2019: S$26.1m; 2018: S$32.2m; 2017: S$131.2m)
As at 31 Dec 19, the group’s cash position of S$192.3m was sufficient to cover the value of its short term borrowings of S$156.6m, while its current ratio, or current assets over current liabilities, improved to 1.3x from 0.8x in 3Q19.
After making a series of acquisitions in 2019, total assets increased to S$3.53 billion from S$3.15 billion a year earlier. Total borrowings increased 20.2% to S$856.6m and aggregate debt – measured as total debt including lease liabilities and perpetual securities – jumped 46.0% to S$1.26 billion.
As a result, HPL’s gearing, calculated as aggregate debt over total assets, increased from 27.3% in 2018 to 35.6% in 2019. In spite of the increase in borrowings, we think that the group’s gearing ratio is still manageable. On a side note, secured bank loans carried floating interest rates ranging from 1.0% to 4.9% in 2019 (2018: 1.0% to 4.9%), and certain unsecured notes and other secured long-term liabilities had fixed interest rates between 3.9% and 5.0% (2018: 3.5% to 5.0%).
Bond valuation
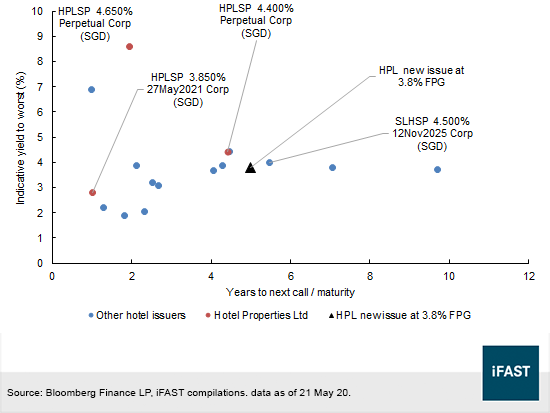
In view of HPL’s positive cash flows, decent gearing and manageable liquidity profile, we think that HPL’s credit health remains good. However, the 3.8% final price guidance (“FPG”) looks mediocre among comparable credits. For example, the HPLSP 4.650% Perpetual Corp (SGD)’s indicative yield to next call of more than 8% is more appealing to us, albeit there is a possibility that the issuer may not redeem the perpetual security on its first call date. At the moment, we think there is low extension risk for the 4.65% perp as the company should be able to tap other sources of liquidity to cover its financial obligations.
Moreover, there are other credits that provide a slightly higher return like the SLHSP 4.500% 12Nov2025 Corp (SGD), which has an indicative yield to maturity of 3.9%. Shangri-La Asia Ltd (“Shangri-La”), the guarantor of the bond, has more exposure to China. HPL is more focused in Singapore and the Maldives, which accounted for 33.8% and 33.5% of group revenue respectively in 2019. To our understanding, hotel occupancies have picked up in China after the lockdown restrictions were lifted in the country, and that would put Shangri-La at an advantage in terms of its earnings outlook. One minor argument against Shangri-La is that the company had a higher gearing ratio of 42.9% as compared to HPL (35.6%), at the end of 2019.
Figure 1: Relative valuation
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.


