


- For the first quarter financial results ending 31 March 2022 (“1Q22”), LMIRT saw revenues rebounding.
- Visitor traffic for LMIRT have recovered slightly and are 58% of pre-Covid levels.
- We expect operating conditions for LMIRT to improve following the reopening of borders in Indonesia.
- We think LMIRT has sufficient short-term liquidity and gearing is adequately below regulatory requirements of 50% for S-REITs.
- In terms of LMIRT’s fixed rate bonds, the LMRTSP 7.250% 19Jun2024 Corp (USD) has about 2 years to maturity and has a indicative yield to maturity of 8.10%.
- At current 5Y SOR levels (taken on 9 June 2022) of 3.055%, the LMRTSP 6.6% perps is expected to reset at a much higher rate than its coupon rate.
Lippo Malls Indonesia Retail Trust (“LMIRT”) is one of Indonesia’s largest retail property owners. It is the only Indonesian retail real estate investment trust (“REIT”) listed on the Singapore Exchange.
As of 30 September 2021, the REIT managed 22 malls and 7 retail spaces, most of which are located across the Greater Jakarta, Bandung and Yogyakarta regions. LMIRT is rated ‘B1’ by Moody’s and ‘B+’ by Fitch Ratings.
Lippo Karawaci (“LPKR”) is the LMIRT’s sponsor. With a notable development track record, LPKR is the market leader in mixed-use integrated developments with the largest land bank in Indonesia. The sponsor owns and/or manages 56 retail malls. As at 2 December 2021, LPKR had a 47.29% interest in the REIT.
FY21 financial highlights
Table 1: Summary of financial results for 1Q22
|
As of 31 March 2022 (in SGD m) |
1Q22 |
1Q21 |
% Change |
|
Rental Revenue |
30.50 |
26.48 |
15.2 |
|
Carpark Revenue |
1.31 |
1.21 |
8.0 |
|
Service Charge and Utilities Recovery |
18.69 |
15.47 |
20.8 |
|
Gross Revenue |
50.90 |
43.61 |
16.7 |
|
Net Property Income |
31.27 |
25.78 |
21.3 |
|
Source: Company Financial Reports, iFAST estimates. As at 31 March 2022. |
|||
For the first quarter financial results ending 31 March 2022 (“1Q22”), LMIRT saw revenues rebounding. Rental revenue grew 15.2% to SGD 30.5m while net property income increased by 21.3% to SGD 31.2m in 1Q22. For 1Q22, lower rental discounts were offered to tenants as malls managed by the REIT were open for longer hours. The growth in revenue was also attributable to revenues from Lippo Mall Puri (acquired on 27 Jan 2022). From the acquisition of Lippo Mall Puri from their sponsor, LPKR, there is a NPI guarantee from LPKR until 2024. As part of the Vendor Support Agreement of the acquisition of Lippo Mall Puri, LPKR will provide NPI guarantee of IDR 340b (~SGD 32.3m) per annum. This should translate to approximately 25% of NPI for LMIRT, showing some support from its sponsor for the acquisition and steady income to tide through the pandemic.
Vaccination still remains key in Indonesia’s retail recovery
As highlighted in our previous articles, vaccination rates in Indonesia is an important driver to Indonesia’s retail recovery. Indonesia was faced with a surge of Covid-19 cases in July 2021, which led to emergency lockdowns in Indonesia. As a result, visitor traffic for LMIRT’s malls plunged in 3Q21 (figure 1). Visitor traffic have since recovered slightly and are 58% of pre-Covid levels.
(Related articles: “Will LMIRT bonds outperform its stock in 2022?” and “If there is a dip, buy LMRT bonds”)
Figure 1: Visitor traffic (in thousands)
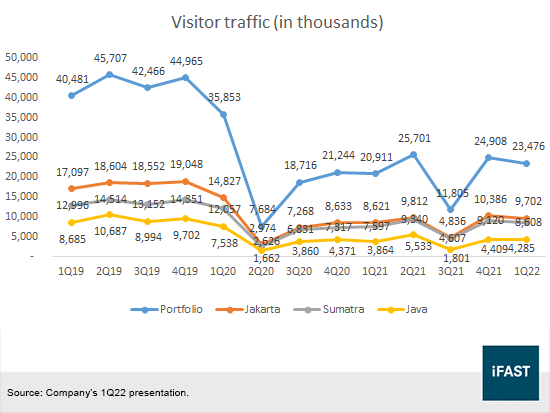
Figure 2: Vaccination rate in the ASEAN region
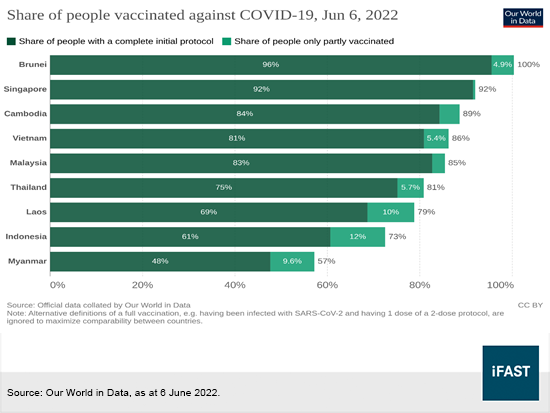
Vaccination rates in Indonesia have lagged other ASEAN peers. As of 6 June 2022, only 61% of Indonesia’s population have been fully vaccinated while 12% of its population are partially vaccinated (figure 2). At 73% of its population with at least one dose of vaccine, Indonesia’s vaccination numbers is one of the lowest among ASEAN peers. From 18 May 2022, Indonesia have allowed vaccinated travelers to enter the country without quarantine. The low vaccination rates in Indonesia poses some risks in potential lockdowns from another surge of Covid-19 infections within the country.
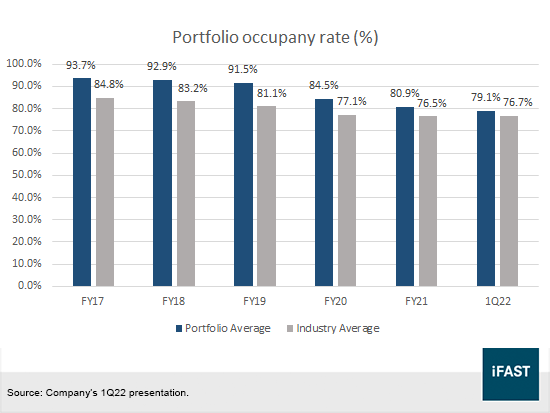
Further lockdowns will cause further strain to retail tenants in Indonesia. Occupancy rates for LMIRT have not been stable since the start of the pandemic. From figure 3, occupancy rates for LMIRT malls saw a decrease of 12.4% in occupancy compared to the market average of -4.4%. The Covid-19 situation in Indonesia have since improved and with the country reopening its borders, it should bolster LMIRT’s occupancy rates.
Figure 3: Portfolio occupancy rate (%)
Nonetheless, we expect operating conditions for LMIRT to improve following the reopening of borders in Indonesia. In 1Q22, no rental discounts were given to tenants while rental reversions saw a 2.3% increase year-to-date. In Bank Indonesia’s retail survey done in April 2022, Real Sales Index rose 6.8% month-to-month. We expect retail confidence to continue to improve for the next quarter.
Credit and solvency profile
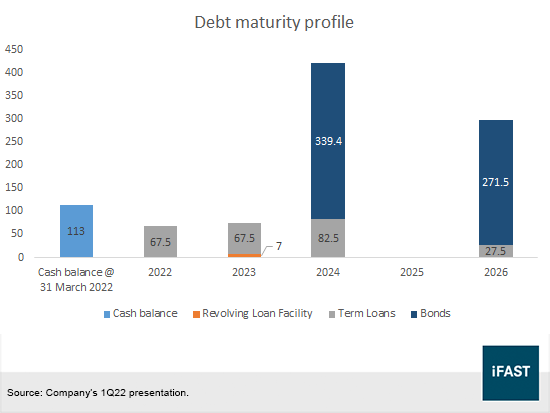
As of 31 March 2022, LMIRT had cash and cash equivalents of SGD 113.0m, of which SGD 2.55m is restricted cash for bank facilities. LMIRT also has ~SGD 23m in committed revolving loan facilities. The REIT has sufficient cash to cover its short term borrowings maturing in FY22 of SGD 67.5m. We believe the REIT has strong access to capital markets as the REIT managed to raise USD 200m from LMRTSP 7.500% 09Feb2026 Corp (USD) notes in Feb 2021 during the pandemic. The proceeds were used to refinance SGD 175m of term loan facility and SGD 44m of unsecured uncommitted revolving credit facilities.
In terms of its credit metrics, LMIRT has a gearing ratio (taken
as total gross borrowings and deferred payments / total deposited property) of
42.9% while interest coverage ratio was 2.0x in 1Q22. We think LMIRT has
sufficient short-term liquidity and gearing is adequately below regulatory
requirements of 50% for S-REITs.
Figure 4: Debt Maturity Profile
Recommendation
Table 2: LMIRT bonds
|
Bond name |
Issuer |
Maturity/next reset |
Years to maturity/ next reset |
Ask price |
Yield to maturity/ next reset (%) |
| LMRTSP 7.250% 19Jun2024 Corp (USD) | LMIRT Capital Pte Ltd |
19 Jun 2024 |
2.0 |
98.44 |
8.10 |
|
LMIRT Capital Pte Ltd |
09 Feb 2026 |
3.7 |
97.65 |
8.25 |
|
|
Lippo Malls Indonesia Retail Trust |
19 Dec 2022 |
0.5 |
68.94 |
11.56 |
|
|
Lippo Malls Indonesia Retail Trust |
27 Sep 2026 |
4.3 |
66.91 |
18.60 |
|
|
Source: Bloomberg Finance L.P., iFAST compilations. Data as of 9 June 2022. |
|||||
We recommend the LMRTSP bonds to high yield seekers with a high risk appetite. In terms of LMIRT’s fixed rate bonds, the LMRTSP 7.250% 19Jun2024 Corp (USD) has about 2 years to maturity and has a indicative yield to maturity of 8.10%. We prefer the 2024 bonds to their 2026 bonds for their shorter time to maturity and the yield pickup is only 15 basis points (“bps”) which we do not think compensates investors for holding the bonds for an additional 1.7 years.
For LMRTSP’s perps, we do not expect the issuer to call its perps on its first call date. We prefer the LMRTSP 6.600% Perpetual Corp (SGD) over the LMRTSP 6.4751% Perpetual Corp (SGD) for its shorter time to next reset. At current 5Y SOR levels (taken on 9 June 2022) of 3.055%, the LMRTSP 6.6% perps is expected to reset at a much higher rate than its coupon rate. As reference if the perps were to reset at the time of writing this article, it would reset to a coupon rate of 7.81% (taking 5Y SOR at 3.055% plus the initial spread of 4.755%). Furthermore, in the case should LMRTSP unexpectedly call back its perps, investors do gain capital appreciation from redemption of the perp at par value. The LMRTSP 6.600% Perpetual Corp (SGD) is available in odd lot sizes on Bond Express.
Conclusion
All in all, we expect Indonesia’s retail mall to recover following the reopening of their borders. We do also note that vaccination rates in Indonesia is one of the lowest among ASEAN countries and may pose some risk of a resurgence of Covid-19 infections that may potentially lead to lockdowns. We recommend the LMRTSP bonds to high yield seekers with a high risk appetite. For fixed rate bonds, we like the 2024 bonds for their shorter time to maturity. For its perps, we like the 6.6% perps over the 6.4751% perps. Although we do not expect LMIRT to call back its perps on the call date, the 6.6% perps may potentially reset at a higher coupon rate.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in LMRTSP 6.600% Perpetual Corp (SGD) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!









