


Highlights:
- Greentown’s growth rate of 2021 contracted sales topped among the large-scale property developers in China. Meanwhile, Greentown is a leading company in the project management sector, the current circumstances may be conducive to the further development of Greentown, as the mid or small-sized developers tend to use project management services.
- Greentown has two credit metrics fulfilled the requirements of regulatory policy, and it has an abundant cash balance. Despite the relatively unhealthy credit indicators concerning the off-balance-sheet debt, the company has a very strong refinancing capability as it is backed by China Communication Construction Group, a state-owned enterprise. As a result, its liquidity is expected to remain at a decent level, and the overall credit profile is controllable.
- The Bond due July 2025 is relatively attractive.
Investors might observe that all Chinese developers that have stepped into default crisis are non-SOE companies, and the developers with SOE backgrounds seem to be rarely influenced. As a result, investing in bonds issued by SOE developers may be a good choice. In this Idea of the Week article, we will analyse the latest operation performance of Greentown China Holdings Limited ("Greentown" hereafter), to see if the company with SOE background would be worthy of consideration.
Company Background
Greentown was established in 1995 and became a Hong Kong-listed company in 2006 (3900.HK). Its current market capitalisation is roughly HKD 34 billion.
Property development is the key business sector of Greentown, and the company is also involved in property investment, property management, as well as hotels operation. In the property development sector, Greentown ranked 13th among Chinese property developers in terms of contracted sales in 2021, therefore, could be classified as a large-scale developer. In the meantime, Greentown also engaged in property project management, and carved out this sector in July 2020 as Greentown management Holdings Company Limited, another Hong Kong-listed company (9979. HK).
It is worth mentioning that China Communication Construction Group, a central government-owned enterprise, owns 25.1% of Greentown’s share and is its largest shareholder. Therefore, Greentown could be considered a developer with an SOE background. In the meantime, Hong Kong Wharf Group owns its 22.4% share.
Growth Rate of Contracted Sales Topped among Large-sized Developers
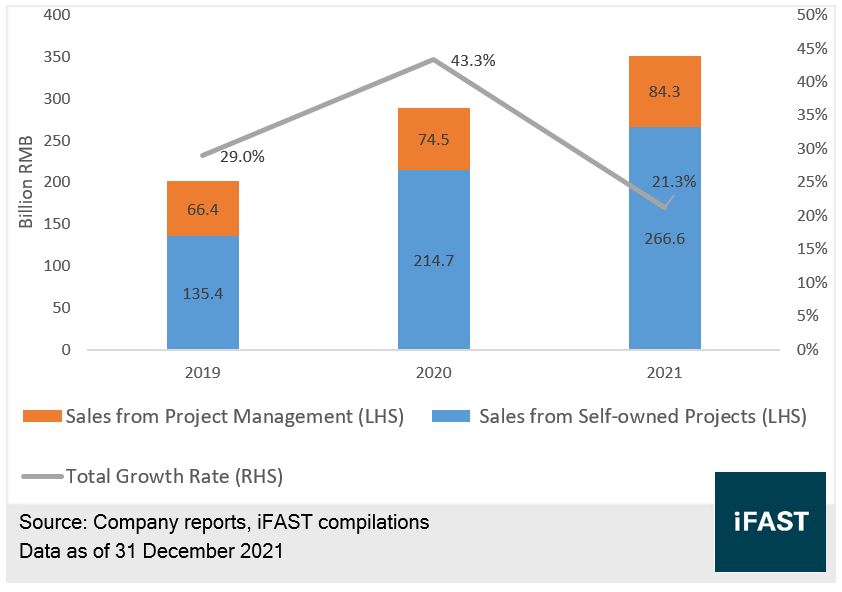
Despite the downturn of the Chinese property market since 2021, with the top 100 developers dipping by 3.5% in contracted sales, Greentown still delivered amazing final results with contracted sales of RMB 350.9 billion, surging by 21% YoY, which ranked top among large-sized developers. Sales of self-investment projects swelled over 25% to RMB 266.6 billion.
Chart 1: Contracted Sales
A high sell-through rate is a key to its good track record. The overall sell-through rate in 2021 spiked to 69%, and projects in tier-one and tier-two cities reported a higher rate at 80%. It's important to note that the sell-through rate of most developers was below 50% amid a sluggish property market in 2021. How could Greentown retain a high sell-through rate?
The confidence of house buyers also plays a vital role. Generally speaking, under the current situation where the property market has uncertain futures with snowballing defaulted cases, the house buyers may believe the SOE developers would have a stronger risk-resistance capacity, and offer the buyers with higher assurance in housing delivery. So house buyers would prefer the projects delivered by the SOE developers. As a result, we noticed that the 2021 sales performance of SOE developers outperformed the market, such as CR Land’s sales number rose around 20%.
Looking ahead, we expect Greentown to have ample room for development. As of the end of 2021, the total land band Greentown owned amounted to 58.8 million square meters with a total aggregated value of RMB 940 billion, which could meet the land requirement in the coming three years.
Blooming Project Management Business
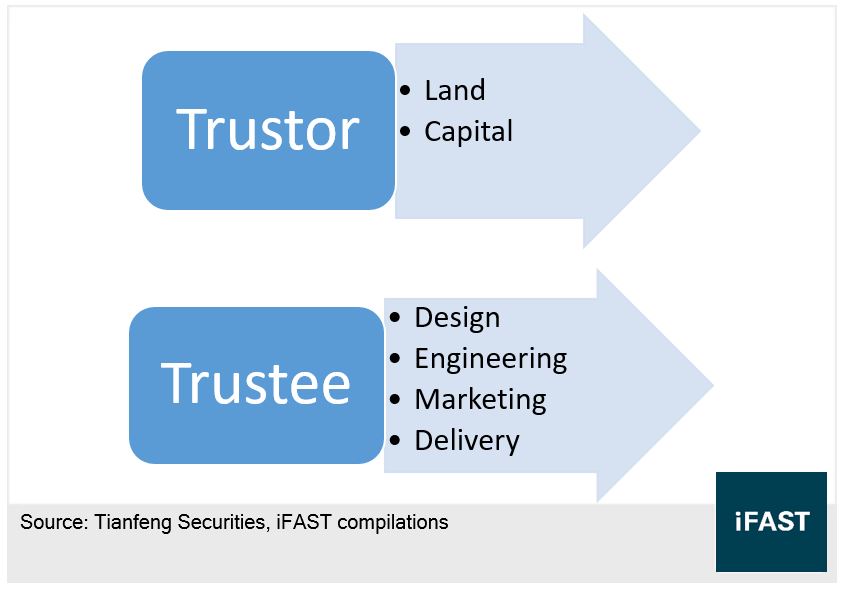
Investors might not be familiar with the project management services provided by the developers. Therefore, we will give a brief introduction to the business sector. Project management literally means a developer entrusts another developer to manage property projects, including design, engineering, marketing, as well as delivery. The entrusting party is only responsible for offering land and capital for the development project. Generally, the entrusting parties are the small-sized developers, while the trustees are the mid-to-large-sized experienced developers.
Currently, there are two mainstream business models of project management in the industry, pure project management and project management with minor interest. For the former one, it does not require a large amount of capital expenditure, and it will charge a fixed management fee for designated projects. The latter one resembles the “less ownership” business model, but it will dominate the project, as the trustee owns a portion share of projects (usually less than 10%), and share the profits of the project’s sales.
As an experienced developer, Greentown offers project management services to many developers. The company mainly adopt the project management with a minor interest business model, and the sale of project management from Chart 1 reflects the contracted sales under minority interest.
Chart 2: Project Management
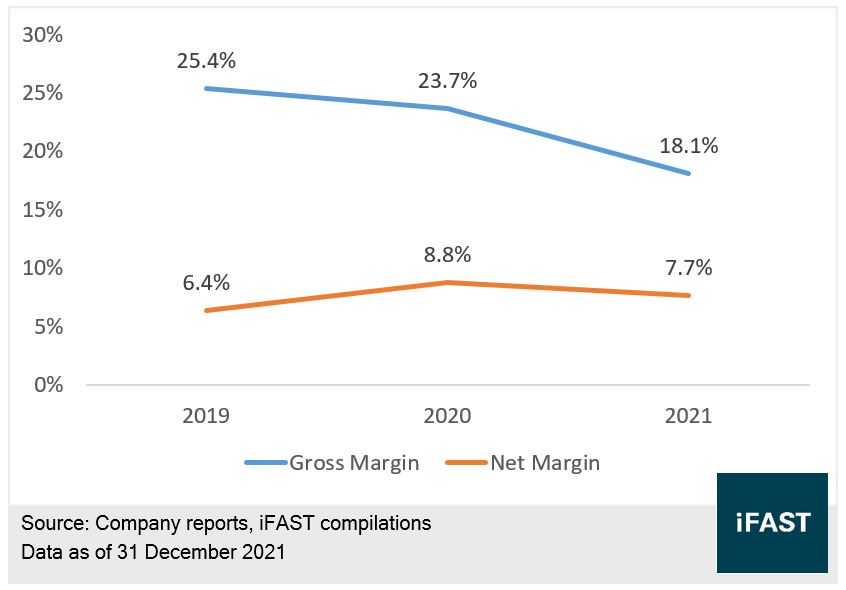
The project management business indeed can bring many benefits to Greentown. On one hand, due to the light-asset nature of the project management business, it will not occupy much of the company’s cash balance, which helps the company to maintain relatively low leverage. On the other hand, projects management could bring the company a higher profit margin, as shown in chart 3, its average gross margin in the past three years has been as high as nearly 20%, which is about 10% higher than the industry average of about 10%.
Chart 3: Profitability
We also noted that the project management business is booming. As of the end of 2021, the number of projects reached 345, with related income amounting to RMB 7.1 billion, up 22.3% YoY. Considering that the property industry is facing more intense competition and stricter regulation policy, leaving more challenges for small-sized developers’ survival as a result. There might be a greater driving force for small-sized developers to seek to use project management services. We hence predict that the project management business of Greentown is expected to maintain rapid growth in the coming years.
Credit Metrics Improved with Ample Cash
Table 1 shows that rather than deteriorations, the major credit metrics of Greentown had been improved in 2021. The net gearing ratio declined from 63.8% in 2020 to 52.0% in 2021, hinting at decreasing leverage and lower stress from debt repayment. The ratio of cash to short-term debt rose to 2.2x, demonstrating ample cash balance with good liquidity. Adjusted liability to asset ratio dipped slightly and nearly meet the regulatory requirement. Since it has two credit metrics that passed the requirements of “Three Red Lines”, Greentown is considered as a "Yellow Zone" developer. Overall, the report credit indicators of Greentown are comparatively excellent in the industry.
Table 1: Credit Metrics
|
2020 |
2021 |
Requirement of Three Red Line |
|
|
Net Gearing Ratio |
63.8% |
52.0% |
<100% |
|
Cash to Short-term Debt |
2.0 |
2.2 |
>1.0x |
|
Adjusted Liability to Asset Ratio |
71.9% |
71.1% |
<70% |
|
Source: Company
reports, iFAST compilations |
|||
Unhealthy Off-balance-sheet Credit Indictors
Looking into off-balance-sheet credit indictors, as of 31 December 2021, minority interest over total equity ratio surged to 57.8%, and payable to joint ventures over total debt also jumped to 30.3%. Both indicators have high numbers, showing increasing collaborative projects and the likelihood of potential off-balance-sheet debt.
We think that the relatively unhealthy credit metrics concerning the off-balance-sheet debt were owing to business strategies. Firstly, Greentown has a large number of joints ventures, under this business model, a portion of projects is not consolidated into Greentown's financial statement, which suggests the company may have off-balance-sheet debts. Besides, some off-balance-sheet debt might derive from “less ownership” business model.
Table 2: Off-balance-sheet Credit Metrics
|
2020 |
2021 |
|
|
Minority Interest/Total Equity |
37.5% |
57.8% |
|
Payable to Associate/joint Ventures over Total Debt |
19.6% |
30.3% |
|
Contracted Liabilities to Attributable Contracted Sales |
94.7% |
102.8% |
|
Source:
Company reports, iFAST compilations |
||
Backed
by Central Government Owned Enterprise, Having the Very Strong Capability of Refinancing
Despite the relatively unhealthy off-balance-sheet credit metrics, the company might not face a higher solvency risk due to its prominent refinancing ability. Benefiting from its SOE background, Greentown is favoured by the capital market and could refinance through various channels at a low cost.
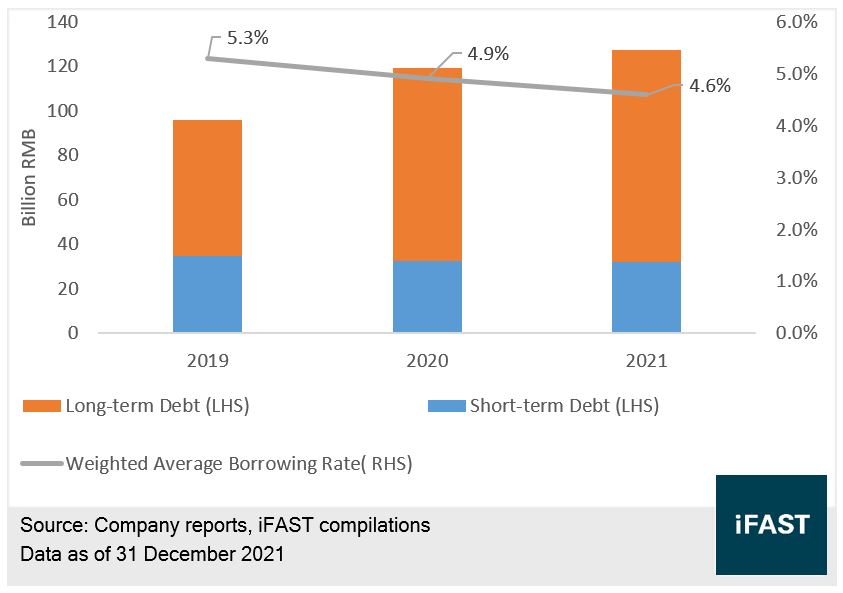
Chart 4 depicts that the weighted average borrowing cost is decreasing along with expanding interest-bearing debt, from 5.3% in 2019 to 4.6% in 2021. Furthermore, the onshore weighted average borrowing rate stood at 3.6%, closed to the borrowing rate of other central government-owned developers, like CR Land and China Overseas.
Greentown sustains a desirable offshore refinancing ability. Greentown still has access to the capital market while nearly all developers halted the refinancing in 2022, as the company issued a credit-enhancement bond due 2025 with the principal of USD 400 million on 20 Jan, and recapped a bond due 2025 with the principal of USD 150 million on 27 Feb. Not just that, the company faces diversified refinancing channels, including syndicated loans and bilateral loans.
To sum up, we consider that the liquidity will keep at a decent level with manageable credit risk given by its prominent capability of refinancing.
Chart 4: Weighted Average Borrowing Rate of Greentown
Bond due Jul 2025 is Attractive
Two bonds issued by Greentown are listed on our platform (see Table 3), and both have a three-year investment horizon on average.
Table 3: Bonds
|
Bond |
Credit Rating |
Years to Maturity |
Ask Price |
YTM |
|
BB- (S&P) |
3.0 |
95.8 |
6.3% |
|
|
BB- (S&P) |
3.2 |
95.2 |
7.4% |
|
|
Sources:Bondsupermart, data as of 22 Apr 2022 |
||||
It is noteworthy to point out that China Communication Construction Group provides a Keepwell deed for a bond due Jul 2025, leaving the bond with higher assurance for investors. The bond is currently trading around 95 with a YTM of 7.4%. Since bonds issued by other SOE developers proffer 4% or below return, we think Greentown's bonds are yielding relatively high attractiveness.
Corporate Risk
Investors should be aware of the following risks. Firstly, Greentown becomes more aggressive on development, particularly in land purchasing. The company spent RMB 96.9 billion on land, which ranked 6th among developers. Also, the spending on land purchasing accounted for 67% of attributable contracted sales. It would weaken the liquidity and cause massive cash outflow if the company retains aggressive going forward.
Moreover, Greentown has diversified business sectors, in addition to traditional residential property development, Greentown also engages in industrial property, which takes more capital input and time to develop. It suggests that these business sectors might result in a negative effect on Greentown's liquidity.
Conclusion
Greentown’s growth rate of 2021 contracted sales ranks first among the large-scale property developers in China. Simultaneously, Greentown is a leading company in the project management sector, the current circumstances may be conducive to the further development of Greentown, as the mid or small-sized developers tend to use project management services.
Greentown has two credit metrics fulfilled the requirements of regulatory policy, and it has an abundant cash balance. Despite the relatively unhealthy credit indicators concerning the off-balance-sheet debt, the company has a very strong refinancing capability as it is backed by China Communication Construction Group, a state-owned enterprise. As a result, its liquidity is expected to remain at a decent level, and the overall credit profile is controllable.
The Bond due July 2025 is relatively attractive. The bond is currently trading around 95 with a YTM of 7.4%. Since bonds issued by other SOE developers proffer 4% or below return, we think Greentown's bonds are yielding relatively high attractiveness.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a NIL position and the analyst who produced this report holds a NIL position in the abovementioned securities.









