Receive first-hand news on the latest bond issues, credit updates and special events when you join us on our Telegram channel at https://t.me/bondsupermart!
- GuocoLand reported revenue growth of 61% YoY in 1H24, driven by growth from both the property development and the investment business.
- Singapore assets continue to be the dominant profit driver, anchoring the Group’s earnings despite some volatility from the Malaysia and China business.
- GuocoLand’s credit metrics have largely moderated but the overall credit profile remains healthy and decent. We think the GUOLSP 3.400% 10Aug2025 Corp (SGD) and GUOLSP 3.290% 26Oct2026 Corp (SGD) bonds are attractively priced.
GuocoLand Limited ("GuocoLand") and its subsidiaries are a leading real estate group with operations in Property Investment and Property Development. It owns, invests in and manages a portfolio of quality commercial and mixed-use assets. The Group’s investment properties are located across its key markets of Singapore, China and Malaysia, which are also the reportable operating segments.
GuocoLand is a subsidiary of Guoco Group Limited, which is a member of the Hong Leong Group – a large financial conglomerate with multiple listed firms across Singapore, Malaysia, Hong Kong, and London. GuocoLand is headquartered in Singapore and is listed on the SGX mainboard.
1H24 Financial Results
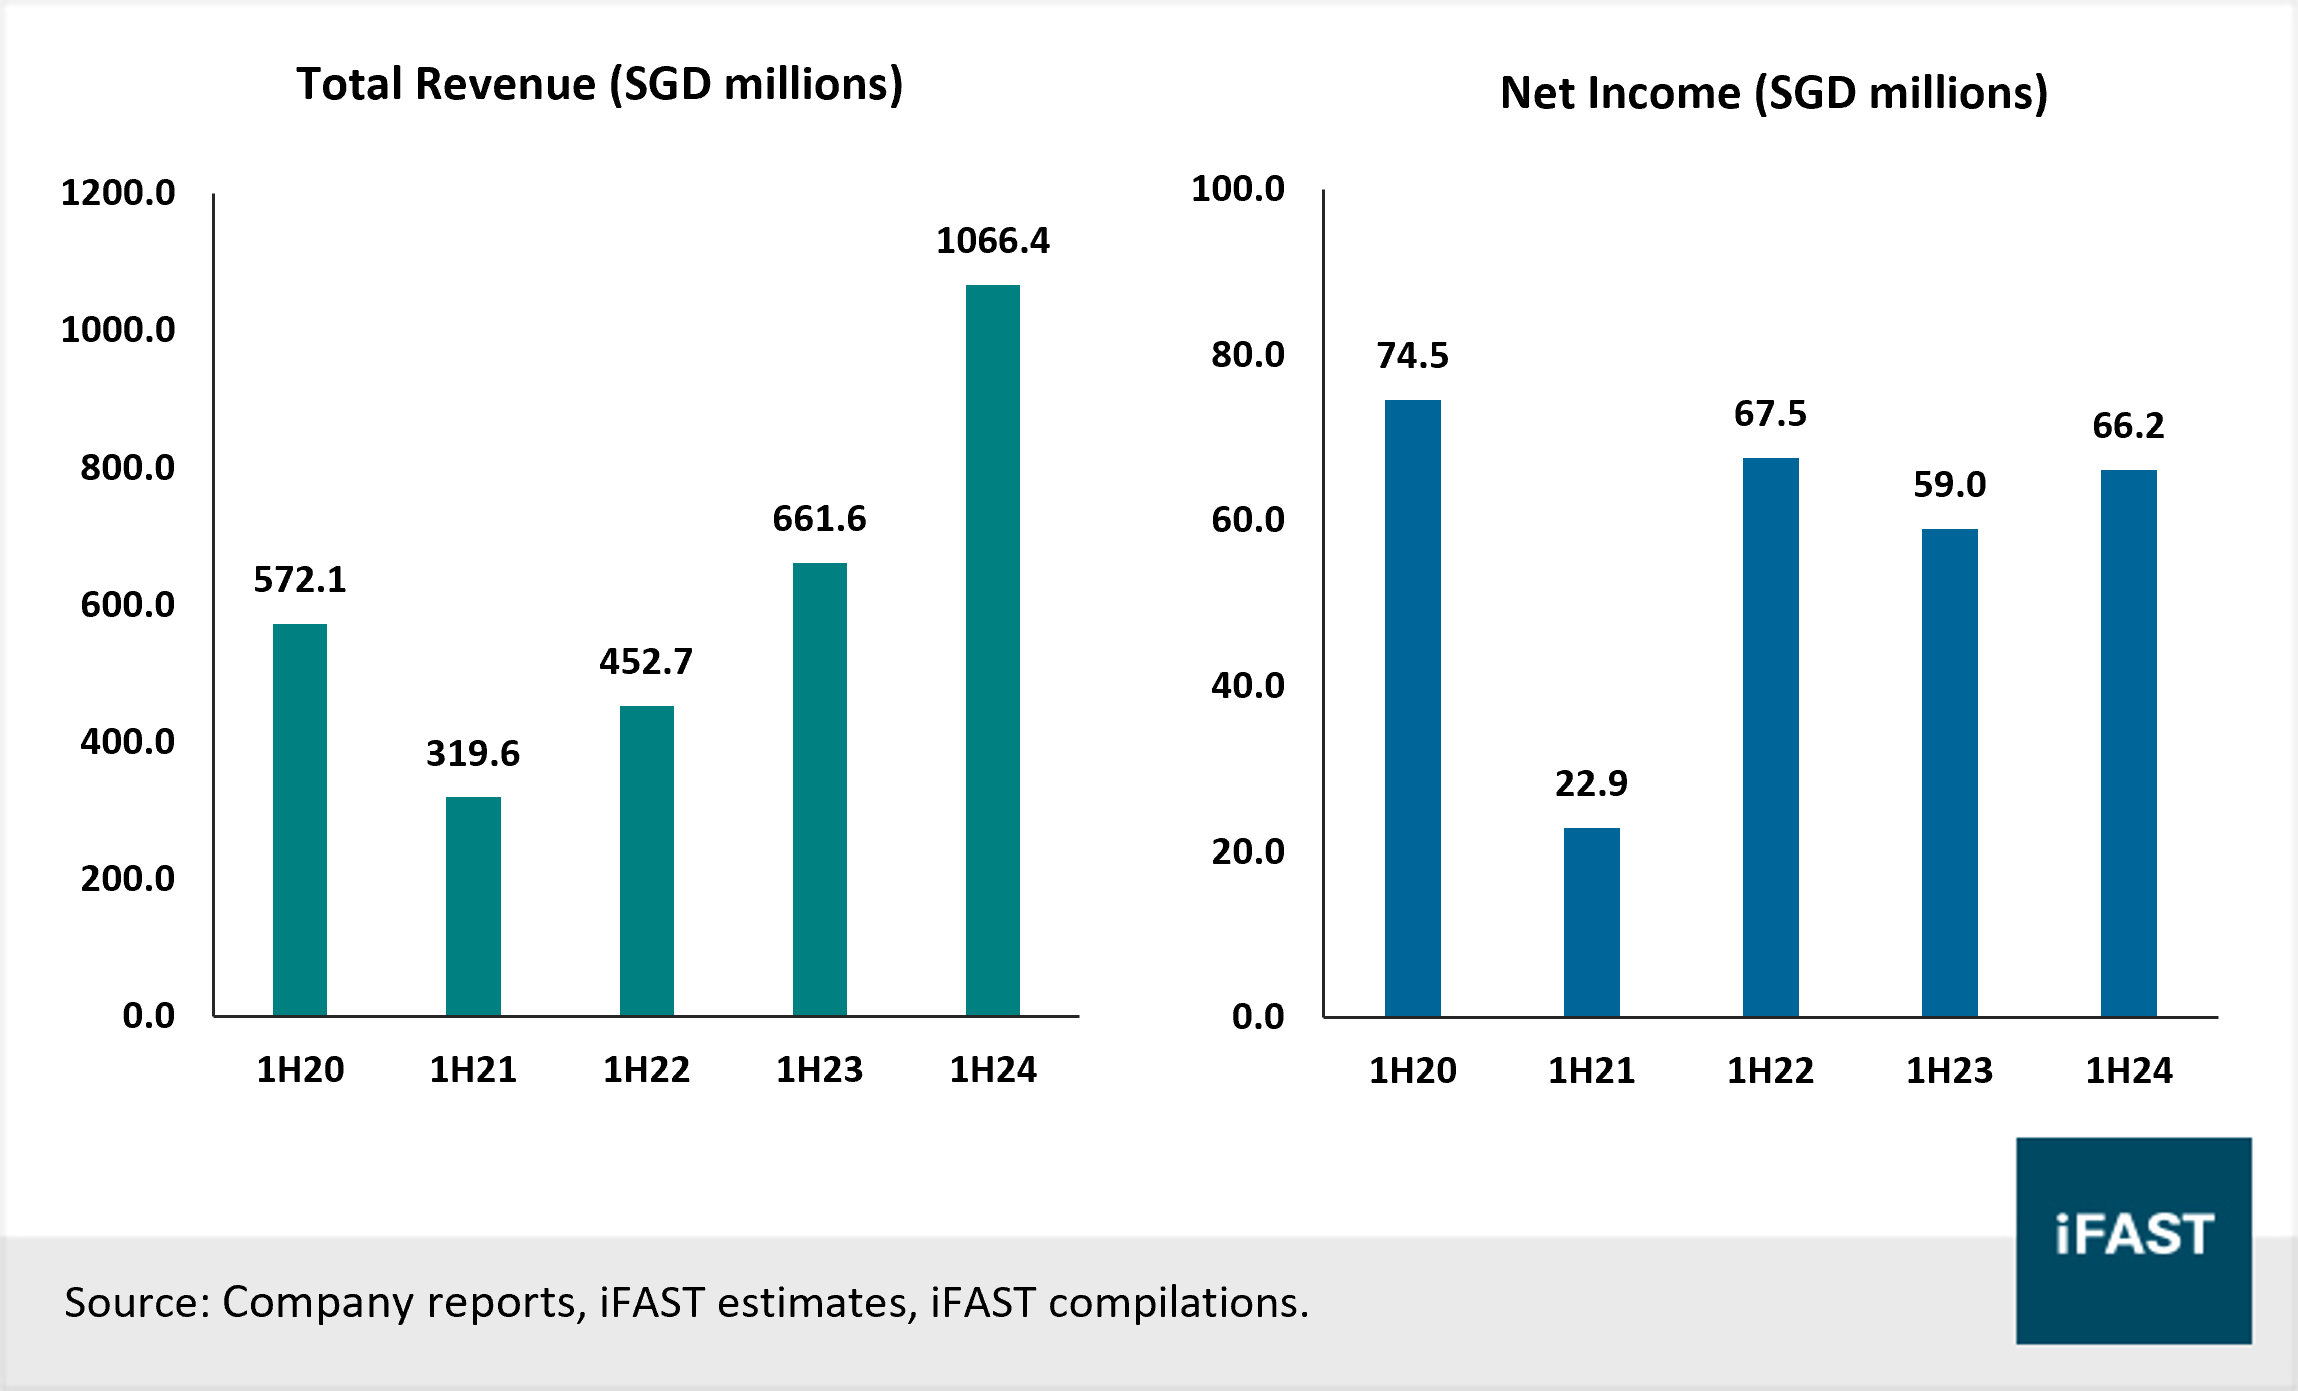
For its half-year financial results ending 31 December 2023 (“1H24”), GuocoLand reported revenue of SGD 1,066.4M (1H23: 661.6M) which was an increase of 61% year-over-year (“YoY”). The increase was driven by robust growth from both the property development and the investment business.
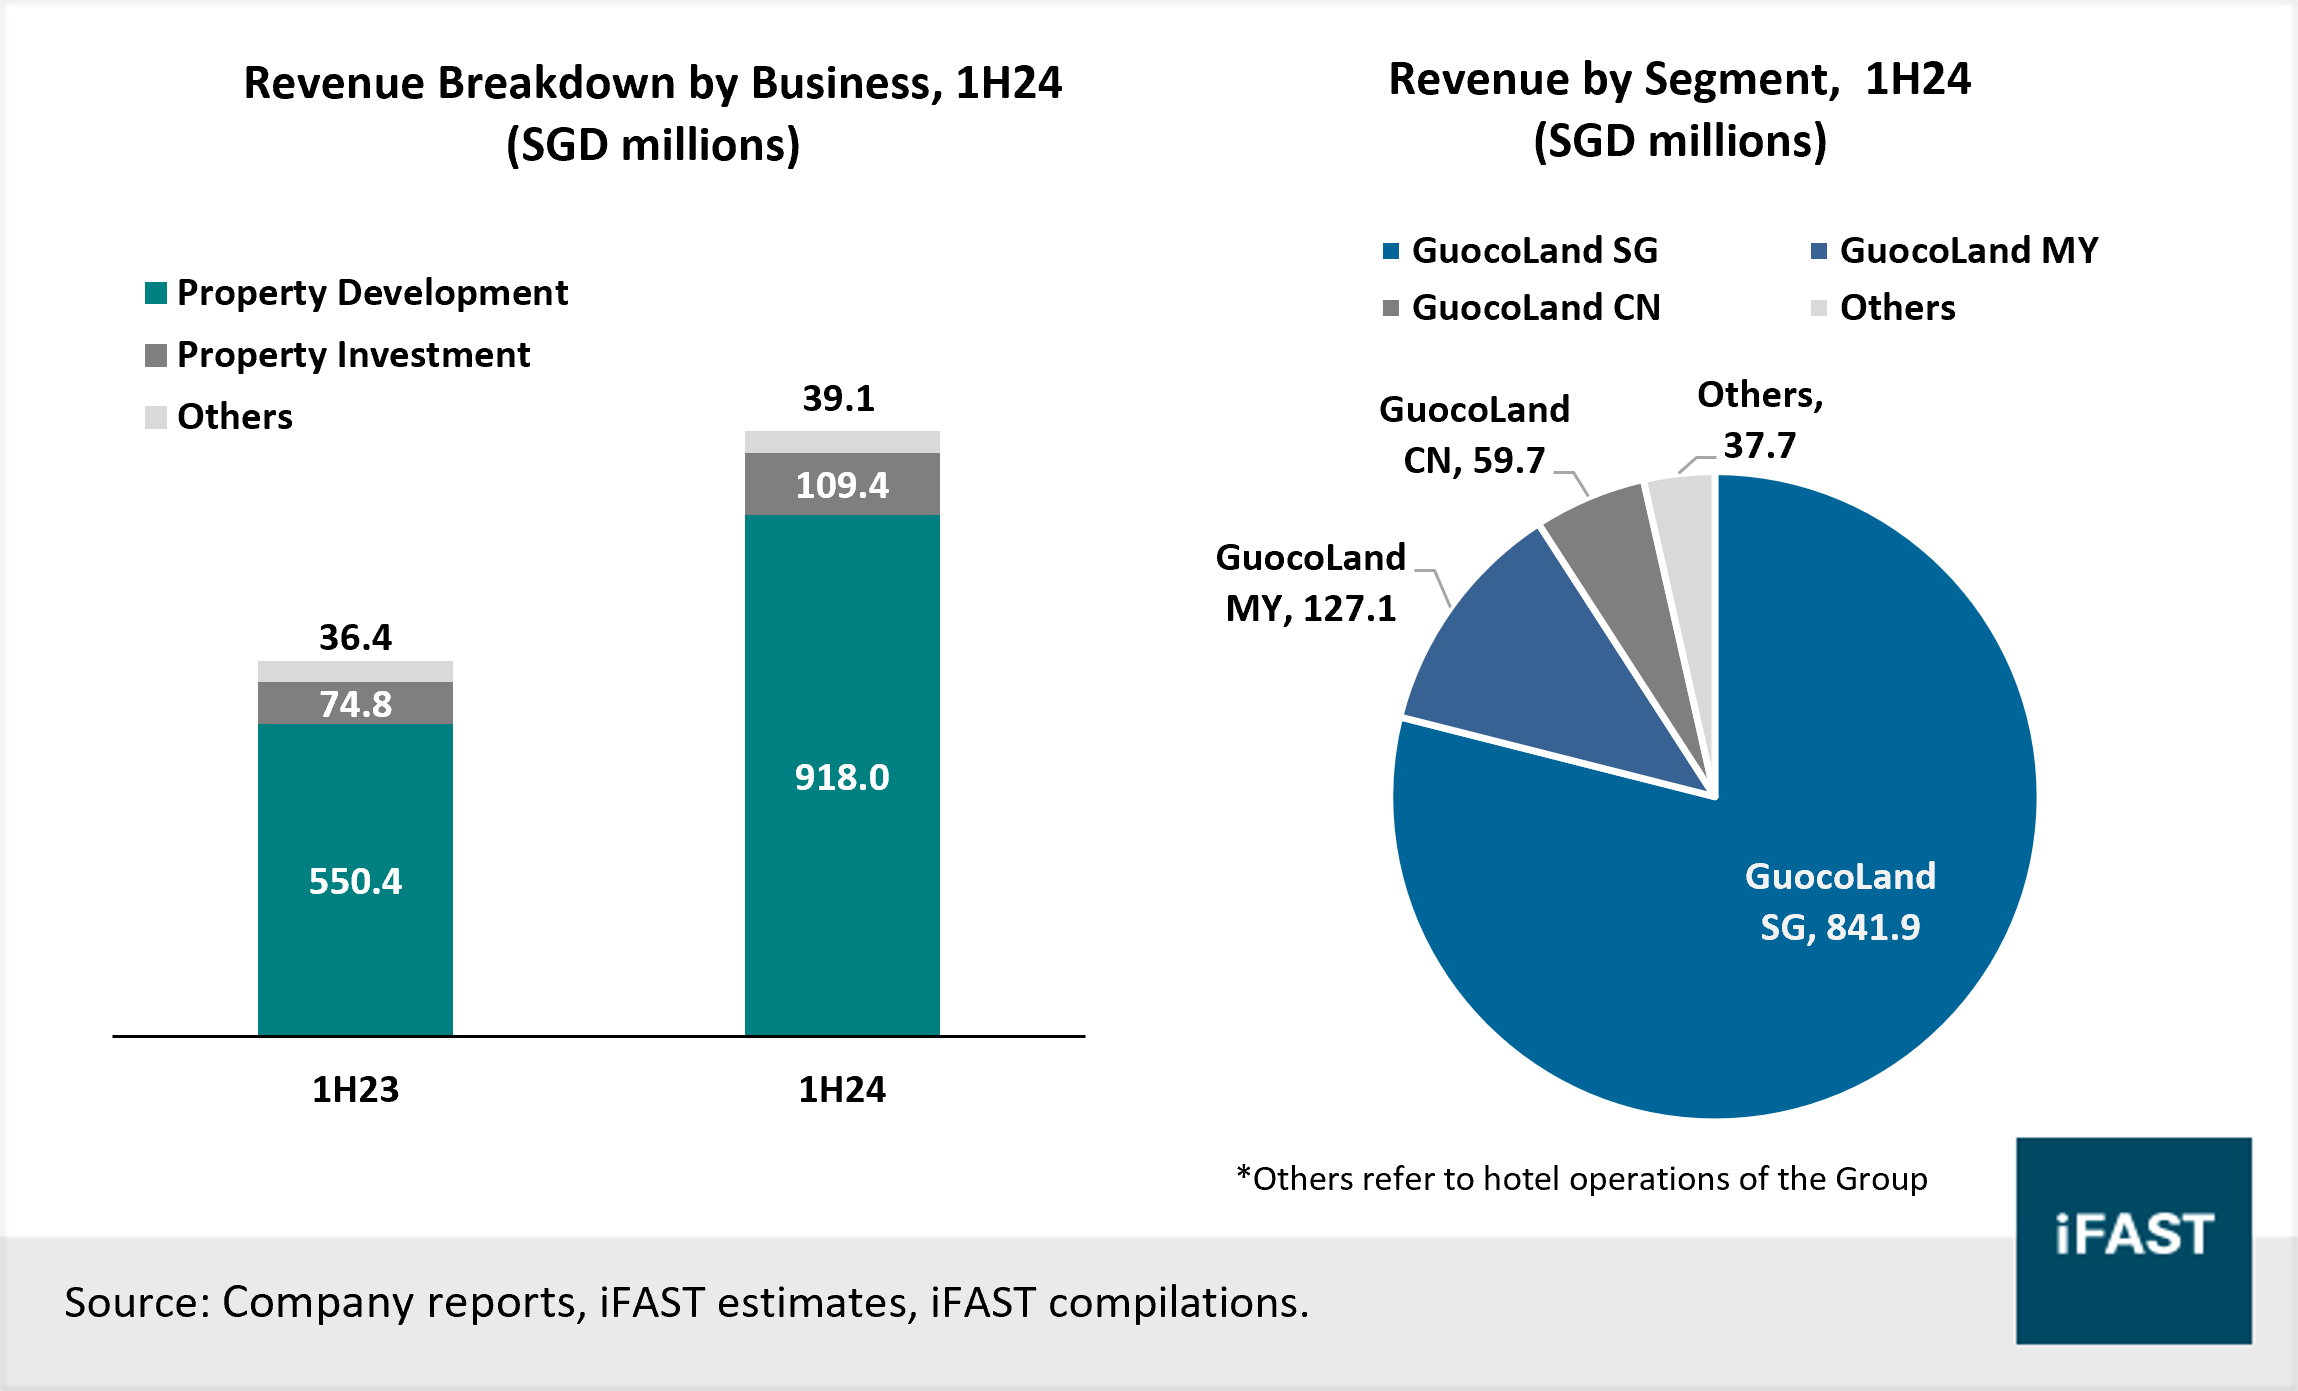
The property development business generated a 67% YoY growth to SGD 918.0M for 1H24, fuelled by higher progressive recognition of sales from high-end Singapore residential developments Meyer Mansion, Midtown Modern, and Lentor Modern. The property investment business generated a 46% YoY growth to SGD 109.4M in the same period, driven by higher recurring rental income at Guoco Midtown and positive rental reversions at Guoco Tower.
The Group’s share of results of associates and joint ventures recorded a gain of SGD 20.5M 1H24, as compared to a loss in 1H23, further contributing to financial performance. The gain can be attributed to the profit contribution from The Avenir, a joint venture residential project in Singapore.
On the other hand, GuocoLand saw a decline in other income by 55% YoY to SGD 21.3M for 1H24 without fair value gains on interest rate hedges and foreign exchange gains recorded in 1H23. Meanwhile, finance cost also increased by 87% YoY to SGD113.5M due to the higher rates backdrop and the recognition of interest expense from Guoco Midtown.
Overall, GuocoLand’s profit attributable to equity holders rose by 12% YoY to SGD 66.2M in the same period (1H23: SGD 59.0M). Excluding the fair value gains/losses, the Group also recorded a pre-tax profit growth of 42% YoY to SGD 93.1M (1H23: SGD 65.7M).
Chart 1: Revenue has risen greatly, supporting higher net income despite higher finance costs
Chart 2: GuocoLand’s Singapore business remains a key revenue driver
Business Outlook
We expect GuocoLand’s Singapore business to continue growing and remain a key revenue driver. In terms of property investment revenue, we continue to expect high occupancy rates and positive rental reversion from Singapore’s assets. Demand remains strong for the Group’s Singapore offices while rental rates for premium Grade A offices have picked up and are expected to stay strong.
Recurring income contributed by Guoco Midtown, the Group’s second integrated project, is expected to increase as the project progressively becomes operational. Full-year contribution for Guoco Midtown is expected to be in FY2024 (Jun 2024). As of 31 December 2023, Guoco Midtown has achieved a 92% pre-commitment take-up for the Grade A office tower which has a 709k sq ft net lettable area. The project also achieved full occupancy for the 50k sq ft retail space.
In terms of property development revenue in Singapore, the group has five major residential developments in Singapore (Table 1) as of 31 December 2023. A majority of these projects are projected to be completed in 2024 and we expect a steady stream of revenue to be recognised as construction progresses. Beyond the near term, GuocoLand plans to add more residential land site, with the Lentor area being a prime target. With the Group’s strong developer presence in the area, having more sites in future would be advantageous, particularly in targeting various segments of home buyers.
Statistics from URA highlighted that annual growth in non-landed private property prices (6.6% YoY) have fallen in 2023, as compared to the prior year (8.1% YoY). This is likely due to higher mortgage rates, rising housing supplies, and property cooling measures which may continue to weigh down prices this year. Despite pressure on property prices, consensus are expecting demand to improve as buyers return to the market. Meanwhile, more than 95% of the units have been sold for GuocoLand’s high-end developments (Meyer Mansion, Midtown Modern and Lentor Modern). This shows that the Group has strong demand, possibly due to branding and past projects, despite a softer economic backdrop.
Overall, we continue to expect Singapore assets to be GuocoLand’s dominant profit driver. While profit from Malaysia or China business may remain volatile, Singapore’s business should remain stable and anchor the Group’s earnings. Due to the major residential developments this year, maiden full year contribution from Guoco Midtown, and the recurring Singapore property investment revenue, the Group should continue to experience earnings growth moving forward.
Table 1: Major upcoming residential developments in Singapore
|
Project
|
Units sold (as of 31 Dec '23)
|
Expected Completion
|
|
Meyer Mansion
|
99%
|
Q1 2024
|
|
Midtown Bay*
|
58%
|
Q2 2024
|
|
Midtown Modern*
|
96%
|
Q4 2024
|
|
Lentor Modern
|
95%
|
Q2 2026
|
|
Lentor Hills Residences*
|
73%
|
Q4 2026
|
|
Source: Company
reports Data as of 31 Dec 23 *Jointly developed with partners.
|
Credit highlights
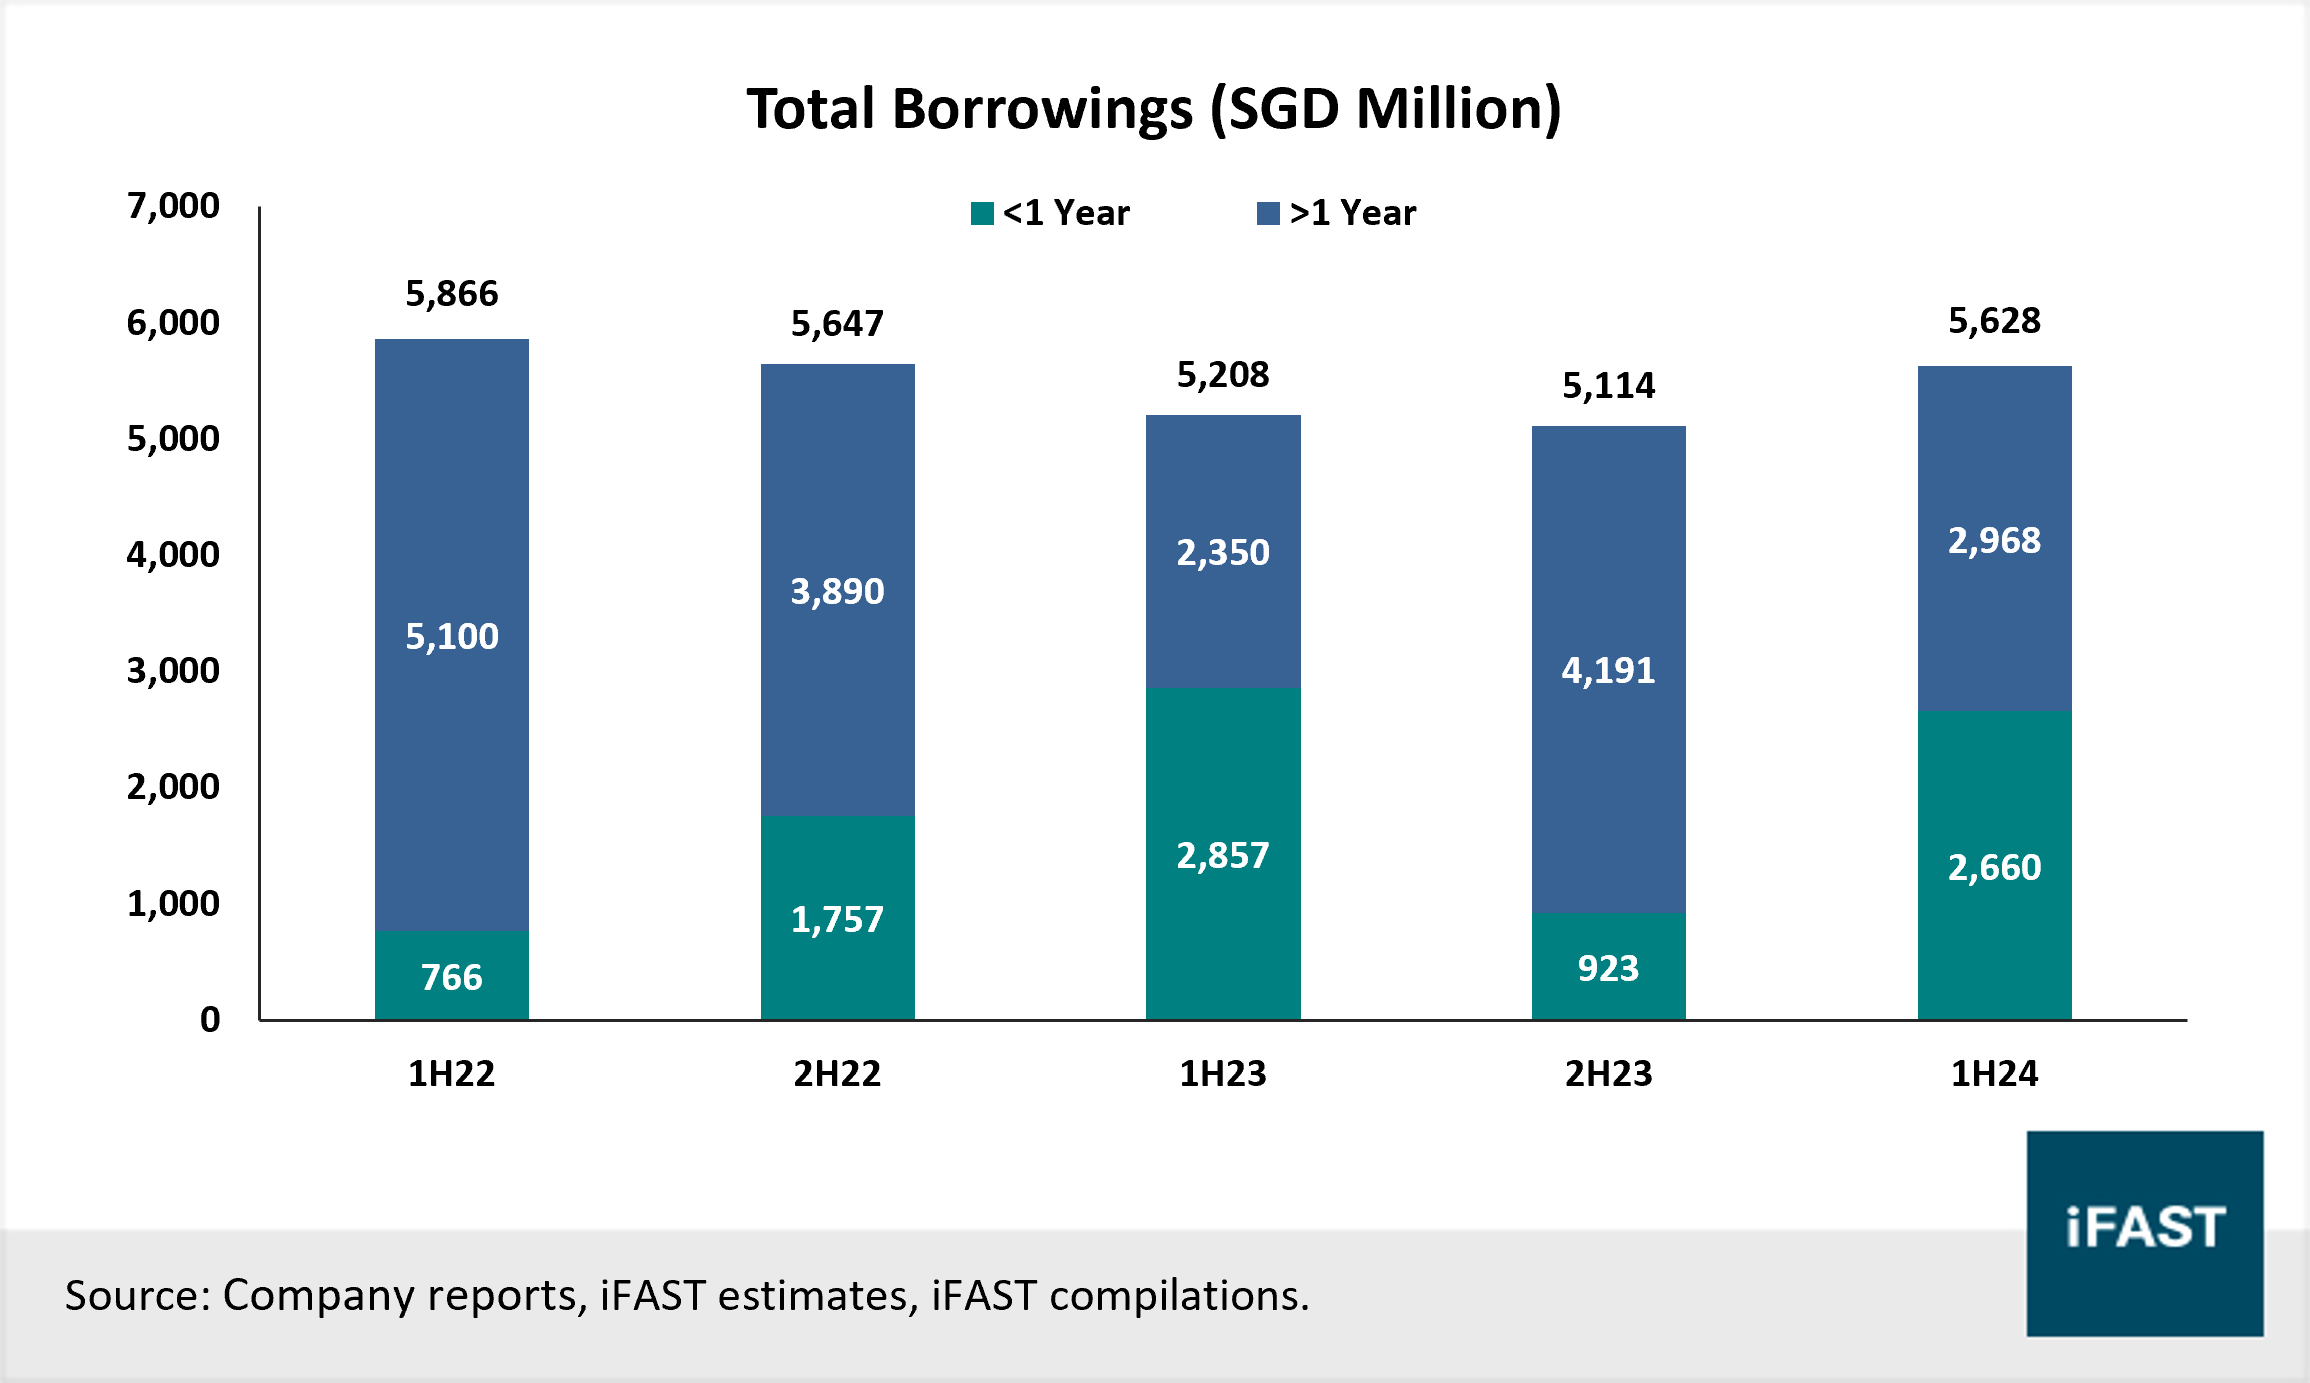
For 1H24, total borrowings rose 10% half-on-half (“HoH”) to SGD 5.6B. A majority of the increase came from short-term secured borrowings which amount to SGD 2.1B, growing 388% HoH, due to financing of the new Lentor Mansion site. Despite the large jump, nearly 80% of short-term borrowings are secured by investment and development properties, with 75% of the Group’s properties based in Singapore. Also, borrowings are mostly concentrated in Singapore assets, which we deem to be more resilient.
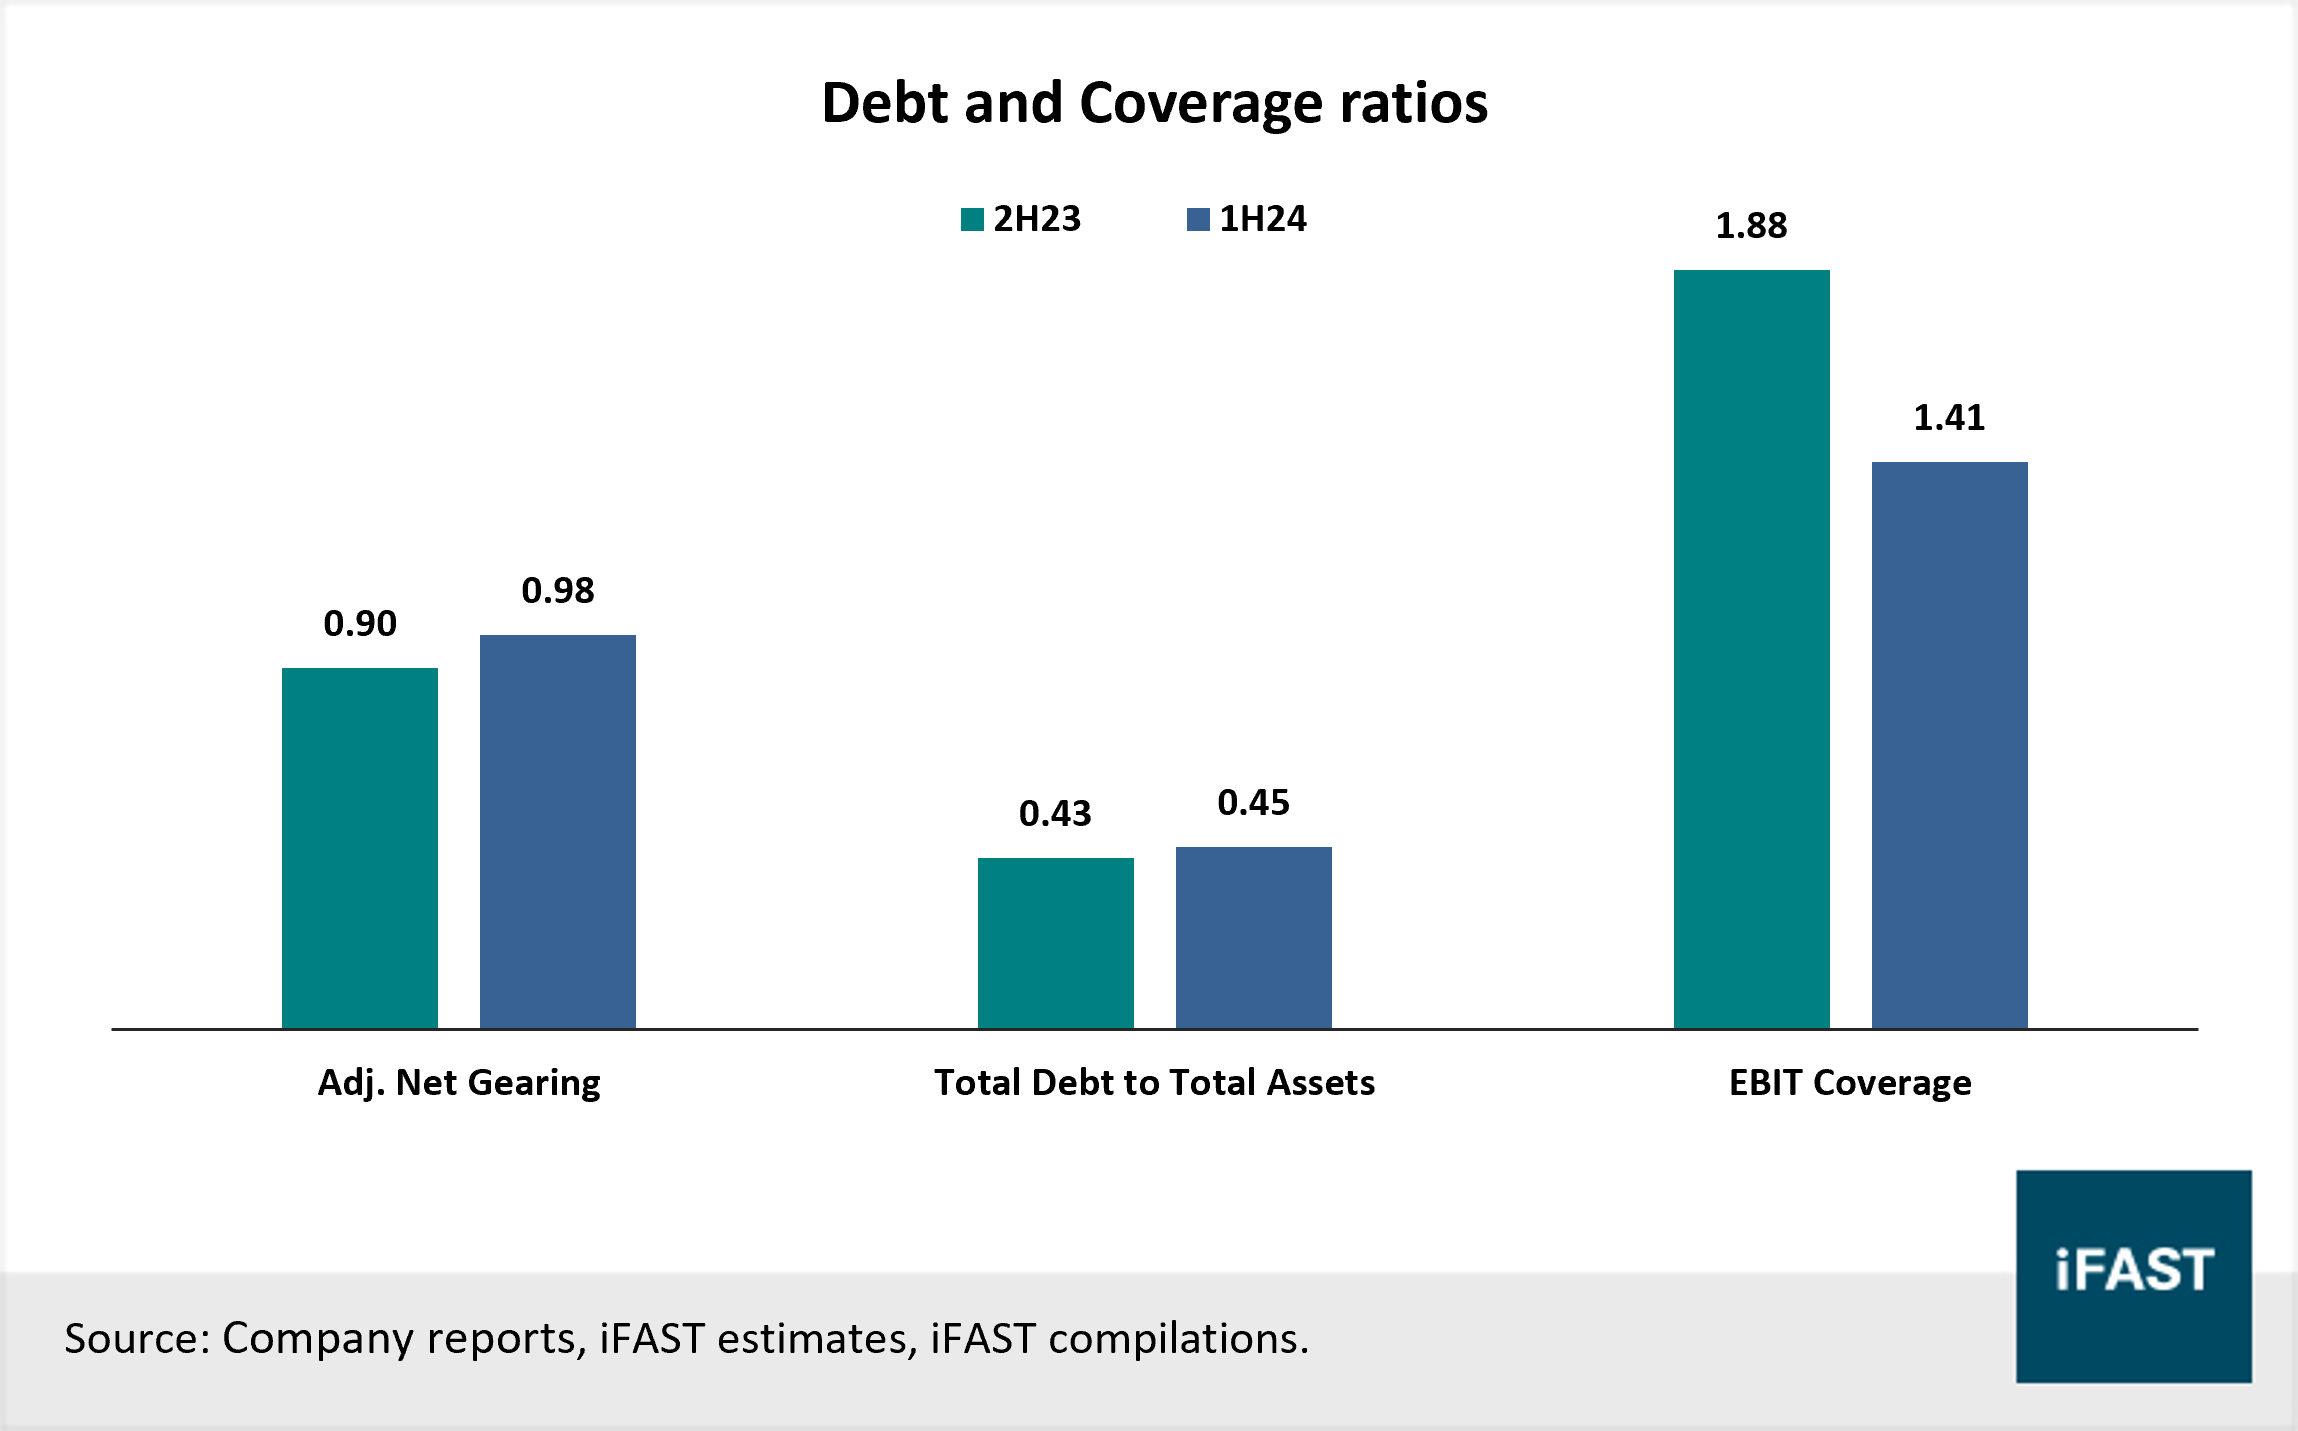
Due to higher borrowings in 1H24, debt ratios have worsened slightly but exhibited a trend of normalisation (back to pre-covid levels) rather than deterioration. Total debt-to-asset rose slightly to 0.45 in 1H24 from 0.43 in 2H23, reversing from a post-covid low. Estimated net gearing (adjusted for perpetual securities) was 0.98 in 1H24, rising from 0.90 in 2H23. The ratio also reversed from post-covid low and back to levels seen in 2021 and 2020. Higher finance cost has also drove interest coverage lower. Estimated EBIT-to-finance cost was 1.4x in 1H24, falling from 1.9x in 2H23.
GuocoLand managed to improve its liquidity profile by growing its cash position by 13% HoH to SGD 1.0B in 1H24 from SGD 0.9B in 2H23. Nonetheless, short term borrowings continue to exceed cash position, which has been the case since 2H22. However, we believe the Group is unlikely to face difficulties in meeting this obligation as ongoing sales from the Singapore residential projects (highlighted in the above section) will help to pare down property development loans.
Chart 3: Total borrowings have picked up, driven by short-term debt
Chart 4: Debt and coverage ratios have slightly moderated
Recommendations
Table 2: GuocoLand fixed rate bonds
Table 3: Bond issuances from comparable peers
GuocoLand’s credit metrics have moderated as debt ratios and interest coverage have weakened after a rise in borrowings and finance cost. However, credit profile remains decent as borrowings are backed by resilient Singapore assets while proceeds from upcoming development will help pare down borrowings.
Comparing GuocoLand’s issuances to that of other property developers, we find that yields are higher which is likely due to the Group’s issuances having a larger credit spread. However, with a decent credit profile, GuocoLand’s issuances offer a nice yield pickup. We like the GUOLSP 3.400% 10Aug2025 Corp (SGD) and GUOLSP 3.290% 26Oct2026 Corp (SGD) bonds which are recommended for investors who seek a stable income for within the next three years. On the other hand, we find the pickup from GuocoLand’s 2028 bond less attractive for an additional twenty one months to maturity. Amongst the comparable bonds, we also like those from Frasers Property due to the stronger issuer credit profile which explains for the slight difference in yields.
Amongst SGD perpetual securities issued by property developers, we think GUOLSP 4.600% Perpetual Corp (SGD) is fairly priced, with a yield to next call (“YTC”) of 5.5% and around four months to its call date. That said, we see a risk of non-call for GuocoLand’s perps given its current financing needs, a tighter liquidity profile, and the higher rates environment. The perp also has a later reset date at 23 Jan 2025 which does not incentivise the Group to redeem early (the Group did not redeem on its first call date, 23 Jan 2023). Between the Group's perpetual and fixed rate bonds, we prefer the latter.
Table 3: Perpetual bonds from comparable peers
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) hold a position in GUOLSP 3.290% 26Oct2026 Corp (SGD) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!