- Property development has been a key driver of revenue, but property investment and management have provided a more stable cashflow.
- Credit profile is generally decent with a substantial cash position while being able to obtain financing mostly with ease.
- We favour WINGTP
4.350% Perpetual Corp (SGD) for its potential current yield upon reset, but
also an attractive yield to reset if it gets called.
Wing Tai Properties Limited
Financial Highlights
In six months ended 30 June 2022 (“1H22”), WINGTP recorded total revenue of HKD 859.8m, improving from HKD 496.8m in 1H21. Similarly, we saw an improvement in profit at HKD 404.8m in 1H22, as compared to a lower HKD 219.6m in 1H21. Across the three segments, property development and property investment & management had been the more significant driver of revenue and profits. Of the HKD 859.8m revenue recorded in 1H22, HKD 480.3m (~55%) was attributable to property development while HKD 300.5m (~35%) was attributable to property investment and management. The trend had been similar in previous years (chart 1).
Chart 1
Revenue (excluding inter-segment sales) in HKD
m
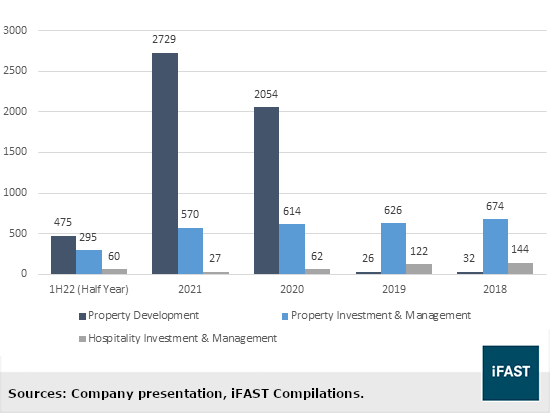
Chart 2
Profit (or losses) before taxation in HKD m
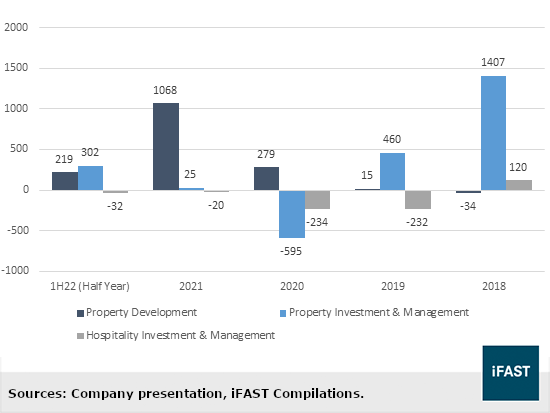
Between the two operating segments of the
company that is of greater significance, property investment & management
had been the stable source of revenue for WINGTP, despite the fluctuations
observed in the profits due to changes in investment properties’ value. The
devaluation in investment properties had been the most significant in 2020 as a
result of the COVID-19 pandemic and fall in interest rates – despite revenue in
the segment coming to a significant HKD 614m, net loss was at HKD 595m mostly
due to the negative net change in investment properties and financial
instruments including joint ventures. Nonetheless, we would like to point out
that the net cash generated from operations for this segment generally remains
positive, in which it had been able to draw in a much more consistently
positive cashflow from operations in comparison to property development.
For property development, there remain three projects under development as of 1H22, with OMA by the Sea expected to be completed by end of 2022. This development has pre-sold around 90% of the residential units as of 1H22, a huge contributor to the revenue observed in the same period. In its mid-to-long term plans, WINGTP intends to further expand the land bank through participation in government land tenders and private agreements
Of the two remaining projects under development, WINGTP expects one to be completed in 2024 (commercial site at Graham Street), and the other to be completed beyond 2024. We have higher expectations on the commercial site, which WINGTP holds a 50% stake in, given the recent easing of restrictions. The commercial site will be developed into a Grade A office tower with hotel and retail shops components, at a massive gross floor area of up to 433,500 square feet in comparison to the average ~200,000 square feet of residential developments completed in recent years. However, we expect revenue from property development to likely stay limited until the launch of the upcoming projects for sale.
For property investment and management, WINGTP has properties present in Hong Kong, London and Beijing with a focus on properties in Hong Kong. The portfolio primarily comprises Grade A office buildings with an aggregate attributable fair market valuation of around HKD 22.3b as of 1H22 – 1,633,000 square feet in Hong Kong, 328,000 square feet in London and 6,200 square feet in Beijing. Occupancy rates in two major properties in Hong Kong, Landmark East and Shui Hing Centre, are at 86% and 81% respectively in 1H22 – which changed marginally to 85% and 87% respectively as of 31 December 2022. WINGTP indicated the intention to redevelop Shui Hing Centre while looking out for new opportunities with a focus on Hong Kong and London to generate greater returns.
With Hong Kong opening up its borders to foreigners, we are expecting to see a greater influx of people and demand for properties to continue in Hong Kong. As lives gradually return to pre-COVID-19 norms, occupancy rates on the Hong Kong properties are likely to further improve – which would provide a crucial stable income for WINGTP. Similarly, with the reopening of borders for tourism, we expect to see greater revenue and profit drawn in through its hospitality segment as well.
Credit and Liquidity Profile
As of 30 June 2022, total borrowings amounted to HKD 6,662m while current borrowings repayable within a year were HKD 3,113m. Of the total borrowings, bank borrowings stood at HKD 4,510m (~68%), while fixed-rate bonds were at HKD 1,643m (~25%), with the remaining being loans from non-controlling interests. WINGTP indicated that the majority of their borrowings are on a floating rate basis, although we understand that it also possesses interest rate swap contracts to an uncertain amount. It reflected that it continues to “closely monitor the exposure to interest rate fluctuations and, if appropriate, hedge by interest rate swap contracts to the extent desirable.”
While it appears to have a significant sum of current borrowings, it does not pose a huge issue for WINGTP, considering substantial bank balances & cash and unutilised revolving loan facilities amounting to a total of HKD 4,657m. As such, the company’s net gearing ratio (calculated by net borrowings over total equity) was at a relatively healthy 16.7% - falling from 19.0% as of 31 December 2021. In addition, WINGTP pledges of its assets to the Group’s and joint ventures’ credit facilities – of the total HKD 7,269m dedicated for pledging, only HKD 3,061m were utilized for the existing secured borrowings. It is likely for the company to refinance its current borrowings with the pledging of available assets to control the cost of borrowing.
Table 1
WINGTP’s Cash Position
|
1H22 (Half Year) |
2021 |
2020 |
2019 |
2018 |
|
|
Bank balances and cash (in HKD m) |
1,963 |
1,465 |
1,190 |
1,740 |
2,873 |
|
Sources: Company presentations, iFAST Compilations. |
|||||
We would like to highlight that WINGTP generally keeps substantial cash reserves in place, necessary to sustain the business operations given the fluctuating cashflow from property development. Furthermore, we observed that WINGTP has been able to adequately support its business operations through financing activities over the years, which is a crucial factor in justifying its credit quality (coupled with the pledging of its assets in allowing them to obtain the necessary financing).
Overall, while WINGTP’s credit profile is not exceptional, it remains decent with its ability to fund operations through financing activities alongside its prudent use of cash. With the last issuance of debt (in this case, perpetual securities that are not even accounted for under debt) in 2017, we have reasons to believe that bank borrowings have been its preferred method of financing, possibly due to preferential rates given their pledging of assets. Despite minimal cashflow until 2024 with a lack of projects in property development, WINGTP is likely to continue supporting the necessary interest expenses with stable revenue from property investment & management, or else with financing if needed.
Recommendations
WINGTP 4.350% Perpetual Corp (SGD) is its only SGD issuance, aside from other issuances from its staking holding company WINGTA – which WINGTA 4.480% Perpetual Corp (SGD) would be the only suitable counterpart for comparisons.
WINGTP 4.350% Perpetual Corp (SGD) currently has an ask price of 92.89 as of 1 February 2023 and a current yield of 4.68% on the coupon. The perp has previously missed the first call date in 2020 mostly due to the COVID-19 pandemic affecting business operations, as highlighted in the previous credit update for WINGTP here, while it remains callable on every semi-annual coupon payment date. In addition, the perp resets on the 24 August 2027 and every 10 years after, based on the 10-year SOR rate plus initial credit spread of 208.7 basis points (“bps”) plus step up margin of 100 bps.
The 10-year SOR rate is 3.15% as of 1 February 2023, indicating a reset rate of 6.237%. This translates to a current yield of 6.71% assuming the entry price of 92.89. However, if we take the average figure of 10-year SOR rate in the past decade at 2.23%, the reset rate will be at 5.317%, translating to a current yield of 5.72% with the same entry price.
The option-adjusted spread on the issue is at 267 bps as of 1 February 2023, which against the total margin of 308.7 bps implies a possibility of redemption of the issue on the reset date. We would like to note that this ultimately depends on the credit quality of the company over the next 4.56 years till the reset date. The yield to reset is at 6.15% at the ask price of 92.89.
We like the issue given the price is below par, which a likely fall in interest rates by the reset date in 2027 allows for a rise in the price (and hopefully a pull-to-par if the likelihood of call rises significantly by then). In such a scenario, investors in the issue may benefit from the increment in price by selling it off on the secondary market.
Table 2
WINGTP and WINGTA SGD Issuances
|
Issue |
Ask Price |
Current Yield |
First Reset Date |
Yield to Reset |
Reset Rate |
|
92.89 |
4.68% |
24 Aug 2027 (every 10 years thereafter) |
6.15% |
10 YR SOR Rate + Initial Credit Spread (208.7 bps) + Step Up Margin (100bps) |
|
|
98.88 |
4.53% |
24 May 2024 (every 5 years thereafter) |
5.47% |
Prevailing SGD 5Y SOR + the Initial Spread (2.562%) + Change of Control Margin (100 bps step up on 24 May 2029) |
|
|
Sources: Bloomberg Finance L.P., Bondsupermart, iFAST Compilations. Data as of 1 February 2023. |
|||||
Between the two issues, WINGTA 4.480% Perpetual Corp (SGD) is less likely to call on the first reset date of 24 May 2024, given the lack of a step-up margin on the first reset date. The step-up margin is only applicable upon change of control or on the first step-up date in 2029. At the same time, the price being close to par reflects earnings for the investors to come through the coupon more than the possible appreciation in price – the coupon and consequent current yield do not justify the risk required for a perp as compared to the risk-free rates.
Therefore, we favour WINGTP 4.350% Perpetual Corp (SGD) for its potential current yield upon reset, which is highly considerable when we see a fall in interest rates. On the other hand, the price below par allows for substantial gains upon call, and even in non-call situations, a possible appreciation in price allows investors to take profit from the investment.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!