Highlights:
- CK Hutchison is a global conglomerate with main businesses in ports, retail, infrastructure, telecommunication and energy. The Group’s cash flow growth was decent. The result highlights are retail and investment segments.
- The Group keeps selling the assets to lower the leverage level, with strong credit metrics. The overall credit risk is low.
- The yield to maturity of CK Hutchison’s bonds is around 5.4% to 5.7%, higher than US Treasury of around 30 bps to 80 bps, which has certain attractiveness. The bonds are suitable for stable income seekers.
CK Hutchison is a global conglomerate with main businesses in ports, retail, infrastructure, telecommunication and energy. The Group is listed on HKEX (Stock Code: 1.HK), with a current market capitalisation of around HKD 147.5 billion.
CK Hutchison’s Chairman, LI Tzar Kuoi, suggested that “COVID is a stress test” during the COVID period. For CK Hutchison, can the Group deliver satisfactory results and pass the "stress test"?
Decent Cash Flow Growth, with Highlights in Retail and Investment Segments
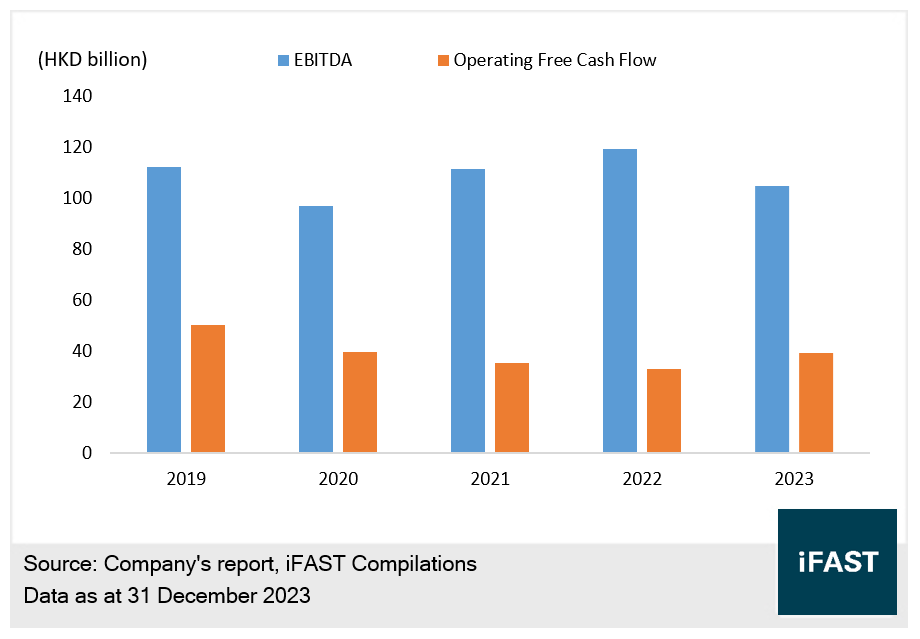
As shown in Chart 1, CK Hutchison’s EBITDA in 2023 was around HKD 104.9 billion, decreased by 12% YoY, mainly due to the tower disposal in the UK in 2022 and the high base effect caused by the acquisition gain from the Indonesian telecom business. Excluding the impact from these factors, the Group’s EBITDA only decreased 1% YoY. The operating free cash flow increased 20% YoY to HKD 39.5 billion. The cash flow growth was decent.
Chart 1: CK Hutchison’s EBITDA and Operating Free Cash Flow
CK Hutchison has 293 operational berths in the ports and related services segment. In 2023, its ports handled a total of 82.1 million TEUs, a 3% YoY decline. In addition, since the supply chain disruption and port congestion gradually eased, the warehousing revenues recorded a 22% YoY decline. Therefore, the Group’s EBITDA only amounted to about HKD 13.6 billion. The performance of this segment was fair.
CK Hutchison’s retail division, which means the subsidiaries under AS Watson Group, still has some growth ability in this segment. The Group's EBITDA for 2023 rose by 13% YoY to HKD 16.2 billion due to the factors such as the gradual recovery of the global economy and the normalisation after COVID. The Group continues to expand its business around the world.
For the infrastructure segment, the Group's EBITDA for 2023 rose marginally by 3% YoY to HKD 29.2 billion, which is still a low single-digit growth. The overall performance remained stable as usual.
After the disposal of the tower business in the UK, CK Hutchison’s EBITDA from the telecommunication business was HKD 22.3 billion, which decreased by 8% YoY (excluding the one-time gain from the disposal). Despite the telecommunication revenues mainly correlated to inflation, the speed of cost inflation, such as the energy cost, network cost and operating costs, was higher than that of revenue growth. Therefore, it was reasonable that this segment recorded a negative EBITDA growth.
For the Finance & Investments and Others segment, CK Hutchison’s performance was relatively stable. Its EBITDA increased 6% YoY to around HKD 19.5 billion, mainly driven by the realized gain of non-core assets and the higher cash return given the higher interest rate. Under the higher for longer interest rate scenario and high energy prices, we believe that this segment will perform well going forward.
Overall, CK Hutchison’s businesses are resilient and well-diversified in terms of businesses and regions. The profitability and cash flow performances are stable. We believe that CK Hutchison already passed the “stress test” suggested by the chairman, LI Tzar Kuoi. In the future, the operating performance should be maintained at a decent level.
Keep Selling Assets to Lower Leverage Level, with Strong Credit Metrics
After CK Hutchison sold a number of telecommunication businesses in the past two to three years, the net debt dropped to HKD 220.3 billion. The net gearing ratio was lower to 33% (See Table 1). The net debt / EBITDA and net debt / operating free cash flow were 2.1 times and 5.6 times respectively. The leverage level was decent.
CK Hutchison’s interest coverage ratio was high at 8.5 times, with a lower cost of borrowing of 3.2%. The credit metrics were strong. Overall, the credit risk was low.
Table 1: CK Hutchison’s Credit Metrics
|
2021 |
2022 |
2023 |
|
|
Net Debt (Including Perpetual Debts) (HKD billion) |
270.9 |
219.4 |
220.3 |
|
Net Debt / EBITDA (times) |
2.4x |
1.8x |
2.1x |
|
Net Debt / Operating Free Cash Flow (times) |
7.7x |
6.6x |
5.6x |
|
Net Gearing Ratio (%) |
42.9% |
35.1% |
33.1% |
|
Current Ratio (times) |
1.3x |
1.3x |
1.2x |
|
Cash To Short-term Debt (times) |
1.9x |
1.7x |
1.8x |
|
Interest Coverage Ratio (times) |
10.1x |
12.6x |
8.5x |
|
Average Cost of Borrowings (%) |
1.6% |
2.0% |
3.2% |
|
Source: Company’s Reports, iFAST Compilations Data as of 31 December 2023 |
|||
CK Hutchison’s Bonds are Suitable for Stable Income Seekers
CK Hutchison’s credit rating is A / A- (S&P / Fitch). The bonds have the same rating.
Given the Group’s decent profits and cash flows and diversification in terms of businesses and regions, we believe that the Group’s overall default risk is low. Investors could consider the bonds with different tenors.
As shown in Table 2, CK Hutchison’s bond yields are around 5.4% to 5.7%, higher than treasury yields of around 30 bps to 80 bps. They have a certain attractiveness. The bonds are suitable for stable income seekers.
Table 2: CK Hutchison’s USD Bonds
| Bond Name | Years to Maturity | YTM |
| CKHH 2.750% 03Oct2026 Corp (USD) | 2.5 | 5.4% |
(债券快线成员) | 4.0 | 5.4% |
| CKHH 5.375% 26Apr2029 Corp (USD) | 5.0 | 5.4% |
| CKHH 2.500% 08May2030 Corp (USD) | 6.0 | 5.4% |
| CKHH 4.875% 21Apr2033 Corp (USD) | 9.0 | 5.6% |
| CKHH 5.500% 26Apr2034 Corp (USD) | 10.0 | 5.7% |
| CKHH 3.375% 08May2050 Corp (USD) | 26.0 | 5.6% |
Source: Bondsupermart Data as of 26 April 2024 | ||
Amongst
these, CK Hutchison’s 2028 USD bond "
CKHH 4.750% 21Apr2028 Corp (USD) " is now available on Bond Express, allowing investors to enter at a
lower cost. Investors coukld also consider the newly issued bonds,
CKHH 5.375% 26Apr2029 Corp (USD) and
CKHH 5.500% 26Apr2034 Corp (USD).
The trading liquidity could be better.
Related Risks
CK Hutchison holds a number of joint ventures and associates. Many of them are partners with other companies under the “Cheung Kong” Group and Mr. Li Ka Shing family. On one hand, this artificially lowers the liability level at the holding company level, which may cause the actual leverage to be higher than the book value. On the other hand, if Mr. Li Ka Shing’s family encounters any issue in their personal finance, it might have a greater impact on the Group's operations.
The intensive geopolitical conflicts might result in a higher risk in operations and execution. For example, CK Hutchison’s Gdynia Container Terminal in Poland was subject to increased regulation by the Polish government on national security grounds after the Group refused to allow a U.S. warship, which was supplying Ukraine with military supplies, to berth in the port during 2023. These political events might adversely affect the Group’s operations.
Conclusion
CK Hutchison is a global conglomerate with main businesses in ports, retail, infrastructure, telecommunication and energy. The Group’s cash flow growth was decent. The result highlights are retail and investment segments.
The Group keeps selling the assets to lower the leverage level, with strong credit metrics. The overall credit risk is low.
The net yield to maturity of CK Hutchison’s bonds is around 5.1% to 5.6%, higher than the US Treasury of around 30 bps to 80 bps, which has certain attractiveness. The bonds are suitable for stable income seekers.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds CKHH 4.750% 21Apr2028 Corp (USD) position and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!