Receive first-hand news on the latest bond issues, credit updates and special events when you join us on our Telegram channel at https://t.me/bondsupermart!
Highlights:
- Greentown’s contracted sales in 1H2022 declined by 34%, but still outperformed the market average, and the industry ranking moved up to Top 10. Greentown's land spending in 1H2022 remains large, leaving it potential for further development.
- Solvency profile remained roughly unchanged, particularly, the liquidity topped among homebuilder peers. The overall credit risk is manageable.
- Bond due in 2025 is yielding approximately 14%, a rather attractive choice for consideration.
As a developer with a state-owned enterprise (SOE) background, Greentown China Holdings Limited ("Greentown" hereafter) keeps a high pace of development over the past few years. In this “Idea of the Week” article, we will dive into the latest financial statements of Greentown, to see if the company would be worthy of consideration.
1H2022's performance Outperformed the Market with a steadily Increasing Industry Ranking
In relation to property sales (Table 1), the sluggish property market has caused a remarkable blow to the performance of Greentown in spite of its good track records between 2019 and 2021, which grew by over 20% YoY. 1H2022's contracted sales of Greentown slumped by 34.3% to RMB 112.8 billion, but still outperformed the average plummet of 50% for the top 100 developers. We see that the industry ranking trends upward, from 24th in 2019 to 10th in mid-2022, hence Greentown could be regarded as a large-size developer.
Table 1: Contracted Sales of Greentown
|
Contracted Sales (Billion RMB) |
Rank |
YoY Change |
|
|
2019 |
201.8 |
24 |
29.0% |
|
2020 |
289.2 |
19 |
43.3% |
|
2021 |
350.9 |
13 |
21.3% |
|
1H2022 |
112.8 |
10 |
-34.3% |
|
Sources: Company Reports and CRIC, iFAST Compilations Data as of 30 June 2022 |
|||
On the other hand, while other non-SOE developers spend wisely and save diligently, Greentown does the opposite by largely expanding the land spending. From Table 2, Greentown's land spending amounted tremendously to RMB 31.9 billion, ranking 5th among the industry. As of June 2022, the total land bank Greentown owns stood at 560 million square meters, enough to fulfil the land requirement in the coming five years.
In the second half of this year, the saleable resources of Greentown are around RMB 380 billion, of which 80% of projects situates in tier-one and tier-two cities. Although the property crisis has yet to fade, it's undeniable that there is an "SOE belief" in the property market, with buyers often giving priority to SOE-backed developers, so we believe that the company can still outperform the market average in the second half of the year, but whether it could reverse the downtrend momentum eventually hinges on the degree of market's rebound.
Table 2: Land Spending in 1H2022
|
Land spending (Billion RMB) |
Rank |
|
|
Binjiang Group |
39.2 |
1 |
|
CR Land |
39.2 |
2 |
|
China Overseas |
35.5 |
3 |
|
C&D Property |
34.9 |
4 |
|
Greentown |
31.9 |
5 |
|
Poly Real Estate |
24.5 |
6 |
|
Merchants Shekou |
23.5 |
7 |
|
Railway Construction Corporation |
21.6 |
8 |
|
Vanke |
19.1 |
9 |
|
Guangzhou Metro Group |
16.5 |
10 |
|
Sources: China Index Academy, iFAST Compilations Data as of 30 June 2022 |
||
Asset-light Mode Is Favored by Peers
Looking into project management business, as mentioned in our previous article ”Idea of the Week: Backed by a Central Government-owned Enterprise, Is Greentown Worth Investing?", the property industry is facing more intense competition and stricter regulation policy, leaving more challenges for small-sized developers' survival as a result. There might be a greater driving force for small-sized developers to seek to use project management services. As of June 2022, the number of projects under management reached 390, increasing by 45 as compared to the beginning of this year. The attributable net profit from the project management segment surged by 33% to RMB 360 million.
One thing to note is that due to the light-asset nature of the project management business, it will not occupy much of the company's cash balance and bring developers higher profitability. Consequently, under the current market situation, this segment is definitely a cake that every developer would die to have a slice, as bigger ones such as CIFI, Zhongliang, and Agile have announced their foray into the business over the past two years. We believe that Greentown has been dedicated to this business for many years, with a market share of over 20%, suggesting its leading place in the industry will be hard to tamper in the near future, and we are optimistic that the company will continue to maintain a fast growth rate in the future even if the industry becomes more competitive.
Credit Indicators Remains Sound, Liquidity Tops Among Developers
As of June 2022, the total borrowing rose by 9.7% to RMB 139.9 billion, including bank loans of RMB 92.4 billion, which comprises 66% of total debt. The relatively low-interest rate of bank loans drove down the average borrowing cost to 4.5%, one of the lowest levels in the industry, and the debt structure is rather desirable.
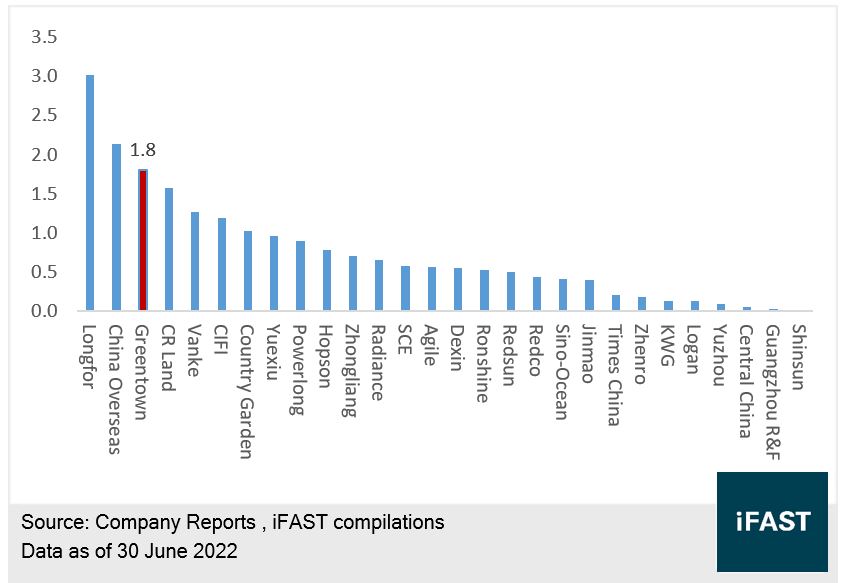
The short-term debt of Greentown amounted to RMB 25.3 billion, and RMB 58.2 billion in cash and cash equivalents were recognised on the balance sheet. Yet the available-for-use cash balance narrowed to RMB 45.1 billion after deducting restricted cash (Including the pre-sale proceed part) of RMB 13.2 billion, translating into a 1.8x cash to short-term debt ratio. Chart 1 depicts that only a few developers like Longfor and China overseas have higher adjusted cash to short-term debt ratios, reflecting that the current liquidity of Greentown tops among developers.
Chart 1: Adjusted Cash to Short-term Debt
From the view of credit indicators, as of June 2022, the net gearing ratio of Greentown climbed by 20 percentage points to 71.5% from the beginning of this year. Adjusted liability to asset ratio slightly gained 2 percentage points to 73.5%. As a whole, Greentown's leverage is trending up, but is still below the industry average.
As for off-balance-sheet credit indicators, as of June 2022, minority interest over the total equity ratio grew to 62.9%, and payable to joint ventures over total debt also jumped to 38.6%. Both indicators have high numbers, showing increasing collaborative projects and the likelihood of potential off-balance-sheet debt. This is due to a large number of jointly developed projects since a portion of projects is not consolidated into Greentown's financial statement, which suggests the company may have off-balance-sheet debts. However, we noted that the equity ratio of the newly purchased land bank (attributable land bank to total land bank) spiked to 75.8%, about an 8 percentage-point increase from one year ago. The rising ratio suggests that Greentown is tuning its business model, from cooperation-oriented to self-development to evite the uncertainly from partners amid a developer default crisis. As a result, we believe off-balance-sheet credit indicators are expected to improve in the future.
Table 3: Credit Indicators of Greentown
|
End-2021 |
Mid-2022 |
|
|
Net Gearing Ratio |
52.0% |
71.5% |
|
Adjusted Liability to Asset Ratio |
71.1% |
73.5% |
|
Average Borrowing Cost |
4.6% |
4.5% |
|
Minority Interest/Total Interest |
57.8% |
62.9% |
|
Payable to Joint Ventures over Total Debt |
30.3% |
38.6% |
|
Sources: Company Reports, iFAST Compilations Data as of 30 June 2022 |
||
Fundraising Keeps Smooth in Both Onshore and Offshore Market, Overall Credit Risk is Insignificant
Owing to the surging of defaulted developers, whether in the onshore or offshore capital market, just a few developers with outstanding solvency have had access to bond issues from the beginning of this year. Greentown is one of them, and issued company bonds, MTNs, asset-backed securities as well from the onshore market, with an aggregated amount of RMB 17.6 billion and an average borrowing rate of roughly 3%, which is close to that of central government-owned issuers, such as China Resources Land and China Overseas.
In the offshore market, Greentown issued a green bond with a principal of USD 400 million in January. China Zheshang Bank provides the bond with Standby Letter of Credit (SBLC), one of the credit enchantment measures, making the coupon rate at the lowest level of 2.3%. Besides, Greentown retaped the bond due in July 2025 to raise another fund of USD 150 million.
In combination, we think Greentown's fundraising keeps smooth on both the onshore and offshore market, and its borrowing cost is significantly lower than high-yield peers, reflecting an "SOE belief" in the capital market as well, particularly for the onshore market. We also expected Greentown's cash flow to remain stable with the backing of strong fundraising capability, and overall risk to be relatively insignificant.
Table 4: Year-to-date Bond Issue of Greentown
|
Onshore |
||
|
Amount (Billion RMB) |
Borrowing Rate |
|
|
Company Bonds |
1.0 |
3.3% |
|
Medium Term Note |
9.6 |
3.6% |
|
Supply Chain ABS |
6.0 |
2.9% |
|
Balance payment ABS |
1.0 |
3.5% |
|
Offshore |
||
|
Amount (Million USD) |
Borrowing Rate |
|
|
Green Bond (Jan) |
400 |
2.3% |
|
Retap of USD Bond |
150 |
4.7% |
|
Sources: Company Reports and Bloomberg, iFAST Compilations Data as of 30 June 2022 |
||
Bonds Yield 14% return, Are Attractive for Investment
Investment-wise, offshore bond issue size looks moderate, with two of them are available for trading on our platform. The relevant information is shown below:
Table 5: Bonds Issued by Greentown
|
Bonds |
Credit Rating |
Years to Maturity |
Ask Price |
YTM |
|
GRNCH 4.700% 29Apr2025 Corp (USD) |
BB-(S&P) |
2.6 |
80.6 |
14.3% |
|
GRNCH 5.650% 13Jul2025 Corp (USD) |
BB-(S&P) |
2.8 |
80.4 |
14.8% |
|
Sources: Bondsupermart Data as of 6 October 2022 |
||||
Two USD bonds are currently trading at around $80, with an investment horizon of 2.5 years. Both are yielding similar yields to maturity at roughly 14%. Considering that bonds issued by other SOE developers usually proffer 6% or below return, we thus believe bonds of Greentown exhibit somewhat investment attractiveness. It is important to highlight that China Communication Construction Group provides a Keepwell deed for a bond due in Jul 2025, leaving the bond with higher assurance. Investors could prioritise to consider it.
Corporate Risk
Investors should be mindful that Greentown is becoming more aggressive on land purchasing, although the current liquidity looks loose, it might weaken if the company retains aggressive going forward.
Furthermore, in addition to traditional residential property development, Greentown also engages in industrial property, which takes more capital input and time to develop. It suggests that these business sectors might result in a negative effect on Greentown's liquidity.
Conclusion
1H2022's contracted sales declined by 34%, but still outperformed the market average, and the industry ranking moved up to the top 10. Greentown's land spending in 1H2022 keeps large, leaving it potential for further development. Greentown’s solvency profile remained roughly unchanged, particularly, the liquidity topped among its homebuilder peers. The overall credit risk is manageable. The bond due in 2025 is yielding approximately 14%, rather attractive for consideration.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!