


Highlights:
- H&H International’s operating performance is good. There is a gradual shift from reliance on milk powder sales to diversified multi-brand product sales. The company’s business model is more stable with more diversification of business risks.
- H&H International’s cash flows are strong. The cash flows could boost the company’s liquidity, provide a foundation for debt repayment and be helpful in negotiation of getting refinancing from banks or creditors.
- H&H International’s credit profile is decent. The 2024 bond has a yield to maturity of 8.1%. The overall default risk is under control. As for the 2026 bond, the credit risk is relatively higher, but the yield to maturity is also up to 14.9%, which offers a good risk-to-return ratio and is only suitable for investors with a high risk tolerance.
H&H International mainly engages in the manufacture and sales of infant milk powder, care products and nutritional products. The company is listed on HKEX (Stock Code: 1112.HK), with a market capitalisation of around HKD 7.01 billion.
With Good Operating Performance, Strong Cash Flows Provide a Foundation of Debt Repayment
As shown in Chart 1, in the first half of 2023, H&H International’s revenues were RMB 6.98 billion, increased by 16.3% YoY (excluding the FX impact). The gross margin was 61.1%. The cost control measures are effective, and it has a certain degree of growth. The operating performance is good.
Chart 1: H&H International’s Revenues and Gross Margin

It is worth noting that as shown in Table 1, the revenues from infant and young child products (including infant formulas and other baby nutrition and care products) were RMB 3.11 billion. These revenues accounted for 45% of total revenues, down from the previous high of 50% or more. This was because of the infant formula market being saturated and the low birth rate in China. These led to a slight decline in the revenues from infant milk powders. Along with strong sales growth in other segments (adult nutrition & care products and pet nutrition & care products). This means a gradual shift from reliance on milk powder sales to diversified multi-brand product sales. The company’s business model is more stable with a more diversification of business risks.
Table 1: H&H International’s Segment Revenues and Main Brands
|
|
2023 1H Revenues (RMB billion) |
YoY Growth (%) |
% As of Total Revenues |
Main Brands |
|
Infant formulas |
2.21 |
-10% |
32% |
Biostime |
|
Others baby nutrition and care products |
0.90 |
+25% |
13% |
Good Goût Dodie |
|
Adult nutrition and care products |
2.94 |
+44% |
42% |
Swisse |
|
Pet nutrition and care products |
0.93 |
+28% |
13% |
Solid Gold Zesty Paws |
|
Total |
6.98 |
+16% |
N/A |
|
|
Sources: Company’s Reports, iFAST Compilations Data as at 30 June 2023 |
||||
H&H International’s cash flow was still strong. As shown in Chart 2, the company generated an adjusted free cash flow of up to RMB 1.2 billion or above each year. The cash flow could boost the company’s liquidity, provide a foundation for debt repayment and be helpful in negotiation of getting refinancing from banks or creditors.
Chart 2: H&H International’s Net Profit to Shareholders and Adjusted Free Cash Flow
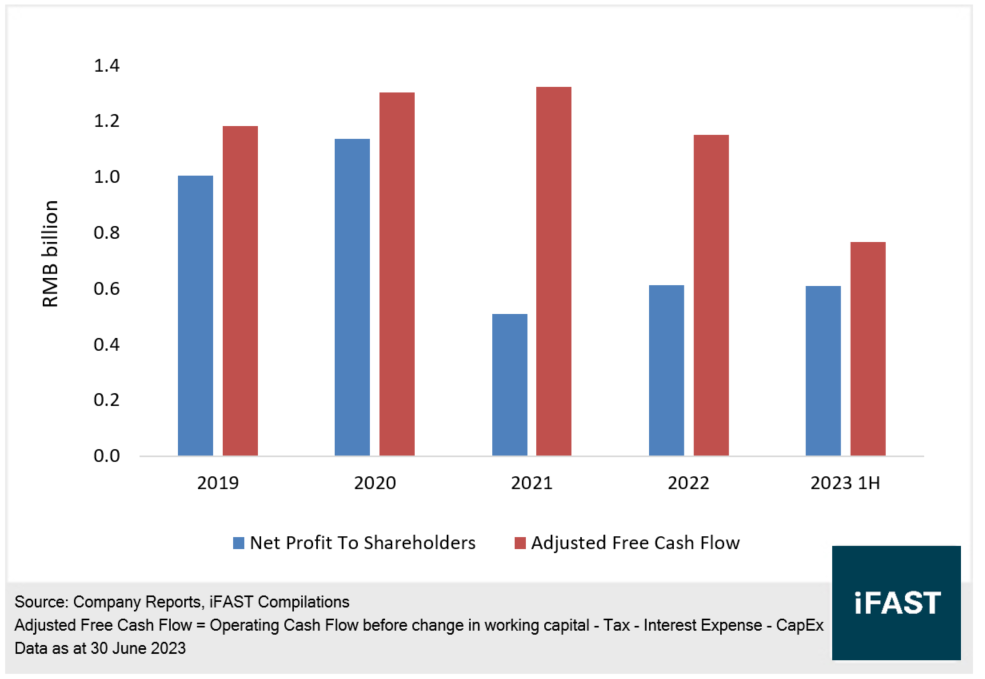
Meanwhile, we expect H&H International’s adjusted cash flow for the year is expected to reach RMB 1.4 billion to RMB 1.6 billion, with YoY growth projected to reach 20% or more. The drivers include the strong growth in both segments (adult nutrition & care products and pet nutrition & care products), the cost optimization of those matured businesses (infant, young child and adult related businesses) and the time for spending money in the pet nutrition and care product segment probably being over. These factors could drive the cash flow performance.
Decent Credit Profile; 2024 Bond’s Default Risk is Under Control
Regarding the credit profile, as shown in Table 2, as of the end of June 2023, H&H International’s total debt increased slightly to RMB 10.09 billion. However, its leverage level improved slightly instead. For example, the company's net debt / EBITDA and net debt/ adjusted free cash flow fell to 4.0 times and 5.8 times respectively. Its interest coverage ratio also improved to 3.4 times. The overall credit profile is decent.
Table 2: H&H International’s Credit Indicators
|
Dec 20 |
Dec 21 |
Dec 22 |
Jun 23 |
|
|
Total Debt (RMB billion) |
6.17 |
9.48 |
9.57 |
10.09 |
|
Total Cash (RMB billion) |
1.83 |
2.40 |
2.31 |
2.16 |
|
Average Cost of Borrowings (%) |
4.7% |
3.7% |
5.5% |
7.3% |
|
Cash to Short-term Debt (times) |
29.0x |
0.8x |
2.4x |
1.5x |
|
Net Debt / EBITDA (times) |
2.1x |
4.5x |
4.2x |
4.0x |
|
Net Debt / Adjusted Free Cash Flow (times) |
3.3x |
5.4x |
6.3x |
5.8x |
|
Interest Coverage Ratio (times) |
7.3x |
5.4x |
3.0x |
3.4x |
|
Sources: Company’s Reports, iFAST Compilations Data as at 30 June 2023 |
||||
As the 2026 bond yield of H&H International is as high as 15%, the company does not have too much room to refinance the bonds for repayment. Therefore, we have to pay attention to the debt maturity profile and consider the factors such as other financing channels other than bond issuance, cash level and future cash flows to determine whether the company can repay the existing bonds.
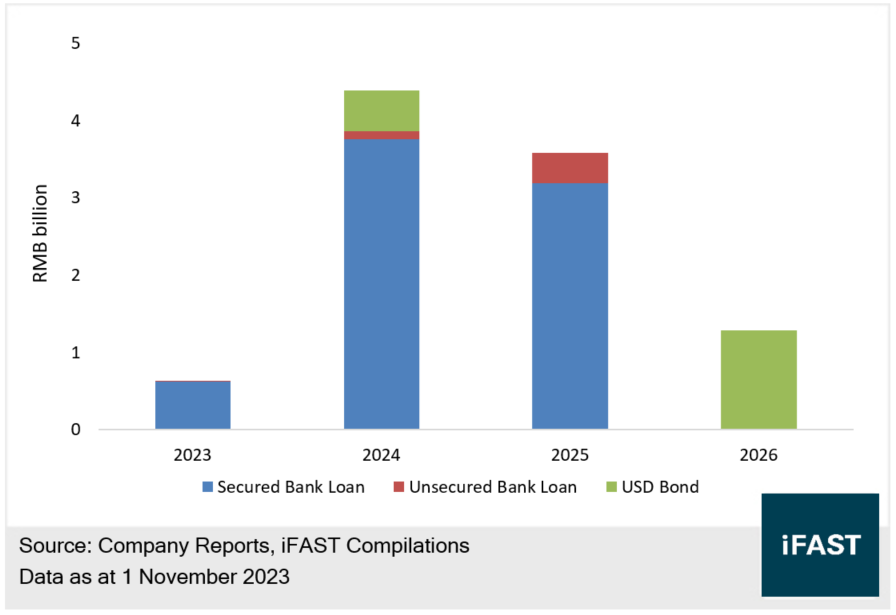
Referring to Chart 3, H&H International’s debt mainly consists of secured bank loans, accounting for 77% of its total debts. Since these loans are secured loans, and coupled with the company's good current operating performance, cash flows and asset quality, we believe that it is not difficult to refinance these secured loans. The actual repayment pressure is not significant.
Chart 3: H&H International’s Debt Maturity Profile
As for USD bonds, the credit risk of H&H International’s 2024 bond, "BTSDF 5.625% 24OCT2024 CORP (USD)", is significantly lower than that of the 2026 bond.
As shown in Table 3, the outstanding amount of the 2024 USD bond is USD 74.55 million. H&H International can take advantage of its cash on hand of around RMB 2.16 billion and free cash flow of about RMB 1.2 billion to RMB 1.6 billion per year to repay the bond. The 2024 bond has a net yield to maturity of 7.8%. The overall default risk is under control. It is suitable for investors with moderate risk tolerance.
The credit risk of the 2026 bond "BTSDF 13.500% 26Jun2026 Corp (USD)" is relatively higher, with a larger outstanding amount of USD 180 million. To adequately repay the bond, H&H International has to (1) successfully refinance a number of secured loans maturing between 2023 and 2025, (2) have no significant deterioration in its operating conditions during this period and (3) accumulate cash flows over a number of years. Thus, the bond is only suitable for investors with a high-risk tolerance. The yield to maturity is high at 14.6%, which offers a good risk-to-return ratio.
Table 3: H&H International’s Bonds
|
Bond Name |
Issuer Credit Rating (S&P) |
Years To Maturity |
Ask Price (Investors Buy) |
Net YTM |
Outstanding Amount |
| BTSDF 5.625% 24OCT2024 CORP (USD) | BB+ |
0.9 |
97.8 |
8.1% |
USD 74.55 million (equivalent to RMB 530 million) |
|
BB+ |
2.5 |
98.0 |
14.9% |
USD 180 million (equivalent to RMB 1.28 billion) |
|
|
Source: Bondsupermart Data as of 5 December 2023 |
|||||
Related Risk
Currently, H&H International relies on bank loans for refinancing. If it fails to refinance, this will pose a higher short-term liquidity pressure.
Mainland China’s recent birth rate has dropped to a record low, and the government policy on promoting birth might not be effective. If the trend persists, it might hurt the demand for Mainland China’s milk powder market, thus affecting the company’s business and cash flow performance.
H&H International’s working capital management is not quite decent. Sometimes, the company would have a large increase in inventory and accounts receivables. In general, this does not have a significant impact on operations. However, if the situation persists, it will put pressure on its capital chain and cash flow.
In addition, the company's payables are on a downward trend, which might mean that the company does not have a controlling power over its raw material suppliers. This might affect the company's liquidity performance.
Conclusion
H&H International’s operating performance is good. There is a gradual shift from reliance on milk powders sales to diversified multi-brand product sales. The company’s business model is more stable with a more diversification of business risks.
H&H International’s cash flows are strong. The cash flows could boost the company’s liquidity, provide a foundation for debt repayment and be helpful in negotiation of getting refinancing from banks or creditors.
H&H International’s credit profile is decent. The 2024 bond has a yield to maturity
of 8.1%. The overall default risk is under control. As for the 2026 bond, the
credit risk is relatively higher, but the yield to maturity is also up to
14.9%, which offers a good risk-to-return ratio and is only suitable for
investors with a high-risk tolerance.
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!











