


Highlights:
- CK Hutchison is a typical global conglomerate with main businesses in ports, retail, infrastructure, telecommunication and energy. The Group’s earnings structure is quite diversified, with gradual recovery in several businesses.
- The Group’s credit status is solid, with a low leverage level and a strong financing ability.
- Investors could consider the 2028 Bond, with a yield to maturity of 4.5%.
CK Hutchison is a global conglomerate with main businesses in ports, retail, infrastructure, telecommunication and energy. The Group was formed through the restructuring, merger and spin-off of Cheung Kong Holdings and Hutchison Whampoa Limited. The Group’s founder and major shareholder is Mr. Li Ka Shing. Mr. Li Ka Shing Family holds around 30% of the Group’s shares.
The Group is listed on HKEX (Stock Code: 1.HK), with a current market capitalisation of around HKD 207.4 billion.
Quite Diversified Earnings Structure with Gradual Recovery in Several Businesses
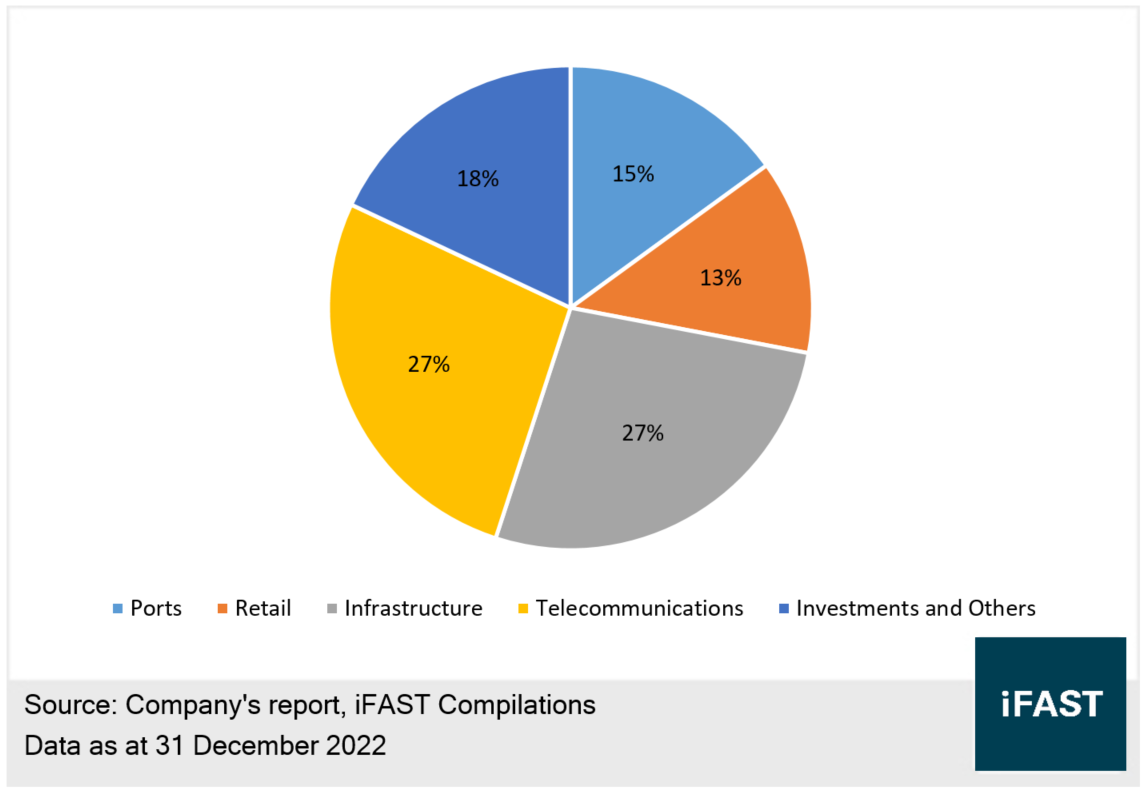
As shown in Chart 1, CK Hutchison’s EBITDA was HKD 119.0 billion in 2022, increasing by 7.0% YoY. The Group’s operating free cash flow slightly declined by 6.4% YoY to HKD 33.0 billion. The overall performance is fair. The Group’s earnings structure is quite diversified (Chart 2), with each of the five businesses accounting for 13% to 27% of EBITDA. It is a typical conglomerate.
Chart 1: CK Hutchison’s EBITDA and Operating Free Cash Flow over Past Few Years
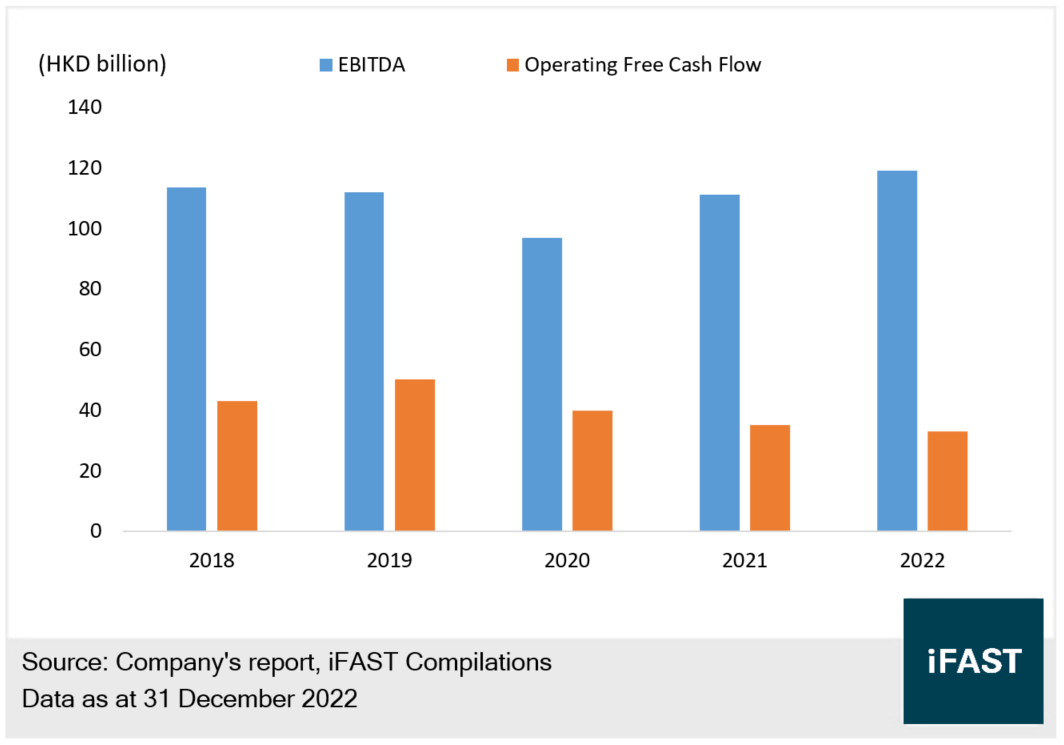
Chart 2: CK Hutchison’s EBITDA Breakdown (by Segment)
For the port business, the Group operates 293 operating berths and terminals in 51 ports amongst 25 countries. In 2022, despite a slight decline in throughput, given an increase in warehousing revenues, we saw a low single-digit revenue and profit growth in 2022 (see Table 1).
With the supply chain issues easing and the port congestion nearing resolution, the port throughput is expected to increase, which could boost revenue from this segment. We believe that the port business will gradually recover.
The retail division consists of the A.S. Watson group of companies. A.S. Watson Group owns and operates 12 retail brands with 16,000 stores, providing health and beauty products, food and beverages, consumer electronics and electrical appliances.
Although consumer spending in regions such as Europe and Asia (excluding China) continued to recover, the strengthening of USD/HKD against other currencies, coupled with the city closure measures in China for most of 2022, resulting in a decline in both revenue and profit for the retail business (see Table 1). The performance of the entire retail business is expected to be boosted by the return to normal in China.
Table 1: CK Hutchison’s Segment Revenues and EBITDA in 2022
|
|
Total Revenue |
YoY Change |
EBITDA |
YoY Change |
|
Ports |
HKD 44.1 billion |
+4% |
HKD 15.8 billion |
+4% |
|
Retails |
HKD 169.6 billion |
-2% |
HKD 14.3 billion |
-11% |
|
Infrastructure |
HKD 54.4 billion |
-3% |
HKD 18.8 billion |
-3% |
|
Telecommunications |
HKD 77.9 billion |
-10% |
HKD 23.8 billion |
-20% |
|
Investment and Others (Including Energy) |
HKD 94.1 billion |
+31% |
HKD 18.5 billion |
+81% (Excluding one-off items) |
|
Source: Company’s Reports, iFAST Compilations Data as at 31 December 2022 |
||||
The Group's infrastructure investments are mainly made through its 76% stake in the subsidiary, CK Infrastructure (Stock Code: 1038.HK), which has infrastructure developments around the world, including Hong Kong, Mainland China, the United Kingdom, Europe, Canada and Australia. In 2022, the appreciation of USD/HKD against other currencies also dragged down the overall revenues of the infrastructure business to HKD 54.4 billion (Table 1). Excluding the impact of foreign exchange movements, its revenue and EBITDA both recorded low single-digit growth. The overall performance was stable.
For the telecommunications business, the Group sold its transmission tower assets in Austria, Denmark, Ireland, Italy, Sweden and the UK for up to EUR10 billion (around HKD 85-92 billion) between 2020 and 2022. The Group intends to sell 60% of Wind Tre, the Italian telecoms network infrastructure, for an initial consideration of EUR3 billion (approximately HKD 26 billion). This series of major asset disposals would gradually lead to a decline in both revenue and earnings for its telecommunications business segment. However, these transactions generated up to HKD 45 billion in realised gains (booked accordingly in different periods), reflecting that the market value of the Group's telecommunication assets might be significantly higher than their book value.
In investments and other businesses, the largest contributor is the energy segment (accounting for 74% of EBITDA in this segment). The Group has around 17% stake in Cenovus Energy (stock code: CVE.CA). This segment's revenue and earnings are driven by a sharp rise in energy prices over the 2022 period due to the continued tight oil and natural gas supply (for oil outlook, please refer to “Idea of the Week: Unravelling the Investment Logics of Oil Bonds”). We expect the WTI oil price to remain higher for much longer. Oil Producers, including Cenovus Energy, would thus benefit. While its revenues and earnings might fall off somewhat due to the high base effect, this still contributes a lot to the Group's revenues and earnings.
Solid Credit Status with Low Leverage Level
As of the end of 2022, CK Hutchison’s net gearing ratio was only 35.1%, down 780 basis points from the end of 2021. The net debt / EBITDA and net debt / operating free cash flow were 1.8 times and 6.6 times respectively. The leverage level is low.
In addition, the Group's current ratio and cash short term debt ratio reached 1.3 times and 1.7 times respectively, reflecting the Group's strong financing ability. Overall, the Group's credit status is solid.
Table 2: CK Hutchison’s Main Credit Indicators
| Dec-21 | Dec-22 | |
| Net Debt (Including Perpetual Debts) (HKD billion) | 270.9 | 219.4 |
| Net Debt / EBITDA (times) | 4.7x | 4.1x |
| Net Debt / Operating Free Cash Flow (times) | 7.7x | 6.6x |
| Net Gearing Ratio (%) | 42.9% | 35.1% |
| Current Ratio (times) | 1.3x | 1.3x |
| Cash to Short-term Debt (times) | 1.9x | 1.7x |
| Interest Coverage Ratio (times) | 5.3x | 5.6x |
| Average Cost of Borrowings (%) | 1.6% | 2.0% |
| Source: Company’s Reports, iFAST
Compilations Data as at 31 December 2022 |
||
Investors could Consider 2028 Bond with Yield to Maturity of 4.5%
CK Hutchison’s credit rating is A / A- (S&P / Fitch). The bond has the same rating and belongs to the high investment grade level.
Given its strong profits and cash flows and excellent credit status, we believe that overall the Group’s bond default risk is low. Bonds with different tenors could be considered (Table 3). Amongst these, investors could consider the 2028 bond, with a yield to maturity of 4.5%, which has certain attractiveness.
Table 3: CK Hutchison’s Bonds with Different Tenors
| Bond Name | Years To Maturity | Ask Price (Investors Buys) |
Yield To Maturity |
| CKHH 4.750% 21Apr2028 Corp (USD) | 5.0 | 101.7 | 4.5% |
| CKHH 2.500% 08May2030 Corp (USD) |
7.0 | 88.5 | 4.5% |
| CKHH 4.875% 21Apr2033 Corp (USD) |
10.0 | 101.8 | 4.8% |
| CKHH 3.375% 08May2050 Corp (USD) | 27.0 | 77.1 | 5.0% |
| Source: Bondsupermart Data as of 5 May 2023 |
|||
Related Risks
The increasing global recession risk could have a greater impact on the Group’s ports, consumer and energy businesses. In addition, the Group's retail segments are mostly located in Europe, which is more likely to be the first to enter recession due to high inflation and aggressive interest rate hikes. This might drag down the Group's overall performance.
The Group holds a number of joint ventures and associates. Many of them are partners with other companies under the “Cheung Kong” Group and Mr. Li Ka Shing family. On one hand, this artificially lowers the liability level at the holding company level, which may cause the actual leverage to be higher than the book value. On the other hand, if Mr. Li Ka Shing’s family encounters any issue in their personal finance, it might have a greater impact on the Group's operations.
Conclusion
CK Hutchison is a typical global conglomerate with main businesses in ports, retails, infrastructure, telecommunication and energy. The Group’s earnings structure is quite diversified, with gradual recovery in several businesses.
The Group’s credit status is solid, with a low leverage level and strong financing ability.
Investors could consider the 2028 Bond with a yield to maturity of 4.5%.


