


It has been two years since the launch of the KITSP 4.750% Perpetual Corp (SGD) and Keppel Infrastructure Trust (“KIT”) is returning to the bond market with a proposed SGD NC10 perpetual note offering. We think that the notes are fairly priced at an initial price guidance (“IPG”) of 4.55%.
About the perpetual notes
Keppel Infrastructure Fund Management Pte Ltd, the trustee-manager of KIT is the issuer of the perpetual securities. The new notes are subordinated and rank only senior to the ordinary units of the trust.
According to the company, the notes are first callable in June 2031. If the issuer does not call back the notes on the first call date, the distribution rate will reset to the 10-year SGD Swap Offer Rate or relevant successor rate + initial spread + step-up margin of 100 basis points (“bps”).
The issuer also has the right to redeem the perps for (1) taxation, (2) accounting or (3) tax deductibility reasons. In other circumstances, the perps may be called (4) if the outstanding amount falls below 10 percent of the aggregate principal originally issued, or (5) if KIT units are suspended or have stopped trading on the Singapore Exchange.
The new notes have a dividend stopper clause and any deferred distribution are cumulative and compounding. Proceeds from this offering will be used for refinancing of existing debt obligations, general working capital purposes including expenditures, or the financing of acquisitions of investments and asset enhancement works. As of 12pm today, order books for this offering have exceeded SGD 300m.
About Keppel Infrastructure Trust
KIT is Singapore’s largest diversified business trust with SGD 5.1 billion of assets under management as of 31 Mar 2021. Most of the assets in the portfolio provide essential services to large institutions including government agencies, industrial conglomerates and commercial enterprises. Table 1 provides an overview of the assets in the portfolio.
Table 1: Overview of KIT's portfolio
| Businesses | Description | Customer and Contract Terms | Primary Source of Cash Flows |
| City Gas (Singapore) | Sole producer and retailer of town gas | Approximately 870,000 residential, commercial and industrial customers | Fixed margin per unit of gas sold, with fuel and electricity costs passed through to consumer |
| Ixom (Australia & New Zealand) | Supplier and distributor of key water treatment, industrial and specialty chemicals in Australia and New Zealand | Over 4,500 customers comprising municipals and blue-chip companies | Payments from customers for delivery of products and provision of services based on agreed terms |
| Philippine Coastal (Philippines) | The largest petroleum products import storage facility in the Philippines, located in the Subic Bay Freeport Zone | Blue-chip customers | USD-denominated “take or-pay” contracts with no direct exposure to petroleum price and volume risk |
| Basslink (Australia) | Basslink subsea interconnector that transmits electricity and telecoms between Victoria and Tasmania in Australia | Service agreement with Hydro Tasmania (owned by Tasmania state government) until 2031, with option for 15-year extension | Fixed payments for availability of Basslink subsea cable for power transmission |
| KMC (Singapore) | 1,300MW combined cycle gas turbine power plant | Capacity Tolling Agreement with Keppel Electric until 2030 with option for 10-year extension (land lease till 2035, with 30-year extension) | Fixed payments for meeting availability targets |
| Senoko WTE Plant (Singapore) | Waste-to-energy plant with 2,310 tonnes/day waste incineration concession | NEA, Singapore government agency – concession until 2024 | Fixed payments for availability of incineration capacity |
| Keppel Seghers Tuas WTE Plant (Singapore) | Waste-to-energy plant with 800 tonnes/day waste incineration concession | NEA, Singapore government agency – concession until 2034 | Fixed payments for availability of incineration capacity |
| Keppel Seghers Ulu Pandan NEWater Plant (Singapore) | One of Singapore's largest NEWater plants, capable of producing 148,000m3/day | PUB, Singapore government agency – concession until 2027 | Fixed payments for the provision of NEWater production capacity |
| SingSpring Plant (Singapore) | Singapore's first large-scale seawater desalination plant, capable of producing 136,380m3/day of portable water | PUB, Singapore government agency – concession until 2025 (land lease till 2033) | Fixed payments for availability of output capacity |
| Source: Company, As of 20 Apr 2021 | |||
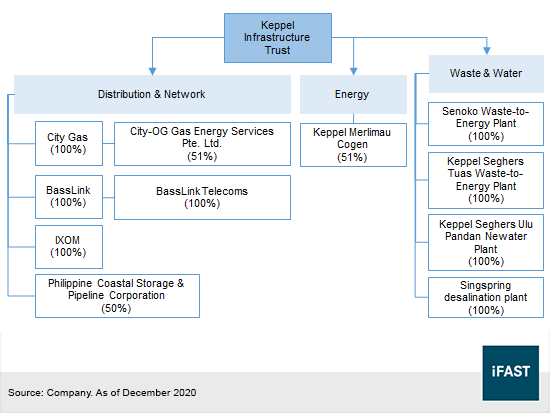
Trust revenue is recognized through the nine core assets in Table 1 that may be categorized according to three operating segments (Figure 1). As of December 2020, the three operating segments - Distribution & Network, Energy, Waste & Water account for accounted for 54.8%, 15.7% and 8.8% of total assets respectively. For more information on the trust structure and performance, kindly refer to our earlier article “Keppel Infrastructure Trust: Investors to reap returns from an upbeat sectoral outlook”
Figure 1: Main operating segments of Keppel Infrastructure Trust and underlying assets
Credit and liquidity profile
Following its last operational update in 1Q21 for the quarter ended 31 Mar 2021, KIT registered a slight 0.2% decline in group EBITDA from SGD 98.1m in to SGD 97.9m. Nonetheless, operational cash flow increased 15.6% from SGD 57.5m in 1Q20 to SGD 66.5m in 1Q21.
The trust remains positive cash flow generative as it recorded net cash from operating activities of SGD 345.43m in 2020 and SGD 356.40m in 2019.
Cash flows are likely to remain resilient moving forward and the trust had a decent interest coverage ratio last year. We think that the EBITDA to interest (including distributions to perpetual securities holders) multiple of 1.8x in 2020 is adequate.
KIT recorded a cash position of SGD 580.7m at the end of 2020. While the cash amount may not be sufficient to cover its SGD 643.9m of current borrowings, the trust indicated that it will refinance the AUD 640.9m Basslink loan due or callable in August 2021. Other loans, inclusive of the SGD 100m maturing in 2022, SGD 178m loan maturing in 2024 and AUD 532.4m fixed rate loan maturing in February 2024 would also be refinanced upon maturity.
Referring back to its latest operational update in March, KIT revealed that its cash level had dropped to SGD 497.0m at 1Q21 while total borrowings increased by SGD 237m. The trust obtained an SGD 300 short term facility to finance the Philippine Coastal acquisition, resulting in a higher net debt position of SGD 1,901m. Net gearing (defined as net debt over total assets) increased to 37.3% in 1Q21 (2020: 32.1%) while net debt / EBITDA expanded to 4.8x from 4.2x in 2020.
Pricing comments
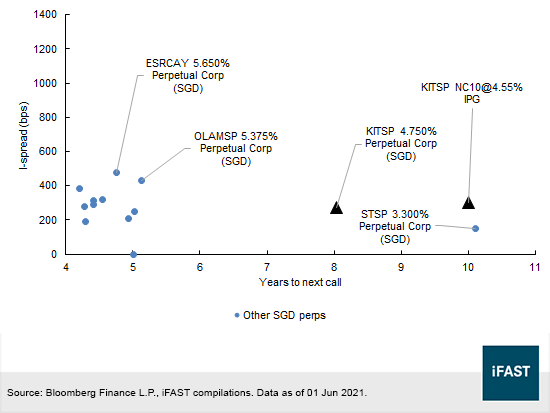
We feel that the new issue from Keppel Infrastructure Trust is fairly priced at an initial price guidance of 4.55%. With an I-spread, or credit spread of 299 basis points (“bps”) above the 10-year SGD Swap Offer Rate (“SOR”), the 4.55% IPG is close to KITSP 4.750% Perpetual Corp (SGD) which has an I-spread of 273bps (Figure 2). From this perspective, we are indifferent between the KITSP 4.75% perps and the new NC10 issue.
Figure 2: Relative valuation using credit spreads
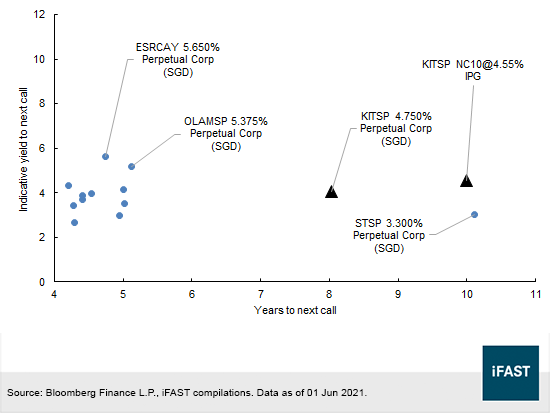
Within the context of their yields (“YTC”), the initial price guidance of 4.55% is nearly 50bps above the yield-to-call of the KITSP 4.75% perps, and 154bps above the STSP 3.300% Perpetual Corp (SGD) (Figure 3).
We do not feel that a sub-50 basis point difference would compensate well enough for a 2-year tenor difference between the two KITSP notes but we would prefer the new 4.55% IPG issue over the STSP 3.3% perps as it offers a higher return. Investors may refer to “Singtel to issue NC10.5 SGD perpetual notes at 3.6% IPG” for more details on the STSP 3.3% notes.
On the other hand, investors who prefer perpetual securities with a shorter call date and higher yield may consider the ESRCAY 5.650% Perpetual Corp (SGD) – see “ESR Cayman proposes further issue of SGD 5.65% perps ” and OLAMSP 5.375% Perpetual Corp (SGD) – “Olam International to issue SGD NC5.5 perpetual at 5.5% IPG”. The ESRCAY 5.65% perps and OLAMSP 5.375% perps have respective yields-to-call of 5.63% and 5.20% as at 1 Jun 2021.
Figure 3: Relative valuation using Yield-To-Call
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) has a principal position in OLAMSP 5.375% Perpetual Corp (SGD), ESRCAY 5.650% Perpetual Corp (SGD) and STSP 3.300% Perpetual Corp (SGD). The analyst who produced this report is a unitholder of Keppel Infrastructure Trust.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!


