


What’s happening?
LBS Bina Group Berhad is looking to raise a fresh perpetual bond of up to RM 250 million in the first round, with the total programme size possibly reaching thought to be at a total RM 700 million. Having spoken with the bookrunners and representatives of the LBS Bina Group, we understand a portion of the money is earmarked to pare down previous debts to free up the encumbrance of some assets deemed valuable by LBS Bina.
We met with representatives of LBS Bina Group as well as the bookrunners in a private investor session where we were guided that a new perpetual issue is on the cards.
Strategy: affordable housing
LBS Bina is primarily a real estate developer with over 83% of the company’s revenue coming from the property development segment in 2018. What separates LBS Bina from other real estate developers is the focus of the company’s development portfolio, in this case affordable housing.
According to LBS Bina’s representatives, about 50% of the group’s developments are landed properties, with the rest of the products being high-rise buildings. This is a unique proposition given the propensity of local real estate developers to develop high-rise properties. We understand from management that 95% of the landed properties developed by LBS Bina are priced below RM 600,000.
Strong sales, but balance sheet is highly geared
LBS Bina has managed to surpass its internal target of RM 1.5 billion in property sales in 2019, registering RM 1.63 billion in sales last year. In addition to this, the company’s unbilled sales (sales locked in but yet to be reflected on the income statement) stood at RM 2.243 billion as at 31 December 2019, providing a visibility of earnings for approximately 1.5 years.
Nonetheless, LBS Bina’s balance sheet does appear slightly more aggressive compared to its real estate developer peers in Malaysia. To provide some context, the firm’s current debt-to-equity ratio is at 87.64%, as compared to the median debt over equity gearing load of 35.86% of listed developers as of the third calendar quarter of 2019. Figure 1 provides a quick look of where the company stands against its real estate peers that have issued perpetuals last year as well as the industry average.
Figure 1: Listed real estate developers' adjusted debt over equity as of 3Q19
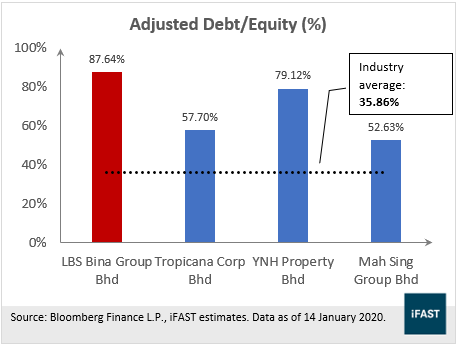
Our estimates in Figure 1 treated perpetual securities as debt and removed the equity credit usually afforded to companies issuing perpetuals to arrive at the adjusted debt-to-equity ratio.
Key bond terms
As mentioned earlier, LBS Bina is expected to raise RM 250 million in the first round of issuance. The bond is expected to be a perpetual bond non-callable for five years, with a step-up provision expected to add an additional 1% of interest (to the initial distribution rate) starting from the first call date, as well as every anniversary thereafter.
We also understand from the meeting with management and bookrunners that the bond would be unrated and secured with a minimum-security cover of 1.43 times. The security package is expected to comprise of either LBS Bina’s existing properties or land bank.
Bond pricing
The book-building for LBS Bina’s new perpetual bond is expected to commence somewhere between early- to mid-February 2020. Given that timeline, there is no indicative pricing at the current moment.
That being said, based on our conversation with the bookrunners, we think the bond is likely to be priced close to that of YNH Property’s 6.85% perp and Tropicana Corp’s 7% perp. YNH’s perp was priced at 349bps over MGS 5Y in August 2019, while Tropicana’s perp was priced at 367 bps over MGS 5Y in September 2019. Based on this pricing guidance, we are of the opinion that the potential coupon rate range of 6.8% to 6.9% would make LBS Bina’s perpetual note attractive in the MYR real estate perpetual space.
Declaration: For specific disclosure, at the time of publication of this report, IFC (via its connected and associated entities) does not have any position in the securities mentioned in the report. The analyst who produced this report holds a NIL quantity in the securities mentioned in the report.