


While Australia remains in an almost perpetual state of lockdown, bonds of a certain Australian company remained at high valuations. Its revenue growth has rebounded, but Australian lockdowns will continue to hinder it. While its credit profile is very strong, there are more attractive alternatives out there.
About Lendlease Group
Lendlease Group (“Lendlease”) is a global real estate and investment group with a presence in Australia, US, Asia, and Europe. It also has a presence in Singapore through its joint venture – Lendlease developed Paya Lebar Quarter and Lendlease Global Commercial REIT, which invested in Jem. Lendlease Global Commercial REIT also manages 313@somerset, a retail mall located in the prime shopping district of Singapore.
Similar to another real estate group – ESR Cayman, Lendlease has three core segments – development, construction and investments. The development segment is focused on the creation of mixed use precincts that comprises of apartments, workplaces and associated leisure and entertainment amenities whereas the construction segment provides project management, design and construction services in various sectors. The investment segment manages funds and assets for money managers including sovereign wealth funds and pension funds. As of June 2021, the Group manages AUD 40b of funds.
Recently, Lendlease reported results for FY21 ending 30 June 2021. Being in the real estate sector, Lendlease also suffered due to COVID-19 effects but its results have rebounded strongly.
FY21 operating results
Lendlease’s core operating profit before tax rose by 87% YoY to AUD 472m in FY21 and total profit after tax increased to AUD 222m after suffering a loss of AUD 310m in FY20. Core segment EBITDA increased by 27% YoY to AUD 918m with the development segment driving most of the gains.
EBITDA for the development segment increased by 46% YoY to AUD 469m in FY21. Two residential towers at One Sydney Harbour, Barangaroo, contributed AUD 325m to EBITDA. However, the management expects that the impacts from COVID-19 will persist into FY22. Also, its pipeline in FY20 of AUD 113.0b was rolled forward with new projects of AUD 8b secured in FY21. After accounting for completions and currency fluctuations, the total pipeline in FY21 stands at AUD 113.6b.
For the construction segment, revenue declined by 16% YoY to AUD 6.40b but EBITDA increased by 71% to AUD 173m. Delays in new projects starts contributed to the revenue declines, however, discipline cost management implemented also led to increase in EBITDA margin. The outlook for this segment is still strong with the Group securing AUD 8.8b of new construction works, with total backlog at AUD 14.9b for FY21.
The investment segment did not perform as well with funds management fees decreasing by 31.6% to AUD 145m due to the performance fee generated from the completion of Paya Lebar Quarter in FY20. However, asset management revenue increased by 32.4% to AUD 139m on the back of securing AUD 1.3b of redevelopment activity. However, funds under management increased by 10% to AUD 39.6b while assets under management declined slightly to AUD 28.5b. Fees should rebound as the retail sector recovers, increasing retail asset management fees. Recurring income should improve as funds under management increase and if return on invested capital recovers to the 5-year average of 6.9% (currently at 5.9%).
However, Lendlease Group generated 56.4% of its AUD 10.19b total revenue in Australia and Australia has been struggling to contain the number of COVID-19 cases despite multiple lockdowns. Melbourne is in its 6th lockdown and has already reached 200 days in lockdown, while Sydney has extended its lockdown till the end of September. As such, we do not expect Lendlease Group’s earnings to rebound dramatically over the next financial year.
Credit profile
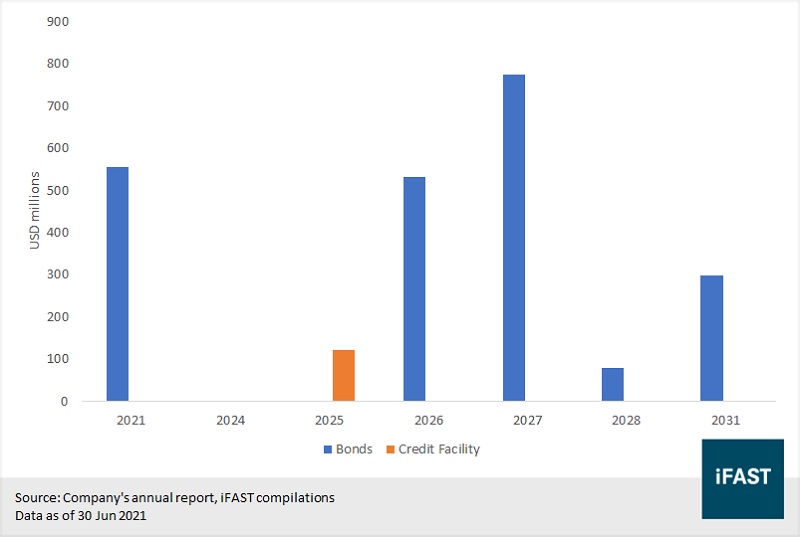
However, there is not much to fret over Lendlease’s credit profile. It has a sizable amount of unused credit facility available, standing at AUD 3.14b as of June 2021. It also does not have much debt expiring in the near term, with only GBP 300m of bonds maturing in October 2021. Its cash position of AUD 1.66b is also enough to redeem those bonds.
Figure 1 :Lendlease Group’s debt maturity profile
While its current liabilities
of AUD 5.98b looks high compared to its current assets of AUD 4.95b, it has AUD
1.38b in construction contract liabilities that are related to billings and
revenue recognised on construction contracts. If required, the Group is able to
draw down on its credit facilities should anything unexpected happens.
Its credit ratios are extremely healthy with net debt/total assets and net debt/equity at ~4.1% and ~10.0% respectively. Its interest coverage ratio (EBITDA/interest expenses) stands at ~4.23x while the Group reported it as 6.4x which excludes a one-off payment in the engineering segment.
Relative valuation
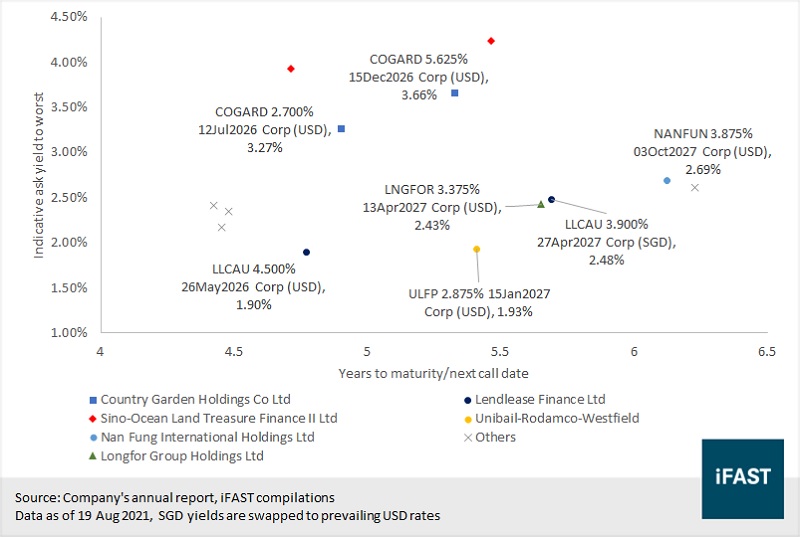
Fitch Ratings affirmed Lendlease Group’s long-term issuer default rating at ‘BBB-‘ in January 2021. When compared to other real estate companies with similar credit ratings, we find that issuers that have similar or lower yields do not have credit ratios that are as healthy as Lendlease’s. For example, Unibail-Rodamco-Westfield (“ULFP”) is still making losses while Longfor Group Holdings Ltd has higher net gearing ratios.
Figure 2: Relative valuation among comparable real estate issues
However,
while the LLCAU 3.900% 27Apr2027 Corp (SGD) notes look relatively attractive in
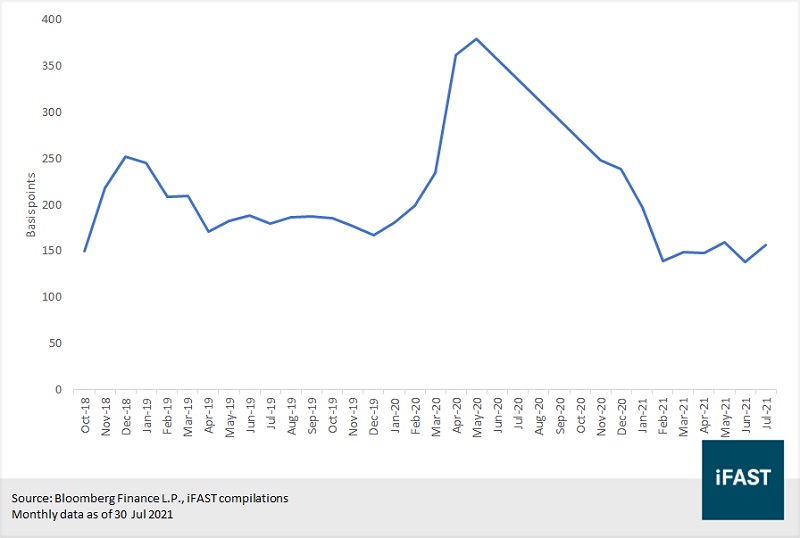
comparison to other ‘BBB-’ names, its credit spreads are quite depressed. The
ask z-spread of the 2027 notes is currently near at its pre-COVID-19 levels and
was at one point, at an all-time low. With Australia still in a bad shape and
the Group still expecting obstacles to revenue growth, we expect the z-spread
to increase.
Together with its high estimated modified duration of 5.11, the bond does not look that appealing. What this suggests is if its benchmark yield, e.g., if 5-year US Treasury, were to rise by 100 basis points (“bps”), the bond’s price could drop by approximately 5.11%, excluding the effects of movements in credit spreads.
Figure 3: Ask z-spread of the LLCAU 3.9% 2027’s
Investors may want to look at
Country Garden’s bonds which we remain positive on. The company has healthy
credit ratios with EBITDA/interest expense at ~9.55x and a net gearing ratio at
~59.7% as at end-2020. The COGARD 2.700% 12Jul2026 Corp (USD) offers a slightly
higher yield with a slightly lower modified duration. Its credit spreads also
look more attractive in comparison to the LLCAU 3.9% 2027’s.
(Related article: Country Garden – An opportunity to capture higher bond yield)
Investors who are willing to go up the risk ladder can also take a look at bonds of ESR Cayman Ltd (“ESR”). Both companies are extremely similar but ESR is more focused on the logistics sector while Lendlease is more diversified. Investors may consider the ESRCAY 5.650% Perpetual Corp (SGD) or the ESRCAY 5.100% 26Feb2025 Corp (SGD).
(Related article: ESR Cayman set to become APAC’s leading real estate manager)
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!