Chinese real estate developers have started the new year with a series of new bond offerings. Logan Group Company Limited (3380.HK, “Logan”) is raising capital to refinance existing offshore indebtedness. Just last month, the issuer raised USD300m through the LOGPH 4.850% 14Dec2026 Corp (USD).
This morning, other developers such as Redsun Properties Group Limited, Seazen Group Limited and Hopsun Capital International Group Co Ltd have also announced bond offerings. Redsun Properties announced a 4-year USD bond at an initial price guidance (“IPG”) of 8.1%. Seazen is looking to issue a 4.5-year note at an IPG of 4.95% while Hopsun Development Holdings is launching a 1-year note at an IPG of 6%.
About the new Logan bond
The 7-year note is expected to be rated BB by Fitch Ratings. Logan is rated BB (stable) / BB (stable) / Ba3 (Positive) by S&P, Fitch Ratings and Moody’s Investors Service respectively. The bond is guaranteed by the Subsidiary Guarantors and the Joint Venture Subsidiary Guarantors on a senior basis subject to certain conditions. Furthermore, the firm has the option to redeem the issue at (i) 102 on or after 13 Jan 25, (ii) 101 on or after 13 Jan 26, or (iii) 100.5 on or after 13 Jan 27.
About the issuer
Logan was incorporated in the Cayman Islands in 2010. They have a 39.2 million square meter (“sq m”) land bank made up of residential properties, retail shops and an office property. As at the end of June 2020, nearly 58.8% of the land bank is located in the Greater Bay Area while 26.4% of the land bank is located in the Southwest region of China. According to the company, the amount of land bank is able to generate real estate development activity for the next five to six years.
Additionally, the company has 24.8 million sq m of urban redevelopment projects that has a saleable resource value of RMB 454.9 billion. These projects could provide more than RMB 150 billion in sales and contribute approximately 20% of core profit annually for the next 3 years. Together with its land bank, total saleable resources including these urban redevelopment projects add to RMB 934.0 billion.
Financial highlights
Logan recorded RMB31.04 billion of total revenue in the six months ended 30 Jun 20 (“1H20”), up 14.9% from RMB 27.02 billion in 1H19. The company made a gross profit of RMB10.93 billion in 1H20 (gross profit margin: 35.2%). Profit after tax was RMB6.28 billion (1H19: RMB5.29 billion) while attributable core profit was RMB5.33 billion in 1H20, up 18.3% from RMB4.51 billion in 1H19.
Attributable contracted sales increased 12.1% to RMB46.35 billion in 1H20 from RMB41.37 billion in 1H19. As disclosed by the company, units were sold at an average selling price of RMB14,985 per sq m, which represents an increase of 13.6% from a year ago.
Logan expects to sell RMB134.0 billion of saleable resource in 2H20, RMB82.2 billion of which is likely to stem from the Greater Bay Area (“GBA”). On a side note, the GBA is a fast growing area that links parts of South China, Hong Kong and Macau. This area is set to rival other Bay areas of the world such as Silicon Valley and could play a leading role internationally in technology, innovation, shipping, trade and finance.
The group also expects to sell some of its Singapore properties that are currently under development. Logan is building The Florence Residences and Stirling Residences, two residential condominiums in Singapore that had 131,423 sq m of gross floor area (“GFA”) at 30 Jun 20.
The interest coverage ratio for Logan is healthy. Based on our estimates, EBIT/Interest (which includes distributions paid to perpetual securities holders) remained at the same level at ~4.2x both in 1H19 and 1H20, even though the company’s average borrowing rate declined from 6.1% in 2019 to 5.93% in 1H20.
Gearing, defined as debt (including liabilities under cross-border guarantee arrangements and perpetual securities) over total assets expanded to 36.6% (2H19: 30.7%) at the end of June, which is a comfortable level among developers in our opinion.
Logan has an adequate liquidity profile. The group’s cash and bank balance of RMB40.15 billion is sufficient to pay down the total short term borrowing amount of RMB39.06 billion consisting of bank loans, senior notes and other current liabilities. In addition, the firm may use the proceeds from this bond offering to repay creditors.
Bond pricing
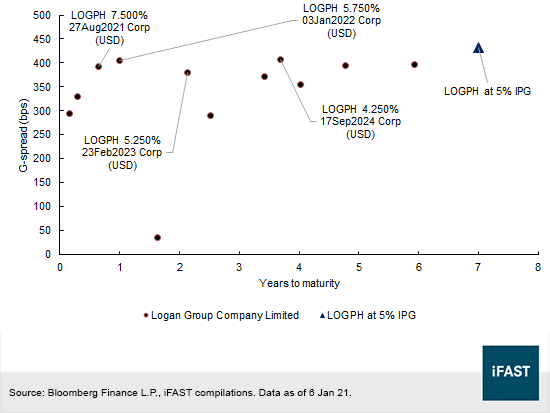
We think that the new 7NC4 bond by Logan is fairly priced compared to other LOGPH notes (Figure 1). With an initial price guidance of 5%, or equivalently 432 basis points (“bps”) above US Treasuries (“G-spread”), the new issue would have the highest credit spread along the LOGPH curve, although we think that investors may also consider the LOGPH 4.250% 17Sep2024 Corp (USD) for its comparable pricing at 372bps spread with a shorter maturity of 3.42 years.
The issuer may use the capital from this issue to redeem the USD300m LOGPH 7.500% 25Aug2022 Corp (USD) (callable on or after 25 Feb 21), USD450m LOGPH 5.250% 23Feb2023 Corp (USD) (callable on or after 23 May 20), USD250m LOGPH 5.750% 03Jan2022 Corp (USD) (callable on 3 Jan 20 and 3 Jan 21), USD 300m LOGPH 7.500% 27Aug2021 Corp (USD) (callable on or after 27 Aug 20), USD 400m LOGPH 6.875% 24Apr2021 Corp (USD) (callable on or after 24 Apr 20), SGD 200m LOGPH 6.125% 16Apr2021 Corp (SGD) (callable on or after 16 Apr 20), or USD250m LOGPH 6.375% 07Mar2021 Corp (USD) (callable on or after 7 Mar 20).
Given that the issuer has USD2.09 billion of offshore notes which are callable or maturing within the next year, the issuer may return to the bond market again to refinance the remaining of its offshore US dollar denominated bonds. Investors looking for BB-rated credits may consider bonds issued by Logan considering that the group has a decent credit profile and adequate near term liquidity.
Figure 1
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) has a principal position in LOGPH 6.125% 16Apr2021 Corp (SGD). The analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!