


By now, the need for business digitalization is becoming more urgent as the disruptions brought about by COVID-19 has changed consumer behavior and their preferred interactions. The pandemic has accelerated current consumption patterns and more companies are shifting business transactions online.
Entertainment companies, cinema operators and concert organizers have recognized the need to reach customers digitally as the cancellation of concerts and shows lead to a loss of revenue. Online viewership among consumers has surged and some media streaming platforms have brought forward their new movie launches. Musicians, likewise, are conducting online concerts after authorities effected bans on mass gatherings for non-essential purposes.
Cathay CineHOME
In the midst of these challenges to the entertainment industry, mm2 Asia Ltd (“mm2”) has announced a new on-demand streaming platform, Cathay CineHOME, to allow subscribers to watch movies that are shown after the theatrical window, or have a limited theatrical run. According to the company’s press release in June, the platform will offer subscribers the option of watching their favorite movies at their own convenience and would serve as a complementary product to the existing cinemas business. Barring unforeseen circumstances, mm2 expects to launch the service in the third quarter this year.
Cathay CineHOME will cater to a sub-segment of movie-patrons but a new streaming platform may not appeal to existing over-the-top (“OTT”) viewers, many of whom are already paying for other streaming platforms. After all, mm2’s new product has a small differentiating factor among streaming services and it is hard to see how Cathay CineHOME will hold up against more established offerings in the market.
Entertainment giants like NBCUniversal, Disney and WarnerMedia are growing their own pay-to-view services, while large technology companies such as Apple and Amazon are expanding investments in movie production. Disney Plus is reportedly arriving in Singapore later this year.
Eventually, the streaming platform that excels in product innovation, content creation and the aggregation of the most local, live and on-demand content will command the highest market share. Competition in the space is likely to intensify over time and this may lead to high barriers to entry and lower operating margins for smaller players that have no alluring content to attract audiences.
Supply-side constraints
In April, we assumed that mm2 would be able to reopen its cinemas in May and the return of moviegoers would help the group mitigate losses. But that has not been the case so far. While we recognized that pent-up demand would benefit cinemas on reopening, the lackluster supply of movie showings has been disappointing.
Theater operators in Malaysia and Singapore were only allowed to reopen cinemas at the beginning of July, which is a two-month delay from our earlier projection. Furthermore, Walt Disney Co. announced that the company will delay the launch of Mulan indefinitely and reschedule the future release of the Star Wars and Avatar installments.
Revenue from theatres is typically linked to box office receipts, and Hollywood blockbusters tend to account for the majority of ticket sales. Last year, those blockbusters generated considerably more sales than locally produced films in Singapore (Table 1). The cancellation of the August release for Mulan is negative for mm2 as the Disney flick is a widely anticipated film and the movie launch could have given the group a much needed cash boost.
Table 1: 2019 top grossing movies in Singapore
|
Movie |
Box office receipts (S$ m) |
Remarks |
|
Marvel Studios’ Avengers: Endgame |
18.27 |
Walt Disney Studios Motion Pictures |
|
Marvel Studios’ Captain Marvel |
9.58 |
Walt Disney Studios Motion Pictures |
|
Spider-Man: Far From Home |
8.83 |
Walt Disney Studios Motion Pictures |
|
Disney’s Frozen II |
7.65 |
Walt Disney Studios Motion Pictures |
|
IP Man 4: The Finale |
7.07 |
Well Go USA Entertainment |
|
Jumanji: The Next Level |
6.46 |
Sony Pictures |
|
Joker |
6.07 |
Warner Brothers Pictures |
|
Disney’s Aladdin |
5.59 |
Walt Disney Studios Motion Pictures |
|
Fast & Furious Presents: Hobbs & Shaw |
5.36 |
Universal Pictures International |
|
Disney’s The Lion King |
5.05 |
Walt Disney Studios Motion Pictures |
|
Movie |
Box office receipts (S$) |
Remarks |
|
A Land Imagined |
26,869 |
Singapore production |
|
Killer Not Stupid |
767,554 |
Singapore production |
|
Make It Big Big |
485,610 |
Singapore production |
|
Revenge of the Pontianak |
509,996 |
Singapore production |
|
Wet Season |
275,611 |
Singapore production |
|
When Ghose Meets Zombie |
307,834 |
Singapore production |
|
Source: IMDA, iFAST compilations |
||
The fact that there is a dearth of Hollywood movies in the theaters right now suggest that cinema operators may be suffering from depressed sales. The social distancing measures in place also further weigh on ticket sales of cinemas. After theaters opened their doors in early July, the distributors for zombie movie Train to Busan: Peninsula – Clover Films and Golden Village Pictures – apparently collected S$147,000 on its first day. This is markedly lower than previous blockbusters, such as the S$7.5m of ticket sales for Avengers: Endgame during its opening weekend in 2019.
FY2020 financial highlights
On 30 May 20, mm2 announced results for the financial year ending 31 Mar 20 (“FY2020”). Total revenue fell to S$235.8m, down from S$266.2m in FY2019. The company revealed that business operations were adversely affected by COVID-19. Movie production delays and the rescheduling of concerts also affected top-line contributions from its core business, cinema and events segments, which accounted for 33%, 37% and 26% of FY2020 revenue (Table 2).
Table 2: Revenue change by segment
|
|
FY2019 (S$ m) |
FY2020 (S$ m) |
YoY change (%) |
|
Core business |
98.2 |
76.9 |
-21.7% |
|
Cinema segment |
100.7 |
87.9 |
-12.7% |
|
UnUsual Limited |
56.2 |
61.7 |
9.8% |
|
Vividthree Holdings |
9.3 |
5.8 |
-37.6% |
|
Others |
1.8 |
3.5 |
94.4% |
|
Source: Company filings |
|||
Core business revenue declined 21.7% year-on-year (“YoY”) to S$76.9m, coinciding with lower ticket sales from its locally produced movies. Based on IMDA statistics, mm2’s local productions Killer Not Stupid and Make It Big Big made S$767,554 and S$485,610 in box office receipts over 2019, lower than ticket receipts from Wonderful! Liang Xi Mei (S$1,758,631), 2359: The Haunting Hour (S$616,313) and Zombiepura (S$359,232) in 2018.
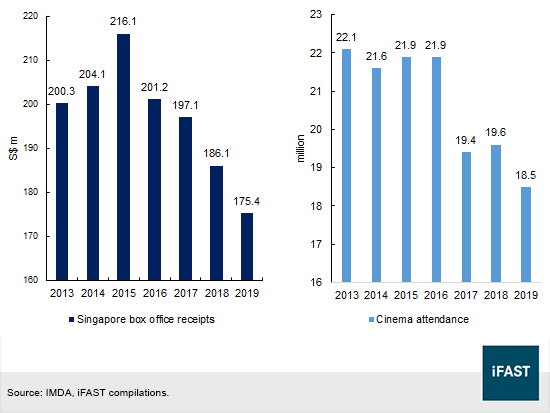
At the same time, sales from mm2’s cinema segment dropped 12.7% YoY to S$87.9m, in tandem with a continued fall in attendances and sales in Singapore during 2019 (Figure 1). A large majority of mm2’s cinema revenue is driven by operations in Singapore, which accounted for S$62.7m, or 71.4% of total cinema revenue in FY2020.
Figure 1: Singapore cinema attendance and box office
Revenue from mm2’s subsidiary – UnUsual Limited – climbed 9.8% YoY to S$61.7m as it managed to host a few concerts by famous singers including JJ Lin, Andy Lau and Eric Chou. Other events such as Walking with Dinosaurs - The Live Experience and Disney on Ice Presents Frozen were also well received by audiences during FY2020.
On a semi-annual basis, group revenue dropped 22% from S$152.3m in 2HFY19 to S$118.3m in 2HFY20. After taking into account S$87.1m of cost of sales and S$36.9m of administrative expenses, we estimated that mm2 had a net loss of S$6.2m for 2HFY20. Admittedly, losses would have been worse had it not been for the recognition of derivative and foreign exchange gains of S$8.5m.
Net cash from operating activities (“CFO”) amounted to S$34.5m in FY2020, while free cash flow was around ~S$28.7m after including disposals and additions to property, plant and equipment. Net CFO was estimated to rise to S$32.8m in 2HFY20 from S$20.9m in 2HFY19. At this rate, we think mm2 could generate up to S$44m of cash flow from operating activities in the current financial year.
Our S$44m cash flow projection may be a tad optimistic, as it is an extension of operating cash flow for the second half of FY2020, a period in which cinemas and concerts were operating at a higher capacity, which is a stark contrast to the current environment. With social distancing measures in place right now, group EBITDA for FY2021 is likely to drop below our baseline projection of S$56.2m in April – an estimate that was derived based on the assumption that cinemas will reopen in May with a gradual pickup in moviegoers towards 4QFY21.
Liquidity profile
As at 31 Mar 20, mm2 recorded S$127.1m of short-term borrowings and S$23.0m of lease liabilities on the balance sheet. The short-term borrowings include a S$47.4m convertible note issued by mm Connect Pte Ltd, a wholly-owned subsidiary of mm2. mm Connect entered into a subscription agreement with certain subscribers to fund the expansion of its cinemas in 2017.
According to an earlier company announcement, the maturity date of the convertible notes shall be the earlier of (1) the initial public offering (“IPO”) date of the issuer or (2) the third-year anniversary from the issuance date of the notes (that presumably falls in February 2021).
In addition, mm2 is obligated to redeem the S$50m MMASIA 7.000% 27Apr2021 Corp (SGD) in April next year. With a cash position of S$29.4m and barring the possibility of a mm Connect IPO, we think mm2 may face a precariously tight liquidity situation next year. Out of the S$29.4m cash position, we noted that its two listed subsidiaries – UnUsUaL and Vividthree – maintained cash and cash equivalents of S$12.6m and S$2.1m respectively (Table 3), leaving less than S$15m at the parent company.
Table 3: Selected financials of mm2 and subsidiaries (FY2020)
|
Figures in S$ ‘000 |
mm2 |
UnUsUaL |
Vividthree |
|
Cash and cash equivalents |
29,383 |
12,574 |
2,123 |
|
Current trade and other receivables |
140,679 |
25,146 |
6,722 |
|
Non-current trade and other receivables |
21,603 |
- |
- |
|
Other current assets |
84,498 |
26,158 |
3,784 |
|
Revenue |
235,774 |
61,943 |
6,136 |
|
Short-term borrowings |
127,081 |
11,358 |
1,700 |
|
Lease liabilities |
23,047 |
- |
205 |
|
Source: Company filings |
|||
mm2 recorded a negative working capital position with S$258.1m of current assets and S$259.7m of current liabilities as of FY2020. According to its latest filing, management submitted a request to the firm’s lenders for a repayment deferment of S$15.5m. The lenders have acceded to the request and deferred the payment to February next year. However, this six-month deferment does not lower the S$127.1m of borrowings due by March 2021. We did learn that the group secured a S$6.6m credit facility recently, but that will likely help meet general working capital requirements for just a few months.
On a separate note, the recoverability of trade and other receivables is also a concern as the group’s receivables turnover is more than 260 days by our estimation. As highlighted in mm2’s FY2019 report, trade receivables, which accounted for 54.5% of current assets, are balances due from local and overseas customers. Aging receivables above six months represented nearly half of trade receivables at 31 Mar 20. Lastly, expected credit losses on trade receivables have increased to S$3.2m in FY2020, up from S$2.2m in FY2019.
Recommendation
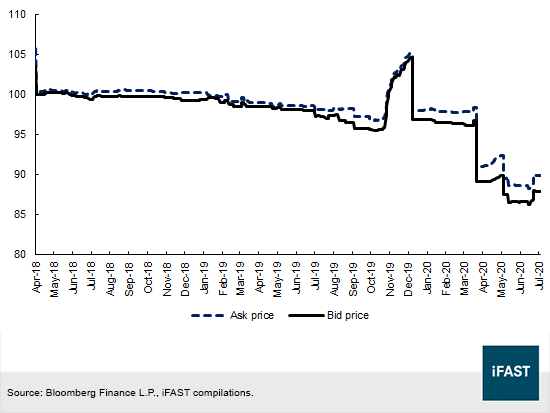
At this juncture, the aforementioned factors have led us to downgrade our outlook on the MMASIA 7% ‘21s. Bid prices on the bond have fallen to 86 on 27 Jul 20 and the sizeable bid-ask spread may necessitate bondholders who are thinking to exit to do so at a prohibitive cost. Bondholders may switch into one of our recommended bonds or consider other notes that we think are still attractive for the longer term.
Figure 2: Bid and ask prices for the MMASIA 7.000% 27Apr2021 Corp (SGD)
As mentioned earlier, a mm Connect IPO will help to alleviate the cash flow burden of the group. mm Connect owns Cathay Cineplexes Pte Ltd, mm2 Star Screen Sdn Bhd (“mm2 Star”) and holds a 30% interest in River Front Mega Cineplex Sdn Bhd (“Mega”). mm2 Star is a Malaysian subsidiary that acquired 13 theatres from Lotus Five Star Cinemas (M) Sdn Bhd for MYR 98m (~S$37.8m) in 2017.
mm2 ran 19 cinemas in Malaysia during 2019 but we believe that not all of them are open at the moment. In aggregate, the group has 214 screens in 28 locations in Singapore and Malaysia. A divestiture of these assets through an equity offering will provide more liquidity to the entertainment company.
Other possible sources of liquidity include the sale of the company’s stakes in UnUsUaL (shareholding of 39.2%) or Vividthree (41.53%), listed entities with market capitalizations of S$147.2m and S$24.0m respectively. However, the group continues to believe in the long-term viability of these businesses and it is likely that the subsidiaries may resort to issuing shares to raise funds in our view.
If conditions in the SGD bond market improve, mm2 may also seek to refinance the MMASIA 7% ‘21s with a new issuance. But investors will need to be convinced that there is a sustained demand for movie-going activity and locally produced media. At this juncture, we think investors may not be keen to allocate capital to such firms given the murky outlook on the recovery of the entertainment sector, and the pandemic has accelerated the trend of content moving to streaming platforms and away from cinemas. That aside, mm2 may possibly work with creditors to restructure their borrowings, but we think lending standards might tighten in the future, especially when the loan moratoriums provided by banks end and credit costs rise.
Overall, we are erring on the side of caution in light of ongoing structural changes in the entertainment industry. Mm2 faces elevated refinancing risk and we advise bondholders to look out for opportunities to sell their holdings or switch into other bonds. With the resurgence of virus cases and the possibility that a vaccine may take longer to be developed, we are uncertain if cinema attendances or movie production will return to normalcy soon.
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a principal position in MMASIA 7.000% 27Apr2021 Corp (SGD). The analyst who produced this report holds a NIL position in the abovementioned securities.










