


mm2 Asia Ltd. (“mm2 Asia”), a media company listed on the Singapore exchange has made a series of announcements recently. We believe that the situation surrounding the company is fluid and still unfolding so note that the information in this article reflects all publicly available information as at 5 Feb 21, 8:50am.
On 2 Feb 21, the group requested for a trading halt in its shares. A day later on 3 Feb 21, the company announced that it is proposing a rights offering of up to 1,162,804,610 new shares at an issue price of S$0.047 for each rights share.
This issue price of S$0.047 for each rights represents a 60.83% discount to the last traded price of S$0.12 on 1 Feb 21. However, the rights issue is subjected to the approval of shareholders at the upcoming extraordinary general meeting (“EGM”).
As shareholders are allowed to subscribe for excess rights, there may be a change in controlling interest as a result of this exercise. Shareholders will therefore also vote on a resolution involving the potential transfer of controlling interest. If the rights issue resolution is not passed, the potential transfer resolution will also not be passed.
mm2 expects to raise S$54.65m from gross proceeds of this rights offering, out of which up to S$51.75m are intended to be deployed to repay the MMASIA 7.000% 27Apr2021 Corp (SGD) due on 27 Apr 21.
As mentioned in the announcement on 3 Feb 21, the Executive Chairman and 38.11% shareholder of the firm, Mr Melvin Ang has expressed his intent to subscribe to his pro rata entitlement of the rights issue, on condition to the availability of financial resources.
Other substantial shareholders are invited to subscribe to the rights if the rights resolution is passed. StarHub Ltd., a 9.83% shareholder of the company as at 18 Aug 20, will be asked to provide further capital to the company. The invitation extends to Mr. Yeo Khee Seng Benny, who was a 8.36% equity owner of the firm. Part of the shares are held in Apex Capital Group Pte. Ltd., which is 70% owned by Mr Yeo.
Public investors, who made up 38.23% of the total share capital, will likely decide on the outcome of the rights resolution and have to decide if they want to provide additional funding to the firm.
At this point, it remains uncertain if the entire S$54.65m will be raised successfully from shareholders even if the resolutions are passed at the EGM. Only one shareholder – Mr Melvin Ang has expressed to provide up to S$20.8m for the bond offering.
Extension of maturity date of convertible bonds
In connection with the rights issue and as part of the underwriting agreement between the group and UOB Kay Hian, mm2 has extended the maturity of its S$47.85m convertible notes issued by its subsidiary, mm Connect Pte Ltd (“mm Connect”). Although this will alleviate the current financial obligations of the company, the amount of borrowings due in the short term is high relative to the amount of cash on the balance sheet on 30 Sep 20.
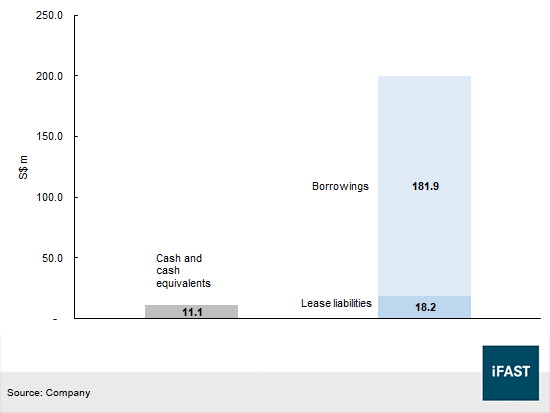
In the financial statements for the half-year ended 30 Sep 20 (“1HFY21”), mm2 reported S$11.1m of cash and cash equivalents and S$181.9m of current borrowings. Excluding the S$47.85m convertible bond, the level of current borrowings may have dropped to ~S$134.0m.
With a cash position of S$11.1m and cost of sales of S$19.7m during 1HFY21, we think that the company faces a tight liquidity situation. However, the firm has maintained that the group is not under pressure from its bankers to repay debt nor are there any arrangements to refinance any of its borrowings. mm2 said that it has adequate resources to meet capital commitments in view of its bank facilities and internal resources.
Possible spin-off of the cinema business
In December, the company announced that it is considering a spin-off and public listing of its cinema business, which is currently operating under mm Connect.
A few days later, mm2 informed the exchange that it plans to merge its cinema business with Golden Village cinemas in Singapore, which are managed by Orange Sky Golden Harvest Entertainment (Holdings) Ltd (“OSGH”). mm2 oversees 8 cinemas in Singapore under the “Cathay” brand and 14 cinemas in Malaysia under the “Cathay Cineplexes Malaysia”, “Mega Cinemas” and “Lotus Fivestar” brands.
The proposed merger transaction is subjected to requisite approvals from various parties including shareholders of both mm2 and OSGH, as well as the competition and consumer commission of Singapore in relation to anti-trust issues.
As a matter of interest, OSGH was in a stronger credit position than mm2. OSGH’s gearing ratio, defined as bank borrowings over total assets was 28.3% at 30 Jun 20, while its cash to bank borrowings ratio was 97.0%, implying that it had adequate amounts of liquidity to support its cinema business in the midst of a sharp drop in cinema attendances and virus pandemic. Even though OSGH has a stronger balance sheet than mm2, it is not clear if the Hong Kong listed company would still proceed with the merger especially when there is an excess capacity of cinemas in the industry.
mm2 is proposing to work on both the proposed merger in parallel with the spinoff listing. However, the proposed merger may be terminated if the conditions for the proposed merger cannot be agreed by 31 Dec 21. Any material corporate developments related to the proposed transaction or spinoff will be announced in due time.
1HFY21 results
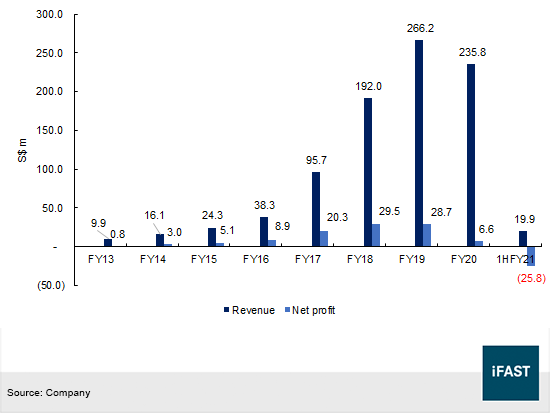
During 1HFY21, mm2 reported a 83.0% fall in revenue to S$19.9m from S$117.4m in the six months period ended 30 Sep 19. Gross profit plunged 99.8% YoY from S$58.2m in 1HFY20 to S$130,000 in 1HFY21. Looking at FY2022, the group guided that the cinema business remains weak but it has received a strong pipeline of over 20 titles that will be released in future, exceeding its typical 14 to 18 titles annual titles in previous years. After accounting for administrative expenses and other charges, the company swung from a profit of S$12.8m in 1HFY20 to a loss of S$25.8m (Figure 1).
Figure 1: Revenue and net profit since FY2013
Net cash flows generated from operating activities also swung from a cash inflow of S$1.7m to a cash outflow of S$1.6m. Operating cash flows before working capital changes remained positive but declined materially to S$7.2m at 1HFY21 from S$50.3m in 1HFY20. The changes are in line with the group’s EBITDA of S$6.2m in 1HFY21 compared to S$50.1m in 1HFY20.
As mentioned earlier, mm2 registered cash and cash equivalents of S$11.1m at 30 Sep 20, but part of this is probably held at its subsidiaries – Vividthree Holdings Ltd. (1HFY21: S$1.5m) and UnUsUaL Limited (1HFY21: S$5.6m), leaving just S$4.1m at the parent firm. In addition to the S$181.9m (or ~S$134m excluding the convertible bond) of short term borrowings, the group also has S$18.2m of current lease liabilities.
Figure 2: Cash and current financial obligations as at 1HFY21
The sharp fall in profitability resulted in a sharp deterioration in mm2’s credit profile in the six month period before 30 Sep 20. Gearing, measured as the ratio of debt to total assets increased from 35.6% in 2HFY20 to 37.4% in 1HFY21due to an increase in total debt from S$262.4m to S$264.4m. EBITDA over interest expense, taken as a gauge of the group’s interest servicing ability plummeted from 6.4x in 1HFY20 to 0.8x in 1HFY21.
Our recommendation
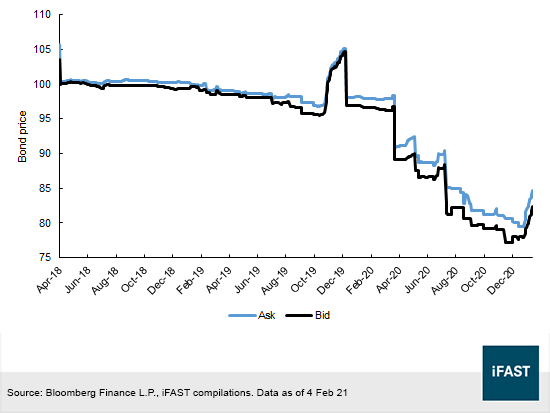
Trading for the MMASIA 7.000% 27Apr2021 Corp (SGD) has been suspended on the exchange but indicative ask prices for the notes in the secondary market were trading at 95 while bid prices held around 85 on 4 Feb 21. Liquidity for the S$50m issue has historically been low as the latest bid-ask spread showed a 10% difference between the quotes. Bid-ask spreads may tighten however in view of the slew of upcoming corporate developments such as the upcoming EGM and the announcement of the raising of capital through the rights issue.
This morning on 5 Feb 21, a company announcement said that the Singapore Exchange has granted the company’s request to extend the trading halt till the end of Friday as the firm will be releasing further material information. Given the recent fluid corporate developments, coupled with the company’s tight financing situation and the possibility that the issuer may not raise enough capital for the bond repayment, we are keeping our negative view on the issuer and an underweight recommendation on the MMASIA 7% 21’s. This is in line with our previous credit opinion as mentioned in the article - “mm2 Asia: Credit Update 29 Jul 20”.
Figure 3: Bid and ask prices for the MMASIA 7.000% 27Apr2021 Corp (SGD)
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) has a principal position in MMASIA 7.000% 27Apr2021 Corp (SGD). The analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!


