In this series of articles, we provide an overview of issuers currently on our watchlist, including the latest developments and our commentary on each issuer.
But before that, we have also provided a summary of several issuers that we are keen on:
|
Company |
Latest Developments |
Related article |
Comment |
|
Tropicana (5Y sukuk at 6% IPG) |
- In 1Q26, revenue increased by 20.5% yoy to RM313mil, driven by higher progress billings arising from the completion of several projects within the Klang Valley and Northern regions. - Bottom line remained in the red, attributable to mark-to-market loss on quoted shares amounting to RM16.7 million, which was a non-cash item. Excluding this, the group would have recorded a profit before tax of RM3.9 million. - Tropicana has been actively deleveraging through asset monetisation and project completions, demonstrating continued commitment to debt reduction. - Possess a sizeable landbank of 1,336.1 acres across Malaysia, with an estimated GDV of RM97 billion as at 31 Dec 2025. |
- Anticipate continued improvement in the group’s profitability and balance sheet, with expansion in Johor serving as a key catalyst for future revenue growth. - View risk-reward profile for the sukuk as well justified, with 1.5 times security cover (landbank). |
Moving on to the next segment, here are the latest updates on issuers we are closely monitoring, which is exhibiting elevated credit risk or even under financial distress. We have marked the changes from the previous update in bold.
|
Company |
Latest Developments |
Related article |
Comment |
|
Tan Chong Motor Holdings Berhad |
- In 1Q26, the Group's performance remained under pressure, with revenue declining 17.2% YoY to RM457.8 million and a loss before tax (LBT) of RM8.3 million, despite recognising a RM20.1 million gain from the disposal of an asset classified as held for sale. - Operating cash flow before working capital changes is at negative RM31.1 million during the quarter. |
Cloudy outlook for Tan Chong Motors |
- While July’s new RM200,000 CIF shield Tan Chong’s CKD pipeline and its Serendah assembly partnership for the Perodua QV-E, the operational turnaround remains in a monitoring phase, keeping us structurally negative from a bond perspective. |
|
Pestec International Berhad (deferred coupon x 2) |
- The group recorded a 13% qoq revenue decline to RM43.8 mil, due to lower revenue recognition within rail division. - Short term borrowing came in at RM358.5 mil, significantly more than cash and short-term deposits (RM71.1 mil) that the group has. - Given the current financial situation, we are of the view that further coupon deferment may continue. |
Nil |
- We are negative on Pestec’s ability to service coupon payments and principal redemption. - We believe that the company will involve perpetual holders in the restructuring plan, though timeline remains unknown. |
|
YNH Property Bhd (deferred coupon x 1) |
- On 8 July 2026, YNH announced the proposed disposal of a freehold commercial development land in Kuala Lumpur to Chin Hin Property (JSI) Sdn. Bhd. for RM455 million. - Cash proceed from the land disposal is primarily earmarked for the redemption of perpetual securities, thereby reducing stepped-up coupon obligations and improving liquidity. - The proposed disposal is subject to the fulfilment of customary conditions, including shareholders' approvals, relevant regulatory approval and more. |
Proposed YNH Land Disposal Positive for Perpetual Bondholders |
- We view the proposed disposal as positive for YNH's perpetual bondholders. - Despite that, we maintain our negative view on YNH. Tight liquidity, subdued revenue recognition, and continued reliance on asset disposals to meet debt obligations remain key credit concerns. |
|
Evergrande |
- Evergrande has officially entered a forced liquidation, and Alvarez & Marsal is the liquidator to handle the asset disposal. - Capability of liquidator is key to max recovery value for debtholders. Liquidators have experience in Lehman Brother and Luckin Coffee. - Hong Kong regulators fines PwC HKD1.3 billion over Evergrande audit work. |
The court ordered the liquidation of China Evergrande |
-The liquidation process is still ongoing, and we posit that it will take a couple of years to complete due to its scale. |
|
Century Sunshine |
-Trading in CENSUN shares has been suspended since 1 April 2025 due to the company’s failure to release its 2024 Annual Report on time. -No dividend was declared for the second scheme year, as the proceeds from the share disposals were insufficient to cover the scheme costs. -There is still no decision on whether the Zhangzhou Land should continue to be reserved for the bridging loan or be disposed of. -The Luozhuang Government unilaterally terminated the relocation agreement on the ground that Shandong Hongri failed to carry out soil remediation. Shandong Hongri appealed the decision, arguing that the termination is unjustified because no clear remediation standards had been provided. - One of Shandong Hongri’s creditors obtained an enforcement ruling ordering the auction of part of its land-use rights. The land is to be auctioned as “industrial land,” resulting in a significantly depressed valuation. Shandong Hongri has filed objections and applied to revoke the enforcement ruling and to stay the auction proceedings. |
-Listing status may be cancelled if the suspension remains in effect until 30 Sep 2025. Given that there are no other available assets, we hope the land title conversion of the Shandong Land will be successfully completed, as it is likely to unlock higher value when the land is disposed of after the conversion. |
In the next section, we will delve into the insights of the yield curves for Malaysian Government Securities (MGS), US Treasuries (UST), Singapore Government Securities (SGS) and Australia Government Securities (AGS).
Our view on MGS:
1) Headline inflation is expected to stay within BNM's 1.5–2.5% target, supported by targeted subsidies and government assistance measures.
2) Hence, BNM is expected to keep policy rates unchanged at 2.75% throughout 2026.
3) Domestic election-related risk and elevated US Treasury yields are likely to exert modest upward pressure on Malaysian government bond yields.
4) Defensive fixed income positioning: Prefer the 3–5 year MGS segment and selectively accumulate A-rated corporate bonds to benefit from attractive credit spreads while managing duration risk.
Chart 1: MGS Curve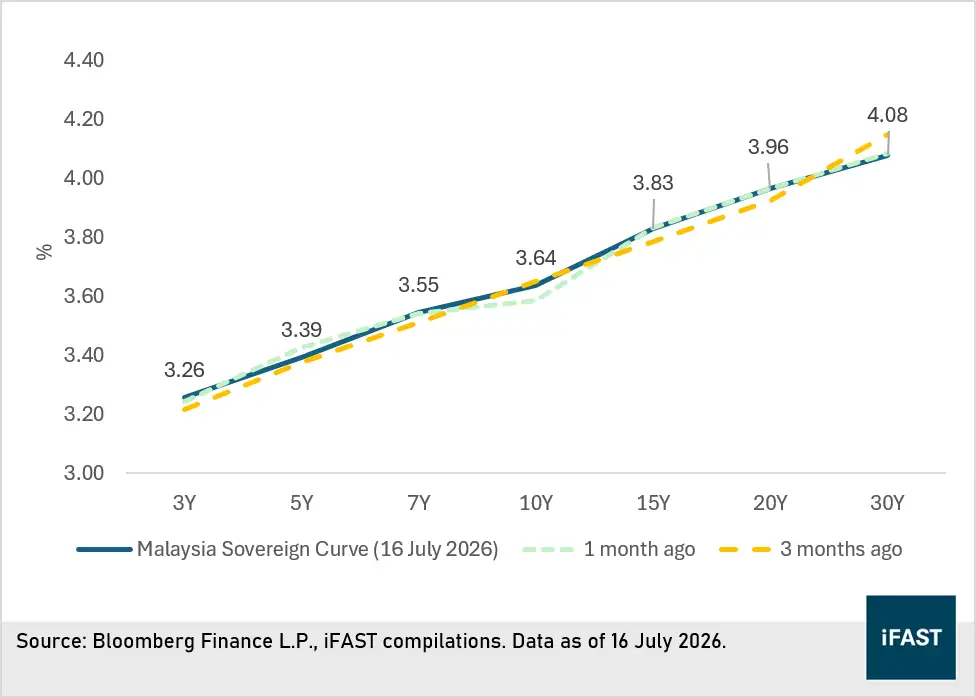
Our view on UST:
1) Fed rate cuts appear increasingly unlikely in the near term, as sticky inflation and resilient economic growth reinforce the higher-for-longer interest rate outlook, with some possibility of rate hikes.
2) Short and medium-term bonds remain relatively attractive, supported by elevated yields and opportunities to selectively lock in attractive returns from high-quality corporate issuers while limiting duration risk.
3) Long-term bonds remain the least preferred segment, given their greater sensitivity to interest rate volatility and the potential for higher long-end yields amid persistent inflation risks and evolving Fed policy.
Chart 2: UST Yield curve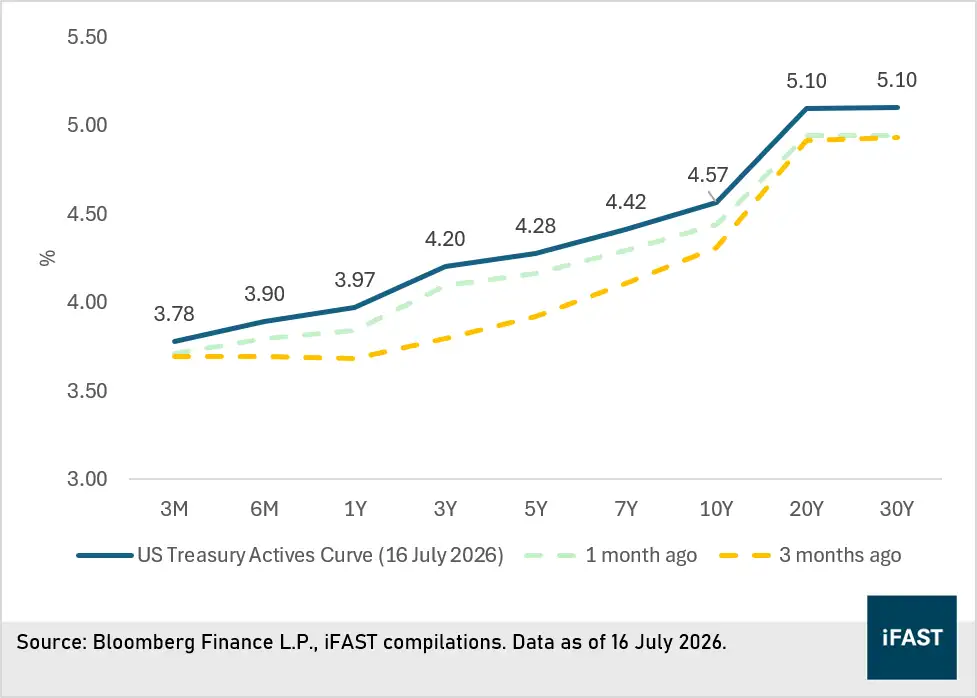
Our view on SGS:
1) Singapore interest rates are expected to remain rangebound with an upward bias, as potential global rate hikes provide upward pressure, while continued safe-haven and wealth inflows help anchor yields.
2) Favour shorter-term bonds (3-5Y); Selectively constructive on medium tenor issues (5-8Y).
Chart 3: SGS Yield curve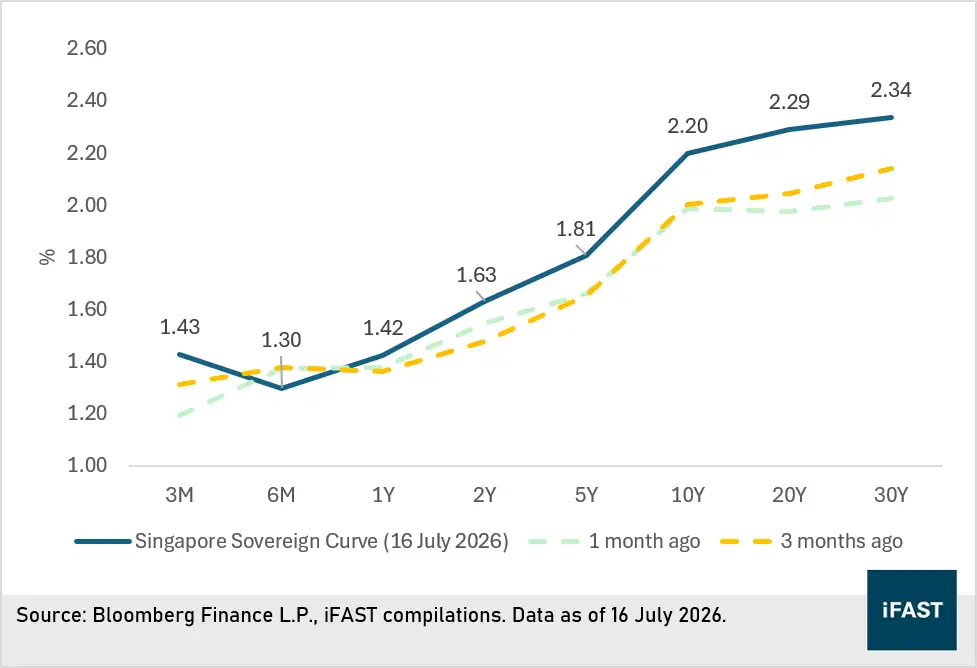
Our view on AGS:
1) Headline inflation moderated to 4.0% yoy in May 2026, while trimmed mean inflation hiked to 3.6% yoy. These are still above RBA’s target inflation of 2%-3%.
2) However, with the previous three consecutive rate hikes to 4.35% by Reserve Bank of Australia, coupled with relatively weak economy, cooling housing market and cautiously spending consumer, we believe the current rates now appear close to the terminal rate, while not ruling out one more rate hike.
3) We continue to favour a Barbell strategy, allocating exposure to both short-duration bonds (1-year tenor) and longer-duration bonds (7 – 10-years).
Chart 4: AGS Yield curve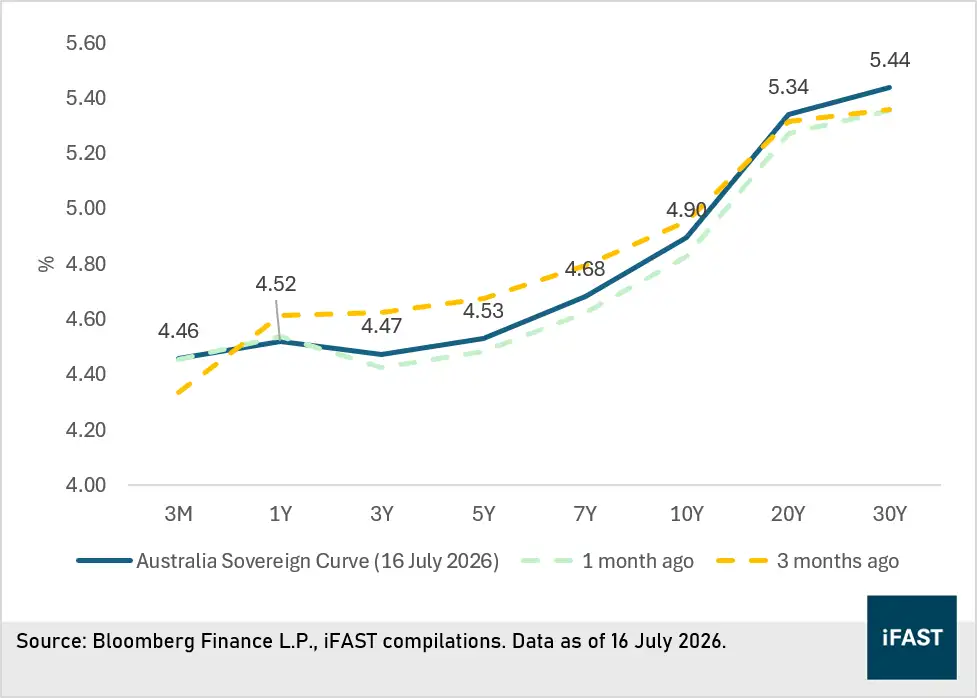
Some of the Credit Announcements by RAM & MARC (1 June - 30 June 2026)
RAM
1) RAM Ratings Affirms AAA Ratings on Sukuk Programmes Issued by Sarawak State SPVs
2) RAM Ratings affirms Pavilion REIT Capital’s program at AA3
3) RAM Ratings maintains AEON Credit's Sukuk Ratings at AA3
https://www.ram.com.my/news-events/?tab=list-ratingannouncement
MARC
1) MARC Ratings affirms its AA- rating on KAJV programme
2) MARC Ratings assigns final ratings of AA- to Moneymax programme
3) MARC Ratings affirms Farm Fresh’s AA- rating
https://www.marc.com.my/insights/rating-announcements/
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds position in DJCMK 6.100% 31Mar2031 Corp (MYR), DJCMK 6.250% 13Nov2028 Corp (MYR), DJCMK 6.000% 15Jul2031 Corp (MYR), COGARD 2.250% 31Dec2034 Corp (USD), COGARD 1.250% 31Dec2036 Corp (USD), COGARD ZERO 31Dec2034 Corp (USD), CENSUN 7.000% 03Jul2020 Corp (SGD) and EVERRE 8.250% 23Mar2022 Corp (USD), and the analyst who produced this report hold a NIL position in the abovementioned securities.