


Here are the latest updates on issuers we are closely monitoring, which is exhibiting elevated credit risk or even under financial distress. We have marked the changes from the previous update in bold.
|
Company |
Latest Developments |
Related article |
Comment |
|
Tan Chong Motor Holdings Berhad |
- In 1H26, the Group's performance remained under pressure, with revenue declining 14.9% YoY to RM929.6 million. - The Group’s loss before tax narrowed to RM39 million, mainly due to a RM20.1 million gain recognised on the disposal of an asset classified as held for sale. - On 12 June 2026, minority shareholders voted overwhelmingly against the proposed mandates for Recurrent Related-Party Transactions (RRRTs) at the AGM. - Tan Chong has signed a three-year master agreement with Perodua Sales to provide ED coating and painting services, as well as rent out designated assembly lines for Perodua’s BEV project. |
- While July’s new RM200,000 CIF shield Tan Chong’s CKD pipeline and its Serendah assembly partnership for the Perodua QV-E, the operational turnaround remains in a monitoring phase, keeping us structurally negative from a bond perspective. - We are of the view that sales will remain under pressure amid intensifying competition in Malaysia’s automotive industry. |
|
|
Tropicana Corp |
- In 1H26, revenue increased by 97% YoY to RM1,164 mil, driven by a one-off gain on the disposal of three land parcels, together with stronger progress billings. - Bottom line remained in the red, attributable to mark-to-market loss on quoted shares amounting to RM23.1 million, which was a non-cash item. Excluding this, the group would have recorded a higher profit before tax of RM32.2 million. - Tropicana has been actively deleveraging through asset monetisation and project completions, demonstrating continued commitment to debt reduction. - Possess a sizeable landbank of 1,349.7 acres across Malaysia, with an estimated GDV of RM102.6 million as of June 2026. - Tropicana has announced that it will not exercise the call option on its perpetual securities, which have a next call date of 15 September 2026. Management cited delays in land sales as the reason for the decision. |
-Anticipate continued improvement in the group’s profitability and balance sheet, with expansion in Johor serving as a key catalyst for future revenue growth. - Despite the non-call event, we believe Tropicana’s repayment capacity remains intact at this juncture, supported by its ongoing deleveraging efforts, sizeable unbilled sales and substantial landbank. |
|
|
Serba Dinamik |
- The liquidation process remains ongoing. As of today, there has been no major breakthrough or definitive restructuring outcome announced. - The liquidator of Serba Dinamik has filed a lawsuit against former external auditor KPMG, claiming that KPMG failed to perform sufficient audit procedures and should have identified financial misstatements earlier.
- The liquidator is seeking at least RM1.56 billion in damages + interest.
|
NiL |
-The lawsuit introduces a potential additional source of recovery value for creditors should the liquidator successfully secure compensation from KPMG. -However, given Serba Dinamik’s substantial debt burden relative to its asset base, the overall recovery prospects remain highly uncertain. -Considering the uncertainties surrounding the litigation outcome, asset realisation process and liquidation timeline, potential recovery value remains fuzzy. |
|
Pestec International Berhad (deferred coupon x 2) |
- 1QFY27 (30 Jun 2026) was a rough quarter, with revenue plunging 82% YoY to RM21.4m as the Iraq and Cambodia projects wound down. The Group swung to a RM19.3m pre-tax loss from RM171.2m profit a year earlier, although the latter was boosted by a one-off debt-waiver gain. - Cash is also thinning, falling to RM57.1m from RM71.2m as at 31 Mar 2026. The auditor flagged that the Group may need to rely on parent support from Dhaya Maju to continue operations. - Given the current financial situation, we are of the view that further coupon deferment may continue. |
Nil |
- We are negative on Pestec’s ability to service coupon payments and principal redemption. - We believe that the company will involve perpetual holders in the restructuring plan, though timeline remains unknown. - We will continue to keep investors updated should there be any firm decision or outcome from the issuer. |
|
YNH Property Bhd (deferred coupon x 2) |
- On 23 July 2026, YNH announced its second coupon deferral exercise for both outstanding perpetual securities tranches, deferring a combined RM34.41 million in coupon payments to preserve cash reserves for its active development pipeline and operational needs. - Based on FY26 (June 2026), revenue decreased significantly by 71% YoY, from RM391.6 million to RM112.6 million, mainly due to the disposal of 163 Retail Park in 2QFY25 (December 2024), which generated RM215 million in revenue and resulted in a high base in the previous year. - YNH recorded a loss before taxation of RM105.3 million, mainly due to a one-off impairment of RM35 million on other receivables and a RM38.5 million provision for foreseeable losses on projects. - Revenue for the current financial year was mainly derived from the disposal of development land in Mont Kiara, progressive profit recognition from Solasta Dutamas (Mont Kiara), as well as inventory sales from Manjung Point Seksyen II and sales investment properties. - YNH’s liquidity position remains constrained. As of FY26, the Group’s available cash of RM47.7 million remains insufficient to fully cover its short-term debt maturity of RM367.3 million due within one year. |
YNH Property Quick Update – Defers Perpetual Securities Coupon for a Second Time |
- We view the proposed disposal as positive for YNH's perpetual bondholders. - Despite that, we maintain our negative view on YNH. Tight liquidity, subdued revenue recognition, and continued reliance on asset disposals to meet debt obligations remain key credit concerns. |
|
Zetrix AI |
- Zetrix AI sharp decline and insider selling could weaken investor confidence and make future refinancing more challenging. - From our perspective, the corruption-related speculation is not a fundamental issue for Zetrix AI, as the company has clarified that it was not involved in the case. With its previous foreign-worker permit business revoked in July 2025. - Zetrix is now increasingly focused on blockchain and AI, with the key concern being whether its sizeable development costs can be monetised to generate sufficient cash flow to support its higher debt burden. - Zetrix AI has significantly increased its blockchain-related development spending, with capitalised development costs rising from RM323 million in FY2021 to RM3.7 billion in 2QFY26. - The expansion has been increasingly debt-funded, with total borrowings rising from RM161 million to RM2.2 billion, while net gearing increased to approximately 38%. - Nonetheless, near-term refinancing remains manageable support by strong operating cash flow of RM982m in FY25 and RM542m cash as of 2Q26 (June 26) provide support for the RM775m FY27 maturity. |
Zetrix AI’s Sharp Share Price Decline: What Does It Mean for Bondholders? |
We remain comfortable holding bonds maturing up to Nov 2027, while remaining cautious on bonds maturing beyond 2027 given the uncertain monetisation of blockchain/AI activities. - We will monitor the situation and may change our recommendation based on further information. |
|
Evergrande |
- Evergrande has officially entered a forced liquidation, and Alvarez & Marsal is the liquidator to handle the asset disposal. - Capability of liquidator is key to max recovery value for debtholders. Liquidators have experience in Lehman Brother and Luckin Coffee. - Hong Kong regulators fines PwC HKD1.3 billion over Evergrande audit work. |
A List of 30 Key Chinese Developers’ Latest Development (Updated on 8 May) |
-The liquidation process is still ongoing, and we posit that it will take a couple of years to complete due to its scale. |
|
Century Sunshine |
-Trading in CENSUN shares has been suspended since 1 April 2025 due to the company’s failure to release its 2024 Annual Report on time. -No dividend was declared for the second scheme year, as the proceeds from the share disposals were insufficient to cover the scheme costs. -There is still no decision on whether the Zhangzhou Land should continue to be reserved for the bridging loan or be disposed of. -The Luozhuang Government unilaterally terminated the relocation agreement on the ground that Shandong Hongri failed to carry out soil remediation. Shandong Hongri appealed the decision, arguing that the termination is unjustified because no clear remediation standards had been provided. - One of Shandong Hongri’s creditors obtained an enforcement ruling ordering the auction of part of its land-use rights. The land is to be auctioned as “industrial land,” resulting in a significantly depressed valuation. Shandong Hongri has filed objections and applied to revoke the enforcement ruling and to stay the auction proceedings. - The annual update is expected to be released by 20 September 2026 |
-Listing status may be cancelled if the suspension remains in effect until 30 Sep 2026. Given that there are no other available assets, we hope the land title conversion of the Shandong Land will be successfully completed, as it is likely to unlock higher value when the land is disposed of after the conversion. |
|
|
Source: iFAST compilation, based on the latest available in-house coverage. Data as of 15 Sep 2026 |
|||
In the next section, we will delve into the insights of the yield curves for Malaysian Government Securities (MGS), US Treasuries (UST), Singapore Government Securities (SGS) and Australia Government Securities (AGS).
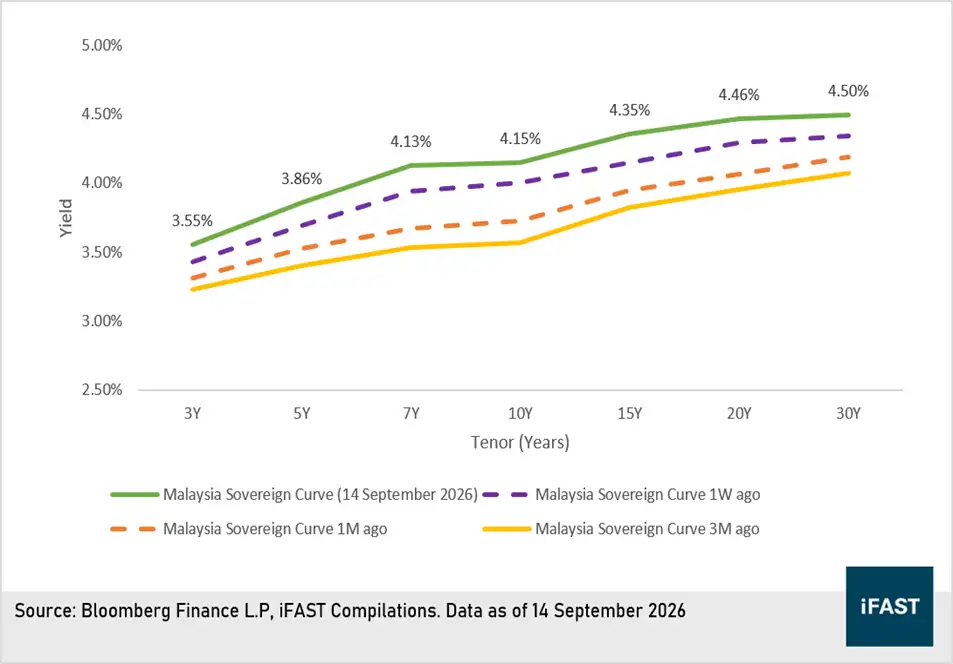
Our view on MGS:
1) The sharper-than-expected increase was mainly driven by the renewed escalation in the US-Iran conflict, which pushed crude oil prices higher and raised concerns over global inflation, indirectly pushing risk premium higher.
2) We expect BNM to keep the OPR (2.75%) unchanged through 2026, as resilient domestic growth with manageable inflation.
3) We see little room for MGS yields to retrace lower in 2H26, as global yield repricing and domestic political uncertainty continue to weigh on market sentiment with risks tilted to the upside.
4) We prefer the short-to-medium segment of the curve, particularly the 3–5-year tenor.
Chart 1: MGS Curve
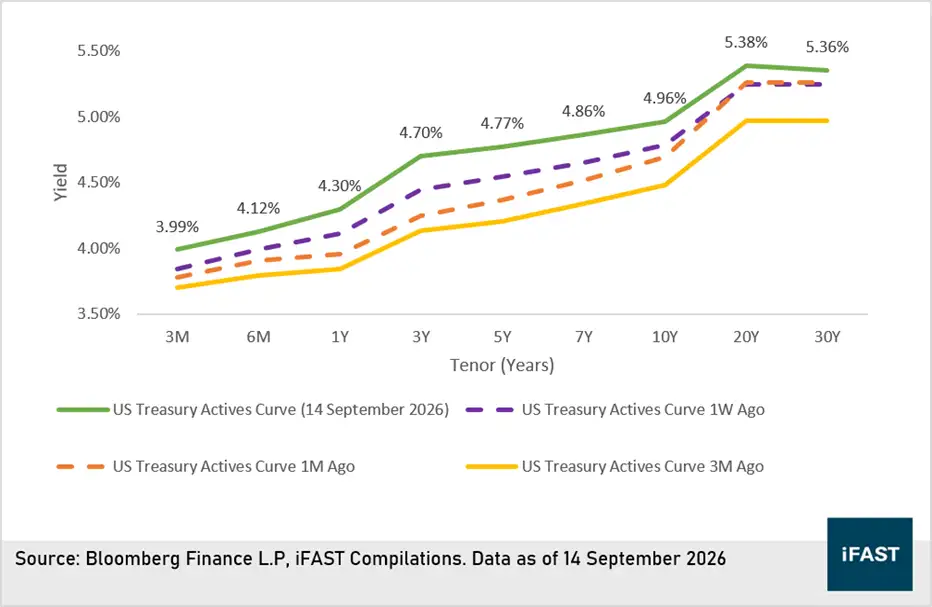
Our view on UST:
1) We see scope for potential rate hikes amid the Middle East conflict, alongside persistent inflationary pressures from tariffs and fiscal stimulus that could drive inflation higher.
2) We favour short and medium-duration bonds:
· Short-term: low sensitivity to interest rate movements.
· Medium-term: On selective basis (focusing on companies with strong balance sheets and good fundamentals)
Chart 2: UST Yield curve
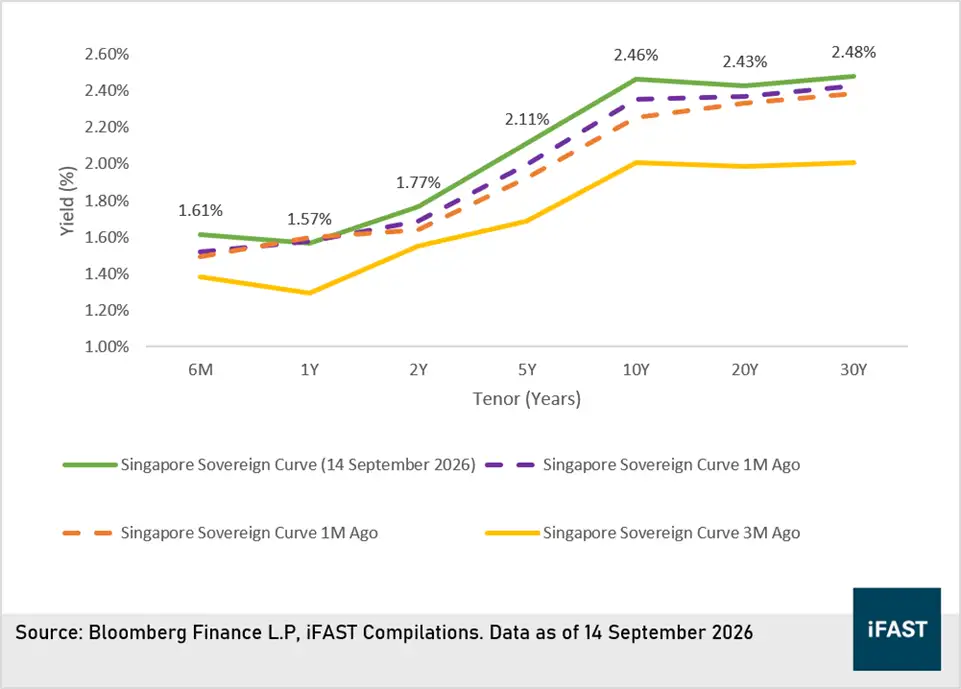
1) Singapore interest rates are expected to remain rangebound with an upward bias, as potential global rate hikes provide upward pressure, while continued safe-haven and wealth inflows help anchor yields.
2) For bond recommendations, we favour:
- Short-term SG T-bills: Rolling 6-month to 1-year T-bills to remain nimble amid the uncertain rate environment.
- SGD financial corporate bonds: Tier 2 bank bonds, particularly investment-grade bonds issued by strong global banks.
- SGD non-financial corporate bonds: Quality issuers, with the 3–5 year tenor being the sweet spot, where the yield pickup is most attractive.
Chart 3: SGS Yield curve
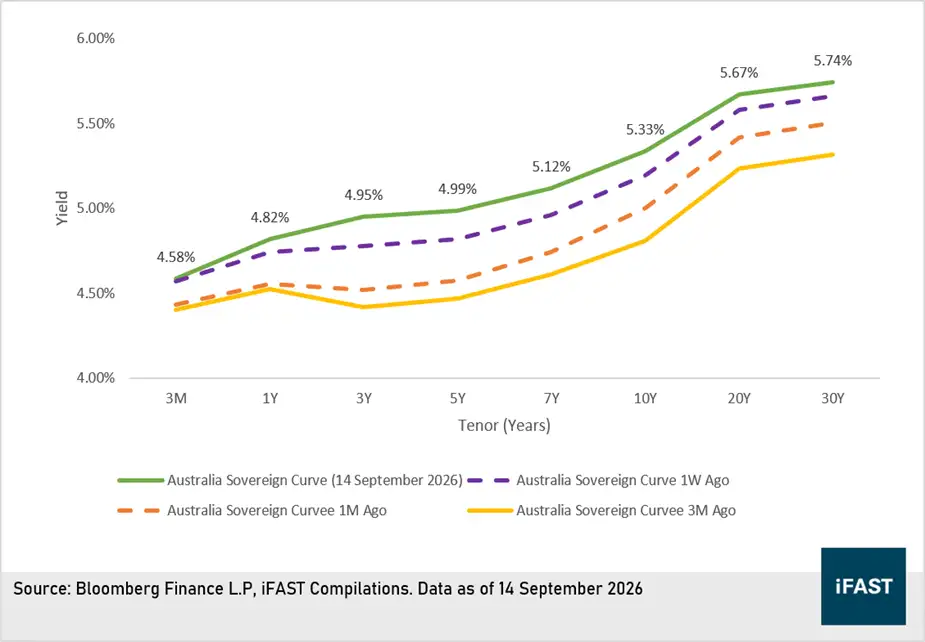
Our view on AGS:
1) July headline CPI further eased to 3.5% y-o-y (from 3.8% in June), however trimmed mean inflation remained sticky at 3.6% y-o-y, keeping RBA on their toes.
2) While we still believe RBA is near its end of tightening cycle, the odds of having one additional hike have increased, as the complication in US-Iran has pushed crude oil prices back to > USD100 territory, on top of the need to dampen core inflation.
3) We reiterate our preference for High-Quality Bonds and Barbell Strategy: We continue to favour barbell strategy, preferring both short (around 1-year) and longer tenors (7 to 10-years) of the yield curve.
Chart 4: AGS Yield curve
Some of the Credit Announcement by RAM & MARC (as of 31 August 2026)
RAM
1) Affirms KIP REIT Capital’s 2024-Issue 4 MTN rating
2) Assigns AAA rating to OCBC Al-Amin; affirms OCBC Malaysia’s AAA rating
3) Affirms Pelaburan Hartanah’s AAA rating
4) Assigns AA1/Stable/P1 corporate credit ratings to Sunway Berhad
5) Upgrades Sunway REIT’s CCR to AA1/Stable; related debt issue ratings also upgraded
6) Assigns AAA/P1 ratings to Suria Capital Holdings Berhad
7) Affirms AAA(bg)/Stable rating on West Coast Expressway’s guaranteed sukuk
https://www.ram.com.my/news-events/?tab=list-ratingannouncement
MARC
1) affirms ratings on Eco World’s Sukuk Wakalah and Perpetual Sukuk Programmes
2) MARC Ratings affirms George Kent’s ratings
3) affirms AAAIS(cg)/MARC-1IS(cg) ratings on F&N Capital’s IMTN/ICP Programmes
4) affirms AAAIS rating on TNB Northern’s sukuk
5) upgrades SHC Capital’s rating to AAIS
6) affirms ratings on S P Setia’s issuances
7) affirms Bank Muamalat’s ratings
8) revises MHB’s rating outlook to positive
https://www.marc.com.my/insights/rating-announcements/











