Olam International Limited (“Olam”), a leading food, agri-business and agriculture commodity trader, is launching a new SGD bond at the initial price guidance (“IPG”) of 4.25%. The senior unsecured note matures in 5.5 years and pays a semi-annual coupon to bondholders.
The new bond is issued under Olam’s USD 5 billion Euro Medium Term Note Program dated 5 May 20. Proceeds of the bond offering will be used for general corporate purposes, including the refinancing of existing short-term borrowings and funding capital expenditures.
About Olam
Listed on the Singapore exchange since 2005, Olam was established in 1989 and incorporated in Singapore in 1995. Since then, the group has expanded its operations to over 60 countries serving over 25,200 customers worldwide through its network of an estimated five million farmers.
Since the start of this year, Olam has re-organized its businesses into two principal groups — Olam Food Ingredients (“OFI”) and Olam Global Agri (“OGA”). These entities are held by the parent Olam International Limited, which acts as the steward and accelerator of the company’s two new growth engines.
OFI manages the portfolios of Cocoa, Coffee, Edible Nuts, Spices and Dairy. The division also provides sustainable, natural, value-added food products and ingredients for health-conscious consumers.
On the other hand, OGA is positioned in the high-growth Asian and African countries supplying food, feed and fibre to customers. Some of the products within the OGA portfolio include grains, animal feed & protein, edible oils, rice, cotton and commodity financial services.
Due to the increasing demand for protein-based diets, Olam will endeavor to grow its packaged foods and Olam Palm Gabon businesses to its fullest potential, while divesting away segments that are not identified in its 2019-2024 Strategic Plan — Sugar and Sweeteners, Wood Products, Rubber and Fertilizer.
As at 1 Apr 20, Temasek Holdings held a 53.4% interest in the company, while Mitsubishi Corporation had a 17.4% stake in the group.
Recent performance
In the six months ended 30 Jun 20 (“1H20”), group revenue increased by 7.1% to nearly S$17.1 billion from S$15.9 billion in the corresponding six-month period a year ago. Share of results from joint ventures and associates jumped from S$23.1m to S$104.8m and Olam recorded a net profit of S$295.4m during 1H20, up 42.2% from S$207.7m in 1H19. According to the company, group sales volume increased 5.0% YoY to 20.1 million metric tonnes, driven mostly by trading volume growth at OGA.
Group EBIT, or earnings before interest and taxes, dropped by 18.8% YoY to S$423.7m due to lower contributions from the Almonds, Hazelnuts and Cocoa segments. However, EBIT from the OGA sub-group grew 55.4% YoY due to higher contributions from the Food & Feed segment, particularly the Processing and Value-added sub-segment.
In spite of delivering higher revenue and profit growth, operating cash flow before reinvestment in working capital dropped from S$770.0m in 1H19 to S$683.9m. Net cash flow generated from operating activities fell from S$1.2 billion to S$934.6m during the same period. Free cash flow to equity, following Olam’s disclosures, were positive at S$826.9m. Meanwhile, net cash flow from financing activities surged from S$355.5m in 1H19 to S$1.91 billion in 1H20, and as a result, cash and short-term fixed deposits jumped to S$5.92 billion (31 Dec 19: S$3.18 billion).
The amount of cash and deposits falls short of the amount of short-term borrowings of S$9.0 billion. But Olam may divest part of its S$6.8 billion of inventory (or S$5.4 billion, consisting of inventories that are liquid, hedged and/or sold forward) to meet debt repayments. Earlier today, the group also announced a medium-term JPY 38.85 billion samurai loan facility, which it may use to pay down debt. Furthermore, there are S$7.24 billion of unutilized bank lines available to the commodities trader. Total borrowings added to S$15.1 billion as at end-June, while Olam has access to S$19.9 billion of available liquidity.
Net gearing, defined as the ratio of net debt (gross debt less cash) to equity (before fair value adjustment reserves), was 1.29x as at 1H20, down from 1.38x in 2H19, and at nearly the same level of 1.28x in 1H19. On the other hand, Olam’s adjusted net gearing* has been climbing gradually from 0.26x in 1H19 to 0.34x in 1H20.
Bond valuation
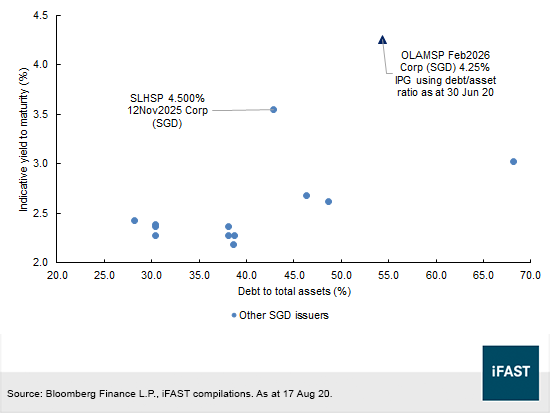
At the IPG of 4.25%, we think OLAM’s new SGD bond due February 2026 is attractively priced among SGD notes of similar maturities (Figure 1). Comparing the credits using the issuers’ debt-to-total asset ratio, Olam’s new senior bond provides relatively high potential return within the space.
Looking across different sectors, the SLHSP 4.500% 12Nov2025 Corp (SGD) has an indicative yield to maturity of 3.54%. SLHSP, or Shangri-La Hotel Ltd, operates in the hotel industry, which has different operating and credit characteristics from agribusinesses, and faces a more challenging operating environment amidst the current health crisis.
Figure 1: Relative valuation among notes of similar maturities
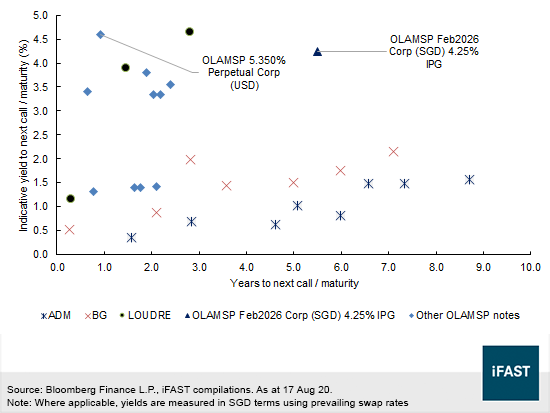
In the context of its industry peers, the OLAMSP 4.25% (IPG) ‘26s are attractively priced, with the highest yield among credits maturing within 5.5 years. At the shorter end of the curve, we prefer the OLAMSP 5.350% Perpetual Corp (USD) with its yield to next call of 4.60%. We would prefer Olam’s bonds over those of Louis Dreyfus Company (LOUDRE) as the latter is a private family-owned business, with less frequent and limited financial disclosures. Archer Daniels Midland Company (ADM) and Bunge Limited (BG) have stronger credit profiles than Olam and this is reflected in their lower bond yields.
Figure 2: Relative valuation among peer issuers of the same industry
*measured as net gearing adjusted for readily marketable inventories that are liquid, hedged and/or sold forward, operating as near-cash assets on the balance sheet, and secured receivables that are supported by letters of credit or documents through banks.
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) has a principal position in OLAMSP 6.000% 25Oct2022 Corp (SGD). The analyst who produced this report holds a NIL position in the abovementioned securities.