


OUE CT Treasury Pte Ltd, a wholly-owned subsidiary of OUE Commercial Real Estate Investment Trust (“OUE C-REIT”), is launching a five-year senior unsecured bond under its recently established S$2 billion multicurrency debt issuance program dated 20 Mar 20, at the final price guidance (“FPG”) of 4%. We understand that net proceeds of the bond offering will be used to refinance existing borrowings, fund buybacks or redemptions of securities, general corporate funding or other working capital purposes.
We recently dialed in to a conference call to find out more details about OUE C-REIT’s operating performance and the new issue. In this report, we highlight some key credit considerations and our pricing views.
About OUE Commercial REIT
OUE C-REIT is a diversified REIT with retail, hospitality and office real estate assets in its portfolio. The REIT has more than 2 million square feet (“sq ft”) of net lettable commercial space and 1,640 hotel rooms. In the office sector, OUE C-REIT owns three Grade A office properties in Singapore’s central business district – OUE Bayfront, One Raffles Place and OUE Downtown – and one office tower, Lippo Plaza, in Shanghai’s Huangpu downtown area. The aggregate valuation of the portfolio was S$6.8 billion as at 31 Dec 19.
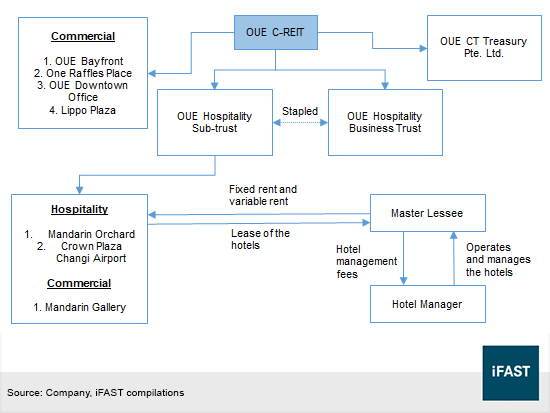
In September last year, OUE C-REIT completed its merger with OUE Hospitality Trust, a stapled group made up of OUE Hospitality Sub-Trust and OUE Hospitality Business Trust (Figure 1). With the merger in effect, the investment mandate of the trust has broadened to include the hospitality sector.
OUE C-REIT now owns the 1,077-room Mandarin Orchard Singapore (that will be rebranded to Hilton Singapore Orchard) and 563-room Crown Plaza Changi Airport in its portfolio. The REIT also has exposure to retail real estate through Mandarin Gallery, a shopping mall inside Mandarin Orchard Singapore.
As displayed in the corporate structure, the hotels are held through OUE Hospitality Sub-Trust and leased to master lessees through master lease agreements. Hotel managers are contracted and appointed by OUE Hospitality Sub-Trust to operate and run the hospitality assets.
Figure 1: REIT structure
Sponsor support
The master lease agreements are beneficial to OUE C-REIT as they provide S$67.5m of minimum rental per annum. OUE Limited (“”OUE”) is the master lessee for Mandarin Orchard Singapore, while OUE Airport Hotel Pte Ltd, a wholly owned subsidiary of OUE, is the master lessee for Crown Plaza Changi Airport.
OUE also provides income support for OUE Downtown Office up to 2023, or when S$60m is fully drawn down. Those long-term (15-year) master lease agreements and income support from OUE are credit positive for OUE C-REIT as they offer a dependable and extended source of income for the trust.
OUE Limited is also the sponsor of OUE C-REIT, and controls 47.7% interest in the REIT. OUE is a prominent real estate owner and developer with a large portfolio located in prime locations in Asia and the US. Owned primarily by Indonesia's billionaire Riady family, the group is listed on the Singapore stock exchange with a market capitalization of S$1.0 billion as of this writing. Readers may refer to “OUE Limited: Credit Update (21 May 20)” for an up-to-date view of OUE.
Financials and liquidity discussion
In the three months ending 31 Mar 20, OUE C-REIT increased revenue by 40.5% year-on-year to S$77.7m. This was broadly due to the inclusion of incomes from Mandarin Gallery, Crowne Plaza Changi Airport and Mandarin Orchard Singapore. Interest cost jumped 54.8% YoY to S$24.1m as the trust drew down on its loans for the merger. Net profit after tax was S$32.9m, up 33.4% from S$24.7m a year ago.
Compared to other Singapore commercial trusts, OUE C-REIT is a mid-sized REIT in terms of income (Table 1). With S$62.1m of property income recorded in the first quarter, OUE C-REIT is comparatively smaller than CapitaLand Commercial Trust (“CCT”), Mapletree Commercial Trust (“MCT”) and Suntec REIT, with respective incomes of S$113.4m, S$98.6m and S$117.2m. Other REITs such as Keppel REIT (“KREITS”) and Lendlease Global Commercial REIT (“LL C-Trust”) generated incomes of ~S$30.3m and S$32.8m respectively.
Table 1: Quarterly income of various office REITs
|
REIT |
Quarterly income (S$ m) |
Quarter ending |
Underlying Properties |
Location |
|
CCT |
103.7 |
31 Mar 20 |
Capital Tower, Asia Square Tower 2, CapitaGreen, Six Battery Road, Raffles City Singapore, 21 Collyer Quay, Bugis Village, One George Street, Raffles City Singapore |
Singapore |
|
9.7 |
31 Mar 20 |
Gallileo, Main Airport Center |
Germany |
|
|
MCT |
98.6 |
31 Mar 20 |
VivoCity, Mapletree Business City I, Mapletree Business City II, PSA Building, Mapletree Anson and Bank of America Merill Lynch HarbourFront |
Singapore |
|
Suntec REIT |
101.7 |
31 Dec 19 |
Suntec City retail, office and convention centre, One Raffles Quay, MBFC Towers 1&2, Marina Bay Link Mall |
Singapore |
|
15.5 |
31 Dec 19 |
177 Pacific Highway, Southgate office and retail, 55 Currie Street |
Australia |
|
|
OUE C-REIT |
57.0 |
31 Mar 20 |
OUE Bayfront, One Raffles Place, OUE Downtown Office, Mandarin Gallery, Mandarin Orchard Singapore, Crowne Plaza Changi Airport |
Singapore |
|
5.1 |
31 Mar 20 |
Lippo Plaza |
China |
|
|
KREITS |
22.2 |
31 Mar 20 |
Ocean Financial Centre, Marina Bay Financial Centre Towers, One Raffles Quay |
Singapore |
|
6.3 |
31 Mar 20 |
8 Chifley Square, 8 Exhibition Street, 275 George Street, David Malcolm Justice Centre |
Australia |
|
|
1.8 |
31 Mar 20 |
T Tower |
South Korea |
|
|
LL C-Trust |
21.6 |
31 Mar 20 |
313@Somerset |
Singapore |
|
11.2 |
31 Mar 20 |
Sky Complex |
Italy |
|
|
Source: Company filings, iFAST estimates |
||||
Trends in office rentals have not been favorable amidst the recent economic uncertainty. Estimates from CBRE showed that core CBD Grade A Singapore occupancy rates dropped 1.5 percentage points QoQ in 1Q20 to 97.6%. Grade A office rents declined 0.4% QoQ to S$11.5 per sq ft. Even though there is a limited supply of office space in the medium term, occupancy and rental rates could decrease further because of the weak economic backdrop.
The weak backdrop in office rentals is also prevalent in China. A strong office supply pipeline in Shanghai CBD caused rental rates to drop 4.2% QoQ to RMB9.7 per square meter. Colliers International expects the supply outlook in Shanghai to peak in 2021, meaning that the performance of Lippo Plaza could remain subdued for the remainder of 2020.
Cash flows however have remained steady in spite of the property and macroeconomic headwinds. Net cash from operating activities were S$74.3m in 1Q20, up from S$50.4m in 1Q19. Taking into account changes in cash flows from investing and financing activities, cash and cash equivalents dropped slightly to S$56.1m by the end of March from S$59.4m in 4Q19.
Trust borrowings were unchanged at S$2,695m at the end of 1Q20 from 4Q19. Secured borrowings added to S$1.6 billion at the end of the quarter, which comprised ~58% of total debt. Collaterals underlying the secure debt included S$3,508m of investment properties, rights, titles, benefits related to the sale and tenancy agreements and receivables of certain properties.
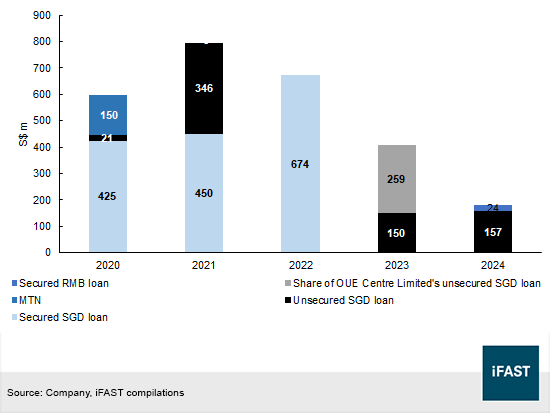
OUE C-REIT’s cash position looks tight against its S$596m of debt due in 2020 (Figure 2), but there are a number of financing options available to the trust. For example, the trust may divest investment properties, refinance its S$425m secured SGD loan or draw down on its ~S$102m undrawn credit facilities. Moreover, the REIT has debt headroom of approximately S$570m and S$1.3 billion before it hits regulatory limits of 45% and 50% respectively.
Figure 2: Debt maturity profile
Peer credit comparison
As a commercial and hospitality player, OUE C-REIT competes with other property owners and hoteliers for tenants and hotel guests. Broadly speaking, the success of each property hinges on its ability to draw customers. Tenants and tourists would likely be attracted to new facilities, reasonable room reservation or rental rates, good customer service quality and brand recognition. If competing properties are more successful in attracting and retaining tenants or hotel guests, then income from underlying properties could fall and the financial condition of the trust would be affected.
OUE C-REIT’s ability to service interest expense is low compared to peers (Table 2). With an EBITDA-to-interest multiple of 2.2x, the trust had a weaker interest coverage ratio than CCT, MCT, Suntec REIT and Lendlease commercial trust. Interest coverage ratio as reported by the trust improved to 2.9x. Looking ahead, we think OUE-CREIT’s EBITDA may remain low in the near term as the weakness in hospitality and in the Shanghai office leasing space may not pick up soon.
OUE C-REIT’s gearing – measured by the percentage of total debt to total assets – is the highest among peers. The percentage of debt at 39% tops the table, but still treads below the regulatory thresholds. Another measure of gearing, defined as net debt over EBITDA, is the second highest within the sector. This was caused by a low EBITDA, which dropped from ~S$70.1m in 4Q19 to ~S$62.1m in 1Q20.
An indicator of liquidity, or cash over short-term borrowings, shows that OUE C-REIT is in a tight liquidity situation, but that will improve once the trust rolls over the S$425 of SGD secured loan. KREITS and CCT have better liquidity with higher cash-to-short-term debt ratios of 99.2% and 75.1% respectively.
Table 2: Credit metrics among Singapore office REITs
|
|
Cash / short-term borrowings |
EBITDA / interest expense |
Total debt / total assets |
Net debt / annualized EBITDA |
|
CCT |
75.1% |
6.2x |
27.8% |
6.6x |
|
MCT |
41.2% |
4.1x |
33.4% |
8.2x |
|
Suntec REIT* |
26.7% |
4.9x |
36.2% |
6.5x |
|
OUE C-REIT |
9.4% |
2.2x |
39.0% |
10.6x |
|
KREITS |
99.2% |
2.1x |
30.8% |
10.9x |
|
LL C-Trust |
N.M |
6.0x |
34.7% |
7.7x |
|
Source: Company filings, iFAST estimates. *Figures for Suntec REIT were based on the quarter ending 31 Dec 19. |
||||
Bond valuation
With a 4% yield to maturity, the new senior note of OUE C-REIT provides the highest yield to maturity (“YTM”) for SGD bonds of similar or shorter maturity issued by commercial REITs (Figure 3). We think it is fairly priced relative to bonds of the OUE group, given that the OUESP 3.550% 10May2023 Corp (SGD) has a YTM of 3.7% with 2.9 years to maturity. The latter bond is issued by OUE Treasury Pte Ltd (“OUESP”), a wholly-owned subsidiary of OUE.
Figure 3: Relative valuation
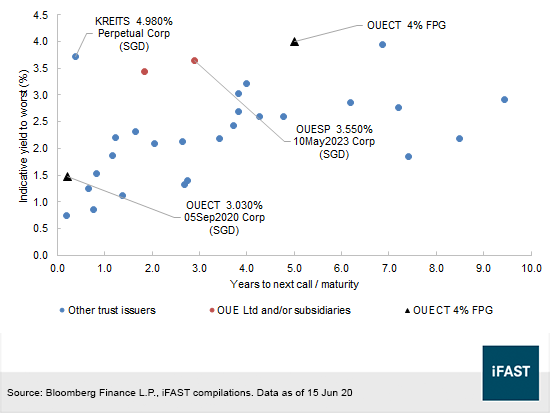
The KREITS 4.980% Perpetual Corp (SGD) may have a higher yield and the issuer has a stronger credit quality than OUE C-REIT. Current bid prices at 95 for the KREITS 4.98% perps suggest that the market is uncertain about whether Keppel REIT will call the perps in November. But we think a redemption at first call is likely given that the trust has access to a sizable amount of credit facility. OUE C-REIT, on the other hand, has a weaker credit outlook as its credit profile is constrained by the refinancing wall in 2020 and 2021.
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.









