Two weeks earlier, Oxley Holdings Limited (“Oxley”) announced a proposed issuance of convertible notes and possible issuance of non-listed warrants. Last week, Oxley also informed the exchange that the company purchased S$ 51.4m of its outstanding notes.
More specifically, the developer purchased USD 38,825,000 of the OHLSP 6.375% 21Apr2021 Corp (USD) and S$ 1,250,000 of the OHLSP 6.500% 28Feb2023 Corp (SGD). These notes were issued by Oxley MTN Pte. Ltd., under the USD 1 billion Euro Medium Term Note Programme that was first established on 17 Apr 17.
Consequently, the market value of the company’s quoted investments will increase from S$25.8m to S$77.3m. The bond purchases may have also lowered Oxley’s gearing and interest expenses.
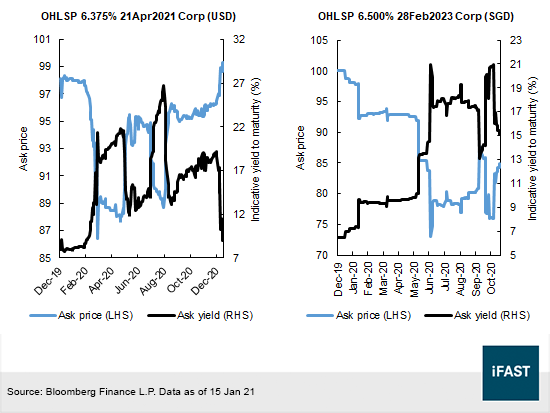
Indicative yields of the company’s bonds have dropped since November. Possibly in tandem with the group’s bond purchases, the ask prices of the OHLSP 6.500% 28Feb2023 Corp (SGD) have increased from 79.3 on 5 Nov 20 to 84.7 on 15 Jan 21. In the same period, the ask price of the OHLSP 6.375% ‘21s increased from 95.4 to 99.3 (Figure 1).
Figure 1: Indicative prices and yields to maturity of the Oxley bonds
About Oxley
Headquartered in Singapore, Oxley is an international property developer that has launched projects in nine geographical markets, including the UK, Cyprus, Ireland, and China. Since its incorporation in 2010, the company has completed 33 property development projects and launched 48 property development projects across these countries. Some of its flagship projects include the Royal Wharf in London, The Peak in Cambodia and Dublin Landings in Ireland. Pindan Group Pty Ltd, an integrated property firm in Australia is a wholly-owned subsidiary of the firm. In addition, Oxley owns an approximate 10% stake in Aspen (Group) Holdings Limited, a listed entity on the Singapore Catalist exchange.
Investment from the Dignari Capital Partners funds
Oxley is proposing to issue up to USD 80m of convertible notes to Dragons 120 Limited, a subsidiary of the Dignari Capital Partners (“DCP”) Asia Credit Fund III, L.P. and DCP Asia Co-Investment Fund I, L.P.
The notes are secured against certain collateral and pay a coupon of 4.5% to the investor, who has the option of converting the notes into shares at an initial conversion price of S$0.25 per share. According to the terms of issuance, the notes will mature in 24 months after the first tranche of USD 72m has been issued. If required, Oxley may request to extend the maturity of the notes by another 12 months.
Convertible noteholders may sell their holdings back to the issuer on certain occasions such as in a Change of Control Event, a cessation of trading in the company’s shares, or in a takeover situation. According to the developer, under the scenario where a maximum number of new shares have been issued, the net tangible assets of the company at FY2020 (the financial year ended 30 Jun 20) will expand from S$ 996.1m to S$ 1.09 billion. However, the conversion of the notes will have almost no impact on the group’s earnings.
Amendment of facility agreement
The investment from the DCP funds was not the only transaction on 6 Jan 21. Oxley also updated the terms of a facility agreement with Dragons 619 Limited (the “Lender”), who is an affiliate of Dragons 120 Limited.
As we understand, Oxley may draw down on a USD 100m facility from the Lender under a facility agreement dated 17 Sep 20. Interest on the facility may be paid in cash or issued warrants that may be exercised at a volume weighted price over the preceding 20 days, subjected to a floor of S$0.20 per share.
The company may choose the form of interest payment any time before 21 Apr 21, which coincides with the maturity date of the OHLSP 6.375% ‘21s. To put it succinctly, the setup of the loan facility increases the repayment likelihood of the 2021 bond.
Group financials and credit highlights
Our positive credit opinion on Oxley has not changed since the last report in September – see “Oxley Holdings Limited: Credit update 18 Sep 20”. The company will report results for the six months ended 31 Dec 20 (“1HFY21”) in February and we will soon follow up with another credit commentary.
In the second half of FY2020 (“2HFY20”), group revenue surged 299% YoY to S$ 638.9m, fueled by contributions from the Pindan Group subsidiary and higher sales from its projects in Singapore, Cambodia and the UK. The developer made a gross profit margin of 23.4% in 2HFY20 (2HFY19: 23.1%). In spite of achieving higher revenue and gross profit, Oxley reported a net loss of S$ 288.0m, mostly as a result of impairment and property revaluation losses.
Operating cash flows have improved since 1HFY19. Net cash flows from operating activities increased to S$ 125.9m in 2HFY20 on the delivery of UK residential units and progress billings on Singapore projects. Free cash flows, which take into account net expenditures on PPE and investment properties, swung from -S$ 108.4 in 2HFY19 to S$ 213.4m in 2HFY20. This was primarily because of the S$ 142.6m inflow connected to disposals of commercial properties at Dublin Landings in Ireland and 30 Raffles Place.
Non-current debt fell from S$ 2.24 billion in 2HFY19 to S$ 1.27 billion in 2HFY20. However, total short-term borrowings climbed from S$ 1.34 billion to S$ 1.75 billion over the same period. On a related note, the company classified S$ 520m of borrowings that are maturing in 2022 as a current liability, primarily due to a violation of loan covenant. However, Oxley obtained a waiver from lenders in September for the non-compliance of the covenant.
Excluding the S$ 520m of borrowings and the 2021 bond purchase, short term debt would have amounted to ~S$ 1.18 billion. At this juncture, we maintain the view that Oxley will be able to redeem its bonds upon maturity. Taking reference from the company’s latest guidance, we continue to believe that Oxley will meet the ~S$1.18 billion of current borrowings through development sale proceeds, asset divestitures and loan refinancing.
With the resumption of construction activity in various countries, we think that Oxley is on track to complete its property projects on time. The company’s potential liquidity sources include its recently established USD 100m loan facility; USD 80m convertible note issuance; ~S$ 238.1m of unrestricted cash; sale proceeds from Dublin Landings (S$ 111m), Royal Wharf (S$ 160m), The Peak (S$ 217m) and down payments of up to ~S$ 240.3m (our estimate) from the sale of remaining Singapore projects.
As mentioned in the FY2020 annual report, Oxley expects to sell the remaining of its Singapore development properties within 12 to 15 months. New home sales in Singapore have been resilient in the midst of a pandemic and the buoyant property market is good for real estate companies. Developers reportedly sold 57.2% more homes in December 2020 compared to the prior month. Sales were up 126.2% year-on-year, making it the highest record in eight years.
Our recommendation
The OHLSP bonds still provide good risk-reward opportunities considering that the firm has a number of liquidity sources to meet debt obligations. We like the OHLSP 5.700% 31Jan2022 Corp (SGD) and OHLSP 6.500% 28Feb2023 Corp (SGD) at their indicative yields to maturity of 11.88% and 15.11% respectively. Bonds along the OHLSP curve have the highest G-spreads among other comparable credits and would be attractively priced in our view (Figure 2).
Figure 2: Relative valuation among real estate bonds of Singapore domiciled issuers
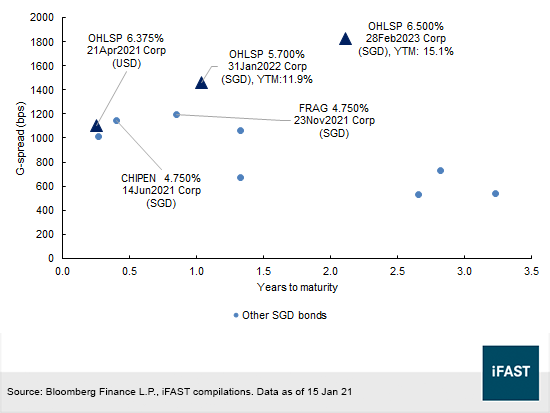
Among notes that are maturing in the near term, the G-spreads of the OHLSP 5.7% ‘22s exceed that of the FRAG 4.750% 23Nov2021 Corp (SGD) and CHIPEN 4.750% 14Jun2021 Corp (SGD). We do not cover the issuers FRAG and CHIPEN but the likelihood of redeeming the CHIPEN 4.75% ‘21s is high as the issuer recorded a sufficient amount of liquidity at the end of June 2020 (with S$ 369.6m of cash and S$ 240.9m of short term borrowings).
On the other hand, Fragrance Group Ltd may be facing a tighter refinancing situation with S$ 18.9m of cash equivalents and ~S$ 337.2m of financial dues. On 15 Jan 21, Fragrance Group informed the exchange that it had received AUD 51.6m in deposits from the sale of residential units at the Premier Tower in Melbourne, and there is a possibility that the eventual proceeds could be lower than the initial contracted sales amount of AUD 468.2m .
Either way, we would still prefer the OHLSP notes over the aforementioned credits as they provide a higher yield to investors. In the event of a funding shortfall, we believe that the developer may still divest its Singapore hotel at Stevens Road for liquidity. Oxley has a track record of ramping up leverage quickly to take advantage of market opportunities, and then de-gearing to pay down debt with sales proceeds. Investors who want exposure to the Singapore residential property market may consider the Oxley bonds.
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) has a principal position in OHLSP 6.375% 21Apr2021 Corp (USD). The analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!