The OHLSP 5.150% 18May2020 Corp (SGD) - Retail have matured and investors may be wondering if they should reinvest the proceeds into the other Oxley bonds. There are a number of good alternatives mentioned in our article – “Nobody knows what COVID-19 means for the future, but that shouldn’t change how you invest”. We also think that the OHLSP 6.375% 21Apr2021 Corp (USD) is attractively priced with a yield to maturity (“YTM”) that is higher than the longer-dated OHLSP 5.700% 31Jan2022 Corp (SGD).
In a filing to the Singapore Exchange earlier this week, Oxley updated that the company entered into an expression of interest for the sale of the retail and banking units at Chevron House. As a recap, Oxley is in the midst of selling Chevron House to Golden Compass (BVI) Limited, the closing of which is subject to (among other conditions) completion of asset enhancement works and the divestment of the retail and banking units. This development is credit positive for Oxley as it indicates that the firm is on track to complete the Chevron House deal by 30 Jun 20.
Latest financial results
Following the amendments to Rule 705(2) of the Listing Manual, Oxley has ceased quarterly reporting and will report FY20 earnings by 29 Aug 20. In the six months ended December 2019 (“1HFY20”), group revenue increased 13% YoY to S$594.0m, backed by sales improvements from development projects in Singapore and Dublin, as well as three-month revenue contribution from Pindan Group Pty Ltd, an Australian subsidiary that was consolidated since October.
Net profit, however, dropped to S$12.9m partly because of a 135% increase in administrative expenses. Higher consultancy fees in overseas projects and the consolidation of Pindan caused administrative costs to rise to S$22.6m.
Net cash flows from operating activities (“CFO”) remained negative at -S$87.1m in 1HFY20 (1HFY19: -S$347.8m). The drop in cash flows was due to changes in working capital as a result of reduction in trade and other payables in Singapore, Australia, the UK and Cambodia.
Our earlier assumptions
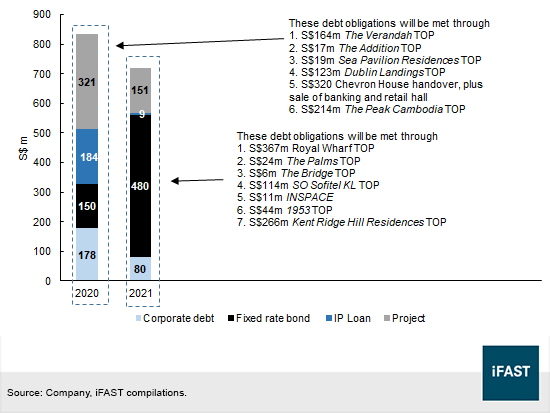
In our February article "Oxley launches new 3Y SGD bond at 6.75% IPG”, we laid out projections about how Oxley’s 2020 and 2021 bonds could be repaid with incoming cash flows (Figure 1). We assumed that the 2020 notes would be paid using cash proceeds from Singapore residential projects as they reach their TOP dates.
But as the coronavirus worsened, virus clusters were discovered in Singapore’s worker dormitories and construction activity had slowed. Oxley subsequently informed that there may be a possibility that the Singapore projects would be delayed.
Figure 1: Debt maturity schedule till 2021
Our revised projections
With the latest developments in mind, we now assume that the project debt (S$321m in 2020 and S$151m in 2021) and investment property loans will be rolled over or refinanced, as we continue to observe signs that Singapore lenders are supportive of corporate borrowings. Remaining financial obligations consisting of the USD 355m (S$480m) OHLSP 6.375% 21Apr2021 Corp (USD) and S$258m of corporate debt may be paid using cash receipts from the Chevron House deal (~S$295m), and completion of the Royal Wharf (S$367m), The Peak (S$214m) and Dublin Landings (S$123m) projects.
Overseas projects such as the Royal Wharf and Dublin Landings are projected to be completed before April 2021, according to the company’s recent status update. Barring unforeseen circumstances such as a worsening of the pandemic, we believe Oxley will complete the projects in time to meet debt maturities.
Sales progress
In the abovementioned status update, Oxley mentioned that the company achieved its revenue targets for Singapore projects. Total attributable future billings were largely unchanged at around S$1.39 billion between February and April, possibly affected by circuit breaker measures (Table 1).
Table 1: Singapore project updates
|
|
Effective Stake (%) |
Total number of units |
Units sold |
Attributable future billings, Feb 2020 (S$ m) |
Attributable future billings, Apr 2020 (S$ m) |
|
The Verandah Residences |
100% |
170 |
169 |
163.6 |
149.6 |
|
Sea Pavilion Residences |
100% |
24 |
24 |
18.5 |
15.6 |
|
Sixteen35 Residences |
100% |
60 |
59 |
38.0 |
34.3 |
|
Riverfront Residences |
35% |
1,478 |
1,273 |
305.3 |
314.7 |
|
Affinity at Serangoon |
40% |
1,057 |
714 |
235.2 |
238.9 |
|
Kent Ridge Hill Residences |
100% |
548 |
308 |
265.7 |
279.5 |
|
Mayfair Gardens |
100% |
215 |
166 |
204.8 |
202.7 |
|
Mayfair Modern |
100% |
171 |
68 |
82.2 |
92.3 |
|
The Addition |
100% |
26 |
26 |
16.5 |
14.7 |
|
1953 |
100% |
72 |
38 |
44.4 |
43.0 |
|
INSPACE |
49% |
84 |
13 |
10.5 |
9.6 |
|
Parkwood Residences |
100% |
18 |
- |
- |
- |
|
Total |
3,923 |
2,858 |
1,384.7 |
1,393.9 |
|
|
Source: Company, iFAST compilations |
|||||
Other sources of liquidity are available
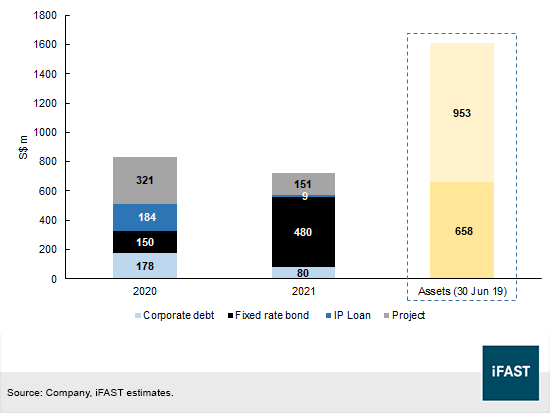
In the event of further delays in construction at the Dublin Landings and Royal Wharf projects, Oxley may still sell existing assets to meet repayment requirements. Last year, the group did attempt to sell the Novotel and Mercure hotels on Stevens Road that booked a carrying value of S$953m as at 30 Jun 19. The developer may also divest some of its freehold land valued at S$658m to tide over debt payments.
Figure 2: 2020-2021 debt and selected assets
Peer comparison
When compared to Perennial Real Estate Holdings Limited (“Perennial”) and Aspial Corporation Ltd (“Aspial”), Oxley registered the highest EBIT-to-interest multiple during 2019 (Table 2). Gearing, defined as debt over total assets, was high at 54% but remained lower than Aspial’s 63%. Aspial recorded the highest revenue-to-debt proportion but that may be driven by sales contributions from its jewellery business.
Overall, we think Oxley had the best credit performance among these three developers during 2019. Our recent reports on Aspial (“Aspial Corp: Credit Update 20 Jan 2020”) and Perennial (“Perennial Real Estate: Credit Update 27 Mar 20”) explain more about the companies and provide our up-to-date views on these issuers.
Table 2: 2019 peer comparison
|
Issuer |
Revenue / Debt |
2019 EBIT / Interest |
Debt / Total Assets |
Debt / Total Capital |
|
Perennial |
4.2% |
1.1x |
39% |
44% |
|
Aspial |
51% |
1.9x |
63% |
73% |
|
Oxley |
24% |
2.1x |
54% |
68% |
|
Source: Company, iFAST estimates. |
||||
Mispriced opportunity?
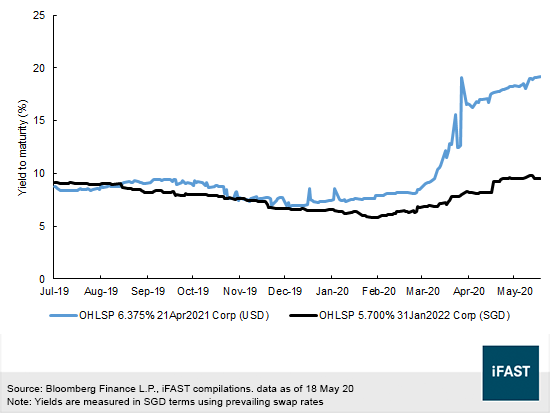
Yields of the OHLSP 5.700% 31Jan2022 Corp (SGD) and OHLSP 6.375% ‘21s started diverging in February and continued to widen even though credit spreads in general have tightened for many issuers. There were also other pockets of opportunities in March when YTMs of USD- and SGD-denominated notes of the same issuer, for instance, LOGPH 6.125% 16Apr2021 Corp (SGD) and LOGPH 6.875% 24Apr2021 Corp (USD); and F 4.125% 20Jun2024 Corp (SGD) and F 4.250% 20Sep2022 Corp (USD); deviated from each other.
Yields of the aforementioned bonds of Ford Motor and Logan Property have since tightened, and yield premiums on the USD notes diminished. However, this does not seem to be the case for the Oxley 2021 and 2022 bonds as their yields continue to display an upward and diverging trend (Figure 3).
We view this as an opportunity for investors as the OHLSP 6.375% ‘21s are offering an outsized YTM of around 19.1% if swapped to SGD, 964 bps higher than the OHL 5.7% ‘22s. In light of our liquidity projections for the company, we recommend investors to buy Oxley’s USD notes due 2021 to take advantage of the current mispricing.
Figure 3: Oxley’s 2021 and 2022 notes
Declaration:
For specific disclosure, at the time of publication of this report, iFAST Financial Pte Ltd (via its connected and associated entities) has a principal position in OHLSP 6.375% 21Apr2021 Corp (USD). The analyst who produced this report holds a NIL position in the abovementioned securities.