SATS Ltd. (SATS) has announced a 5-year senior unsecured USD bond, issued by SATS Treasury Pte. Ltd., but guaranteed by SATS. The bond’s initial price guidance (IPG) is T+120bps (coupons paid semi-annually). It is available only for accredited and institutional investors.
SATS was recently assigned a first-time A3 (Stable) issuer rating by Moody’s, while the new bond issuance is also expected to have an A3 rating by Moody’s. The bond will be issued under SATS’s existing USD 3b Guaranteed Multicurrency Debt Issuance Programme. Proceeds from this new issuance will be used for the refinancing of existing borrowings.
About SATS
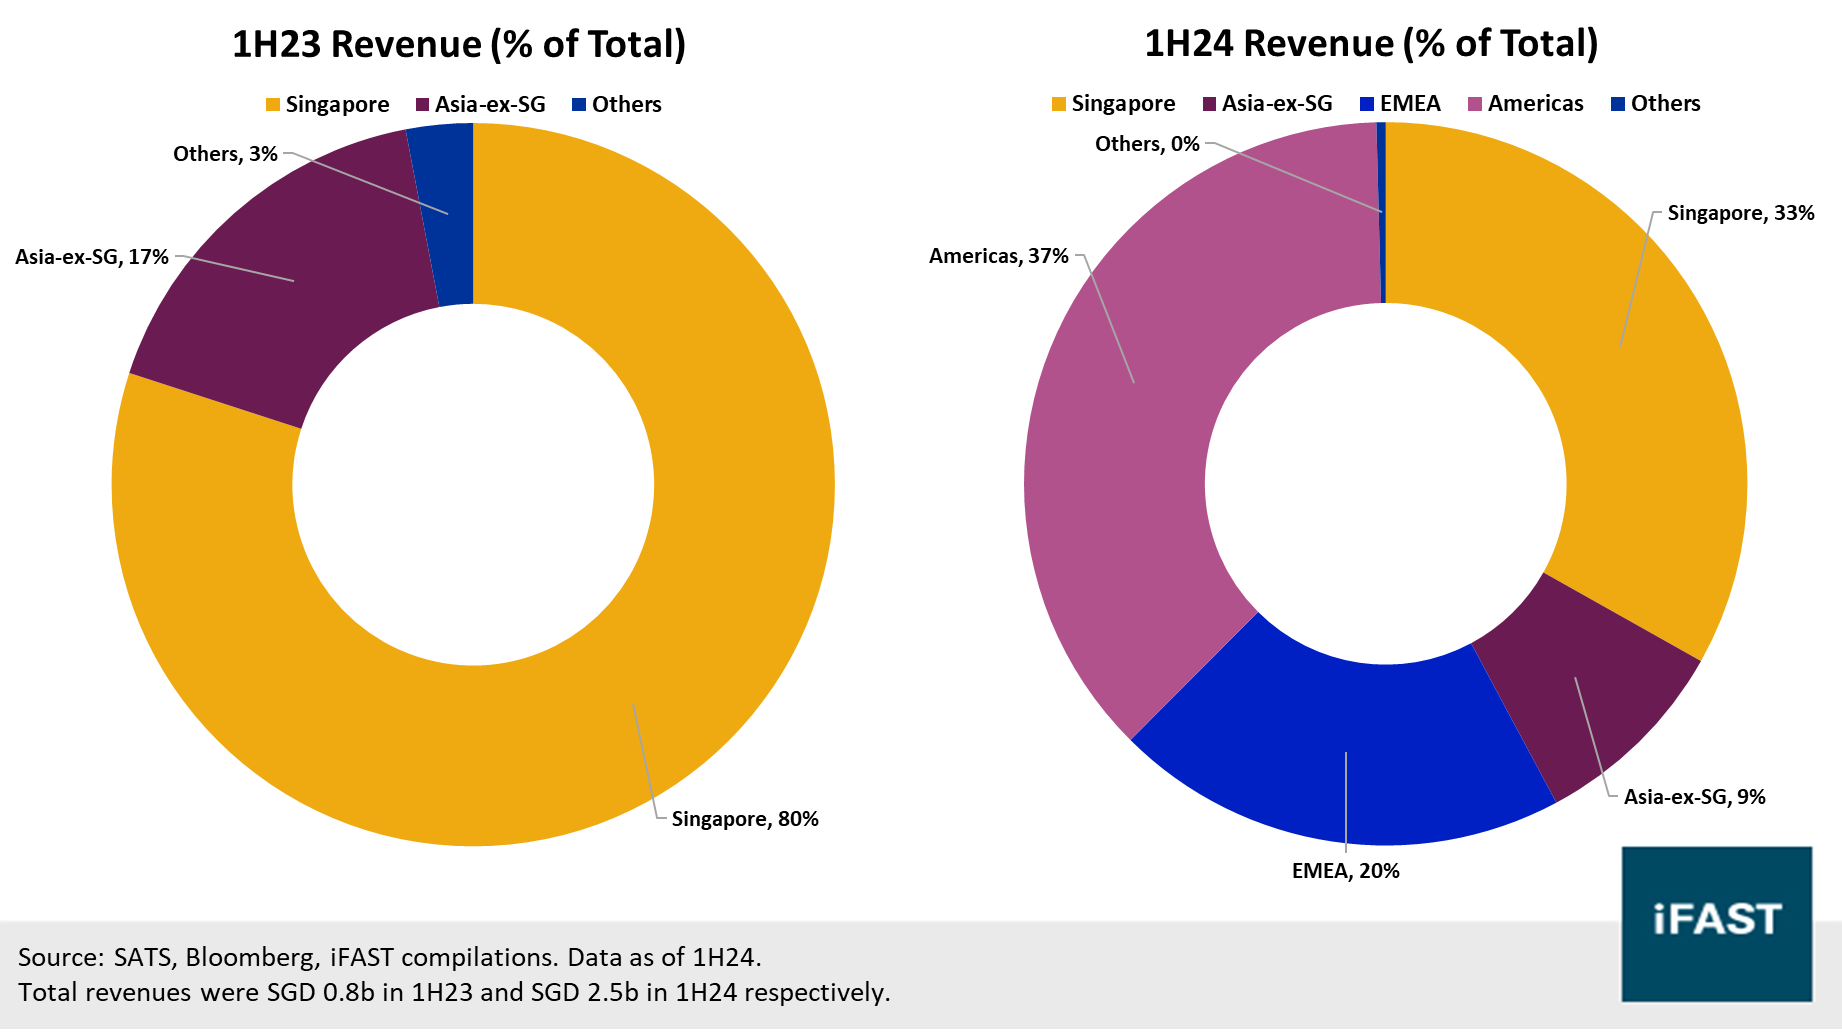
SATS is a leading provider of food solutions and gateway services, operating in over 210 locations and 27 countries. Recently, it has made steps to diversify its revenue sources beyond Asia and Singapore, including its recent acquisition of Worldwide Flight Services (WFS) in 2023, and now makes a majority of its revenues (as of 1H24) outside of Asia (Chart 1).
Chart 1: Geographical breakdown of SATS's revenues
Financial highlights
We first compare SATS’s performance in the half year ended 30 September 2023 (1H24) relative to 1H23 (Table 1). Revenues increased by +208% from SGD 0.8b to SGD 2.5b and operating profits swung back in the green from SGD -42m to SGD 76m. Estimated EBITDA (including share of JVs) also saw a large increase from SGD 59m to SGD 397m, suggesting a healthy increase in EBITDA margins from 7.4% to 16.0% (1H24). Nonetheless, SATS continued to see net losses of SGD -9m in 1H24 (1H23: SGD -41m), hurt by higher interest (debt-servicing) costs. Overall, annual improvements in revenues and operating profits in 1H24 were broadly helped by the acquisition of WFS (completed in early April 2023), though we note the overall net losses for SATS in 1H24.
We next compare SATS’s performance in 2Q24 relative to 1Q24 as it may be less ‘distorted’ from the impacts of the WFS acquisition (Table 2). Revenues increased by a smaller amount (+7%) from SGD 1.2b to SGD 1.3b (2Q24), while EBITDA also climbed by +21% from SGD 180m to SGD 218m (2Q24), with implied EBITDA margins of 15.0% and 17.0% respectively.
In terms of SATS’s credit profile, we think the acquisition of WFS has led to the worsening of some key ratios (Table 2). This includes ratios like total debt to total assets, net gearing, net debt to EBITDA, as well as EBITDA coverage, generally due to the large increase in debt (total debt and net debt) following this acquisition. However, we do not expect these ratios to see significant deterioration ahead (discussed in the Outlook section below). Meanwhile, SATS was also able to maintain a fairly healthy cash position of SGD 516m.
Table 1: Revenue and earnings metrics of SATS
| Revenue & Earnings Metrics | 1H23 | 1H24 | YoY Change (%) |
| Revenue (SGD m) | 805 | 2,481 | 208% |
| Operating Income (SGD m) | -42 | 76 | N.M. |
| Estimated EBITDA (SGD m) | 59 | 397 | 569% |
| Estimated EBITDA Margins (%) | 7.4% | 16.0% | +8.6pp |
| Net Income / Losses (SGD m) | -41 | -9 | -78% |
| Source: SATS, Bloomberg, iFAST compilations. EBITDA includes share of JVs. Data as of 1H24. | |||
Table 2: Credit metrics of SATS
| Credit Metrics | 1H23 | 2H23 | 1H24 |
| Total Debt (SGD m) [A]* | 854.2 | 1,478.4 | 4,173.3 |
| Total Assets (SGD m) [B] | 3,330.0 | 4,673.7 | 8,457.5 |
| Total Debt / Total Assets (%) [A/B] | 26% | 32% | 49% |
| Cash & CE (SGD m) [C] | 689.3 | 374.4 | 515.9 |
| Net Debt (SGD m) [D = A - C] | 164.9 | 1,104.0 | 3,657.4 |
| Total Equity (SGD m) [E] | 1,779.6 | 2,514.8 | 2,519.8 |
| Gearing, or Net Debt / Equity (%) [D/E] | 9% | 44% | 145% |
| LTM EBITDA (SGD m) (F) | 87.8 | 173.2 | 510.9 |
| Net Debt / LTM EBITDA (X) [D/F] | 1.9 | 6.4 | 7.2 |
| LTM Net Interest Expense (SGD m) (G) | -14.4 | -8.7 | -115.1 |
| LTM EBITDA Coverage Ratio (X) [F/G]** | 6.1 | 19.9 | 4.4 |
| Source: SATS, Bloomberg, iFAST compilations. Data
as of 1H24. *Total debt includes MTN, loans, and lease liabilities. **Figures have been turned from negative to positive for readability. |
|||
Outlook, and thoughts on new issue
Looking ahead, the Group’s profitability could also remain supported by an ongoing travel recovery, with management pointing out that several operational statistics (e.g. passenger traffic) remain below pre-pandemic levels. The recent acquisition of WFS could also boost SATS’s long-term growth potential by gaining a larger share in air cargo handling. We think the initial mild growth witnessed between 1Q24 and 2Q24 is an encouraging sign that SATS could potentially be on the right track to profitability.
We also think that SATS’s credit profile should remain stable moving ahead for the following reasons:
- The worsening of credit ratios highlighted above was primarily due to effects from the WFS acquisition, and we see a low probability of similarly large deals for SATS moving ahead (that could affect its credit ratios adversely).
- SATS’s management has highlighted its focus on stabilising the company and deleveraging – one measure they have done is to pause shareholder dividends for now until the Group returns to profitability.
- The assigning of an A3 issuer rating by Moody’s puts it well within investment-grade territory, which may allow SATS to tap debt markets more easily at a potentially lower cost.
- The presence of Temasek as its major shareholder may also be a benefit to SATS.
However, we also remind investors that there will be execution risks involved with this WFS acquisition (as with other large acquisitions), such as the realisation of synergies from both companies. While we think SATS’s outlook remains stable for now, we are keeping an eye on management updates (e.g. every quarter) for signs that the acquisition is truly reaping benefits for the Group.
On balance, given the likely stable outlook for SATS, we think this new issue is fairly priced. The IPG of T+120bps suggests a coupon/yield of about 5.09%, which gives it just a slight yield pickup of about 25bps over a comparable bond by Singapore Airlines also maturing in January 2029 (SIASP 3.375% 19Jan2029 Corp (USD)) (Table 3). We also note that the final price guidance (FPG) is likely to come in lower than the IPG, resulting in a lower coupon and yield compared to this estimate. Institutional and accredited investors who are willing to undertake such execution risks (with the WFS acquisition) can consider this bond.
Table 3: Comparison against peers
| Bond Name | Call / Maturity Date (Years to Call / Maturity) |
Ask Price | Yield to Call / Maturity (%) |
| SATSTP New Issue* | 23 Jan 2029 (5.0) |
100.000* | 5.09%* |
| SIASP 3.000% 20Jul2026 Corp (USD) |
20 Jun 2026 / 20 Jul
2026 (2.4 / 2.5) |
95.335 | 5.07% / 5.00% |
| SIASP 3.375% 19Jan2029 Corp (USD) |
19 Nov 2028 / 19 Jan 2029 (4.8 / 5.0) |
93.739 | 4.84% / 4.80% |
| Source: Bloomberg, Bondsupermart, iFAST
compilations. Data as of 15 Jan 2024. *Note: Not yet issued. Note that this is based on IPG – final price guidance (FPG) is likely to be lower than IPG. |
|||
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!