Starhill Global REIT (“SGREIT”) announced on 6 September 2021 that the company is launching a 7-year SGD, unsubordinated and unsecured notes at an initial price guidance (“IPG”) of 2.35% under its SGD 2b Multicurrency Debt Issuance Programme dated 3 January 2020.
About the unsubordinated and unsecured notes
The new SGREIT 7Y 2.35% IPG notes will be issued under the issuer’s SGD 2b Multicurrency Debt Issuance Programme (“MTN programme”). The new issue will be issued on 13 September 2021 and will mature on 13 September 2028.
The notes bear a Make-Whole call option in which the issuer may redeem all or some of the notes on any interest payment date prior to the maturity date at their Make-Whole Amount with interest accrued to the date fixed for redemption.
The use of proceeds of the notes will be used to refinance existing borrowings, meet capital expenditure requirements and/or for working capital purposes of SGREIT.
About Starhill Global REIT
Starhill Global REIT (“SGREIT”) is a Singapore-based retail and office real estate investment trust. SGREIT has 10 properties under its portfolio situated in Singapore, Australia, Malaysia, China and Japan. SGREIT is managed by YTL Starhill Global REIT Management Limited.
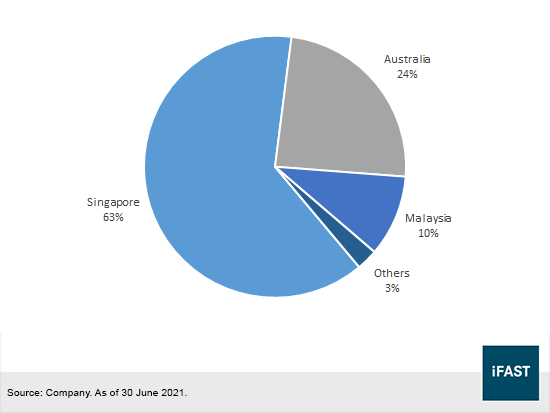
Portfolio properties include Wisma Atria and Ngee Ann City, both of which are situated in the prime shopping district in Singapore. Its Australian properties include Myer Centre in Adelaide, David Jones Building and Plaza Arcade that are located in Adelaide and Perth, respectively. The REIT also owns The Starhill (formerly known as Starhill Gallery) and Lot 10 Property in Kuala Lumpur, Malaysia, a retail property in Chengdu, China, and two properties in Tokyo, Japan.
Figure 1: FY 20/21 Revenue by Geography
Full Year Financial Results
Table 1: Financial Results of SGREIT
|
Year ended 30th June |
FY 18/19 |
FY 19/20 |
FY 20/21 |
Y-o-Y change |
|
Revenue |
206.2 |
180.8 |
181.3 |
0.3% |
|
Operating income before working capital changes |
138.9 |
120.1 |
123.5 |
2.8% |
|
Finance expenses |
38.7 |
39.9 |
41.4 |
3.9% |
|
Total return before tax |
69.1 |
-96.0 |
58.0 |
160.4% |
|
Total return after tax |
65.6 |
-97.4 |
56.5 |
158.0% |
|
Balance sheet |
||||
|
Cash and cash equivalents |
72.9 |
117.4 |
108.3 |
-7.8% |
|
Total Assets |
3,142.0 |
3,081.0 |
3,079.6 |
0.0% |
|
Short Term Debt |
127.8 |
162.0 |
- |
-100.0% |
|
Gross Debt |
1,132.1 |
1,218.0 |
1,105.4 |
-9.2% |
|
Net Debt |
1,059.2 |
1,100.5 |
997.1 |
-9.4% |
|
Total Equity |
1,930.0 |
1,769.5 |
1,890.1 |
6.8% |
|
Cash Flow statement |
||||
|
Net cash from operating activities |
134.0 |
102.8 |
142.2 |
38.3% |
|
Capital expenditure on investment properties, plant, property and equipment |
7.7 |
29.7 |
34.9 |
17.5% |
|
Borrowing costs paid |
37.8 |
39.1 |
44.3 |
13.3% |
|
Free Cash Flow estimate |
126.3 |
73.1 |
107.3 |
46.8% |
| Source: Company, iFAST estimates. As of 30 June 2021. | ||||
On 29 July 2021, SGREIT reported its full year financial results for the year ended 30 June 2021. Gross revenue for 2H FY 20/21 increased 10.5% year-over-year (“y-o-y”) to SGD 92.9m, bringing gross revenue for FY 20/21 to be SGD 181.3m, representing a 0.3% increase from FY 19/20.
Net Property Income (“NPI”) increased 20.2% to SGD 69.8m for 2H 20/21 and NPI for FY 20/21 totalled to SGD 134.7m, a 2.0% increase y-o-y. The increase in NPI is largely due to lower tenant rental assistance and a stronger appreciation of the Australian dollar. We expect rental assistance to taper off slowly as Singapore eases social distancing requirements, leading to higher projected NPI in the future. Gross revenues is expected to rise to close to pre-pandemic levels of around SGD 190m.
Gross revenue for Singapore properties, Wisma Atria and Ngee Ann City, fell by 0.5% in FY 20/21. Retail gross revenue for Wisma Atria fell by 12.1% to SGD 40.9m while retail gross revenue for Ngee Ann City increased by 7.4% to SGD 49.5m. The fall in gross revenue for Wisma Atria is largely due to lower rent and occupancy rates, as well as more rental assistance granted to tenants. However, retail occupancy rate for Singapore properties remained resilient at a healthy 98.6%.
We recently published a credit initiation on SGREIT and highlighted key considerations and risks investors may have to take note in investing in SGREIT, for investors who are interested they may read the credit initiation here.
Credit Profile of SGREIT
SGREIT has a prudent and well managed capital profile. Gross debt decreased from SGD 1,218.0m to SGD 1,105.4m. However, financial leverage for the company was nearly unchanged from FY 19/20 to FY 20/21, with Debt (including perpetual securities) to Total assets falling slightly from ~39.5% to ~39.1%. We feel that SGREIT’s capital management is favorable, given that it has reduced its leverage from the prior fiscal year and its gearing is lower than the MAS’s regulatory requirement of 50% for REITs.
Figure 2: Debt Maturity Profile of SGREIT
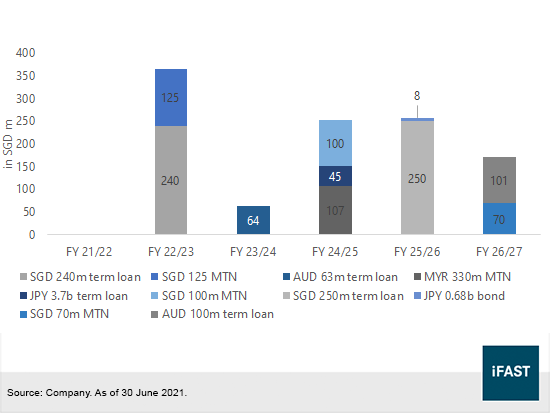
SGREIT has an average debt to maturity profile of 3.3 years and has managed to refinance all its expiring debt for FY 20/21 ahead of their expiry. There are no term debt maturities in the next 12 months for the company. SGREIT had drawn down on their 5-year SGD 250m unsecured term loan facilities in February 2021 to refinance the maturing SGD 100m medium term note and SGD 150m term loan in 2021.
SGREIT have sufficient liquidity in the short term to tide through the current economic backdrop. Net cash from operating activities increased from SGD 102.8m in FY 19/20 to SGD 142.2m in FY 20/21. This is an improvement from pre-COVID levels of SGD 134.0m in FY 18/19. Overall, we feel SGREIT still have sufficient and healthy liquidity considering it has no short term debts to refinance.
Relative Valuation
Figure 3: Relative valuation among SGD fixed rate notes of REIT issuers
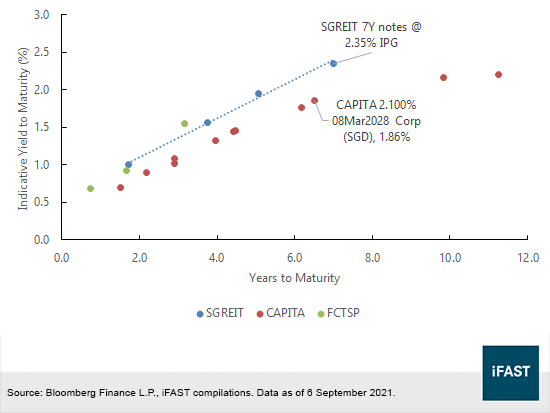
When priced with SGREIT’s existing fixed rate notes, we find the new issue to be fairly priced along its yield curve. When compared with other retail REITs such as Capitaland Integrated Commercial Trust (“CAPITA”) and Frasers Centrepoint Trust (“FCTSP”), the SGDREIT 7Y notes at an IPG of 2.35% is 49 basis points (“bps”) above CAPITA 2.100% 08Mar2028 Corp (SGD) for an additional ~0.5 years difference in bond tenors between the two bonds.
Figure 4: G-spread of SGREIT and its peers
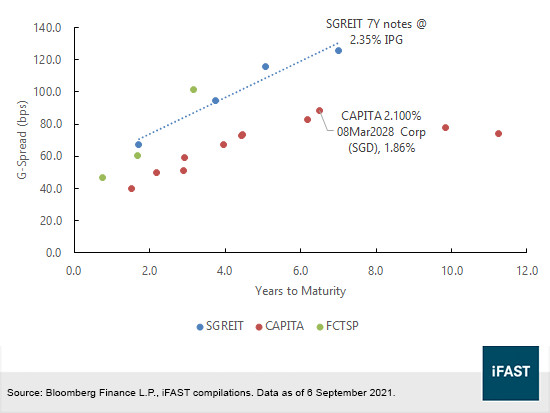
Comparing the G-spreads between its peers, the new issue 7Y notes has a G-spread of approximately 125.5 bps. Comparing it to CAPITA’s G-spread curve, we see that SGREIT has a steeper curve as compared to CAPITA. We feel investors who are considering a longer tenor retail REIT bond may consider this new issue as we find it fairly priced among other notes with the same maturity.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a NIL position and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!