- On 29 July 2021, SGREIT reported its full year financial results for the year ended 30 June 2021 and displayed growth and resilience during FY 20/21.
- Gross revenue for 2H FY 20/21 increased 10.5% year-over-year (“y-o-y”) to SGD 92.9m, bringing gross revenue for FY 20/21 to be SGD 181.3m, representing a 0.3% increase from FY 19/20.
- One key consideration for SGREIT is its long portfolio lease expiry profile. Weighted Average Lease Expiry (“WALE”) by Gross Rent is 5.3 years as at 30 June 2021.
- We recommend the SGREIT 3.850% Perpetual Corp (SGD) and SGREIT 3.400% 26May2023 Corp (SGD).
Retail REITs in Singapore were badly affected in 2020 by COVID-19 restrictions as consumers were not able to shop and dine-in in various retail malls around the country. As these restrictions remain in place for most of 2021, what does this mean for REITs operating primarily in the retail space?
Put simply, we still see value in the bonds of retail REIT issuers as we expect Singapore to ease restrictions following a strong vaccination campaign. Singapore targets to vaccinate two thirds of its population by Aug 9th. As of 4 August 2021, Singapore 62% of the population is fully vaccinated. In comparison, United States have 50% of their population fully vaccinated while the United Kingdom has 57%. We believe that social distancing restrictions will be eased moving forward as more people become fully vaccinated. With a strong pace of vaccination rolls outs in Singapore, we expect Starhill Global REIT to emerge as a strong player in the retail REIT space with looser restrictions and potentially higher shopper footfall.
About the Issuer
Starhill Global REIT (“SGREIT”) is a Singapore-based retail and office real estate investment trust. SGREIT has 10 properties under its portfolio situated in Singapore, Australia, Malaysia, China and Japan. SGREIT is managed by YTL Starhill Global REIT Management Limited.
Portfolio properties include Wisma Atria and Ngee Ann City, both of which are situated in the prime shopping district in Singapore. Its Australian properties include Myer Centre in Adelaide, David Jones Building and Plaza Arcade that are located in Adelaide and Perth, respectively. The REIT also owns The Starhill (formerly known as Starhill Gallery) and Lot 10 Property in Kuala Lumpur, Malaysia, a retail property in Chengdu, China, and two properties in Tokyo, Japan.
Figure 1: FY 20/21 Revenue by Geography
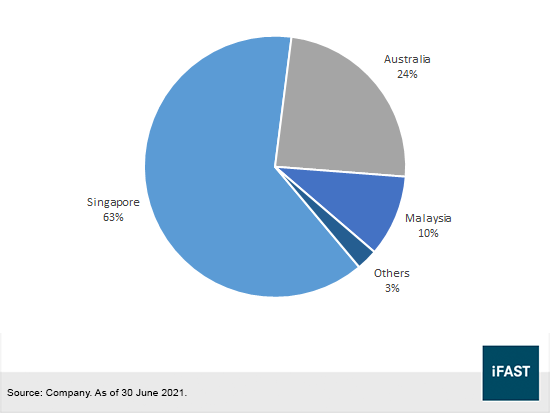
Singapore properties contributed SGD 114.0m for the financial year ended 30 June 2021 (“FY 20/21”). Australia properties contributed SGD 44.3m while Malaysia properties contributed SGD 18.3m during the fiscal year. Revenue from other properties, which include contributions from its Japan and China properties, added to SGD 4.7m.
Fitch assigned SGREIT a long term issuer rating of ‘BBB’ with a stable outlook. According to the rating agency’s report in March, Fitch believed that vaccinations will gain traction over the next few quarters and that the REIT's cash flow will improve and lockdown restrictions would ease.
Full Year Financial Results
Table 1: Financial Results of SGREIT
|
Year ended 30th June (in SGD m) |
FY 18/19 |
FY 19/20 |
FY 20/21 |
Y-o-Y change |
|
Revenue |
206.2 |
180.8 |
181.3 |
0.3% |
|
Operating income before working capital changes |
138.9 |
120.1 |
123.5 |
2.8% |
|
Finance expenses |
38.7 |
39.9 |
41.4 |
3.9% |
|
Total return before tax |
69.1 |
-96.0 |
58.0 |
160.4% |
|
Total return after tax |
65.6 |
-97.4 |
56.5 |
158.0% |
|
Balance sheet |
||||
|
Cash and cash equivalents |
72.9 |
117.4 |
108.3 |
-7.8% |
|
Total Assets |
3,142.0 |
3,081.0 |
3,079.6 |
0.0% |
|
Short Term Debt |
127.8 |
162.0 |
- |
-100.0% |
|
Gross Debt |
1,132.1 |
1,218.0 |
1,105.4 |
-9.2% |
|
Net Debt |
1,059.2 |
1,100.5 |
997.1 |
-9.4% |
|
Total Equity |
1,930.0 |
1,769.5 |
1,890.1 |
6.8% |
|
Cash Flow statement |
||||
|
Net cash from operating activities |
134.0 |
102.8 |
142.2 |
- |
|
Capital expenditure on investment properties, plant, property and equipment |
7.7 |
29.7 |
34.9 |
- |
|
Borrowing costs paid |
37.8 |
39.1 |
44.3 |
- |
|
Free Cash Flow estimate |
126.3 |
73.1 |
107.3 |
- |
| Source: Company, iFAST estimates. As of 30 June 2021. | ||||
On 29 July 2021, SGREIT reported its full year financial results for the year ended 30 June 2021 and displayed growth and resilience during FY 20/21. Gross revenue for 2H FY 20/21 increased 10.5% year-over-year (“y-o-y”) to SGD 92.9m, bringing gross revenue for FY 20/21 to be SGD 181.3m, representing a 0.3% increase from FY 19/20.
Net Property Income (“NPI”) increased 20.2% to SGD 69.8m for 2H 20/21 and NPI for FY 20/21 totalled to SGD 134.7m, a 2.0% increase y-o-y. The increase in NPI is largely due to lower tenant rental assistance and a stronger appreciation of the Australian dollar. We expect rental assistance to taper off slowly as Singapore eases social distancing requirements, leading to higher projected NPI in the future. Gross revenues is expected to rise to close to pre-pandemic levels of around SGD 190m.
Gross revenue for Singapore properties, Wisma Atria and Ngee Ann City, fell by 0.5% in FY 20/21. Retail gross revenue for Wisma Atria fell by 12.1% to SGD 40.9m while retail gross revenue for Ngee Ann City increased by 7.4% to SGD 49.5m. The fall in gross revenue for Wisma Atria is largely due to lower rent and occupancy rates, as well as more rental assistance granted to tenants. However, retail occupancy rate for Singapore properties remained resilient at a healthy 98.6%.
One key consideration for SGREIT is its long portfolio lease expiry profile. Weighted Average Lease Expiry (“WALE”) by Gross Rent is 5.3 years as at 30 June 2021. This is due to SGREIT’s portfolio of anchor tenants. 51.5% of SGREIT’s property portfolio are secured by anchor or master leases. This places the REIT in a favourable position to secure high occupancy rate and resilience to tide through a fall in retail traffic. Comparing other similar retail REITs such as SPH REIT (“SPHRSP”), Capitaland Integrated Commercial Trust (“CAPITA”) and Frasers Centrepoint Trust (“FCTSP”), we see that SGREIT has a far superior WALE as compared to the rest of its peers.
Table 2: WALE and Occupancy Rates of SGREIT and Peers
|
|
SGREIT |
SPHRSP |
CAPITA |
FCTSP |
|
Weighted Average Lease Expiry by Gross Rent (Years) |
5.3 |
^3 |
3.1 |
1.63 |
|
Occupancy Rate (%) |
97.5% |
^98.4% |
97% |
96.4% |
| Source: Company filings. As of 30 June 2021. ^As of 31 May 2021. | ||||
Occupancy rate for SGREIT is also comparable to its peers, only losing out to SPHRSP at 98.4%. Thus, we feel that SGREIT’s lease expiry profile and occupancy rate to be a positive credit driver in providing stability to its property portfolio.
Figure 2: SGREIT’s monthly tenant and shopper traffic for FY 20/21
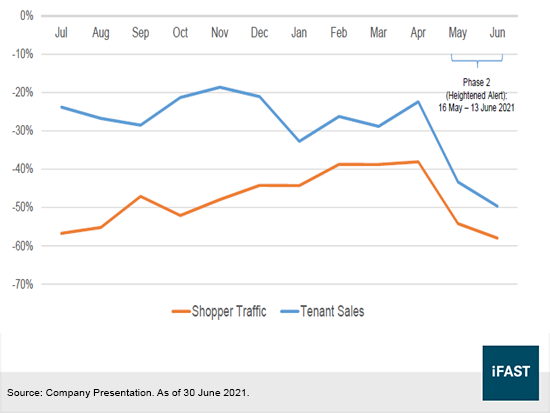
Tenant sales and shopper traffic dropped below pre-COVID-19 levels during FY 20/21, registering a 28.7% and 48.0% fall from FY18/19 levels respectively. This was due to COVID-19 enforcement measures in Singapore and a fall in tourist traffic. We expect traffic and retail sales to pick up when travel and other COVID-19 restrictions eases as the vaccination rate improves.
However, one of the key risks investors have to consider is the uncertainty in the spread of new COVID-19 variants and a slowdown in economic activity. Negative rental reversions and rental assistance are expected to continue albeit at a slower pace. The improvement in financial performance for retail REITs depends on the speed at which Singapore opens up its borders to travellers. However, looking at Singapore’s pace in vaccination and the government’s stance on COVID-19 as an endemic, shows positive signs that the government is willing to open up its borders in the near future.
Sector Outlook
Based on the Business Expectations Survey by the Department of Statistics for the services sector for 3Q21, firms in the services sector continue to keep a positive outlook for the next 6 months. 11% of firms expect a more favourable business outlook, continuing the trend of positive business outlooks between January and June this year. Nevertheless, the real estate industry is expected to see weaker business conditions particularly firms in the rental of retail spaces as lower demand for retail spaces continue to exert downward pressure on rental rates.
In SGREIT’s FY 20/21 presentation, the company has stated that the recovery of the retail sector remains uncertain due to new COVID-19 strains leading to lockdown restrictions in Malaysia and Australia while Singapore adopts Phase 2 (heightened alert) measures. SGREIT expects rental reversions and occupancy rate to be negatively impacted over the next year. The company will contemplate providing supplementary rental support for eligible tenants in addition to the assistance provided by the respective governments.
We feel the retail REIT sector will continue to see downward pressure on rental reversion rates and rental rebates for the coming months. Negative rental reversion will continue to impact the sector while rental rebates will ease off. In the longer term, given the higher vaccination rate, the number of shoppers and travellers may rebound faster than expected, providing a much needed resurgence to retail trade in the various countries.
Liquidity and Credit Profile
SGREIT has a prudent and well managed capital profile. Gross debt decreased from SGD 1,218.0m to SGD 1,105.4m. However, financial leverage for the company was nearly unchanged from FY 19/20 to FY 20/21, with Debt (including perpetual securities) to Total assets falling slightly from ~39.5% to ~39.1%. We feel that SGREIT’s capital management is favourable, given that it has reduced its leverage from the prior fiscal year and its gearing is lower than the MAS’s regulatory requirement of 50% for REITs.
Figure 3: Debt Maturity Profile of SGREIT
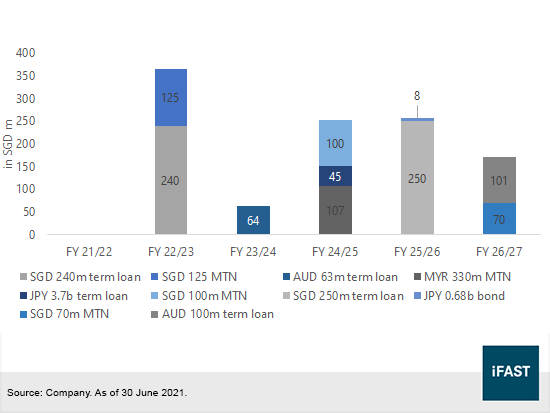
SGREIT has an average debt to maturity profile of 3.3 years and has managed to refinance all its expiring debt for FY 20/21 ahead of their expiry. There are no term debt maturities in the next 12 months for the company. SGREIT had drawn down on their 5-year SGD 250m unsecured term loan facilities in February 2021 to refinance the maturing SGD 100m medium term note and SGD 150m term loan in 2021.
Additionally, the company also drew down on its 5.5-year AUD 100m unsecured term load in May-June 2021 to refinance the remaining AUD 80m secured term load and prepaid SGD 20m of the SGD 260m unsecured term loan maturing in September 2022. As such, there are no term debt refinancing requirements for the company until September 2022 with undrawn committed revolving credit facilities available to the company for working capital requirements.
SGREIT have sufficient liquidity in the short term to tide through the current economic backdrop. Net cash from operating activities increased from SGD 102.8m in FY 19/20 to SGD 142.2m in FY 20/21. This is an improvement from pre-COVID levels of SGD 134.0m in FY 18/19. Overall, we feel SGREIT still have sufficient and healthy liquidity considering it has no short term debts to refinance.
Bond Recommendations
Figure 4: Relative valuation among SGREIT fixed rate bonds with other comparable SGD denominated Retail REITs
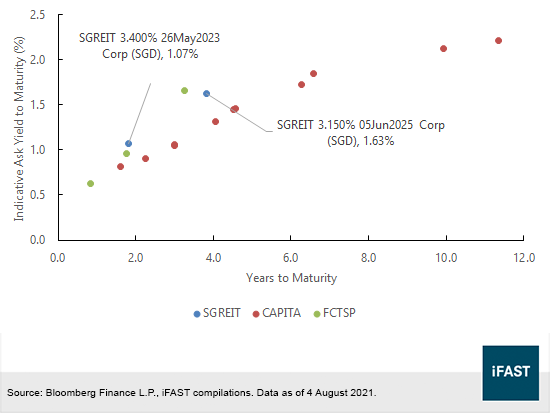
When comparing SGREIT’s fixed issues with other comparable retail REITs such as CAPITA and FCTSP, we see that SGREIT 3.400% 26May2023 Corp (SGD) has an indicative ask yield to maturity (“YTM”) of 1.07%. For stable income seekers, we would recommend the SGREIT 3.400% as it provides investors the highest YTM as compared to other SG retail REITs for a shorter duration.
Figure 5: Relative valuation among SGREIT Perpetual bonds with other comparable SGD denominated Peers
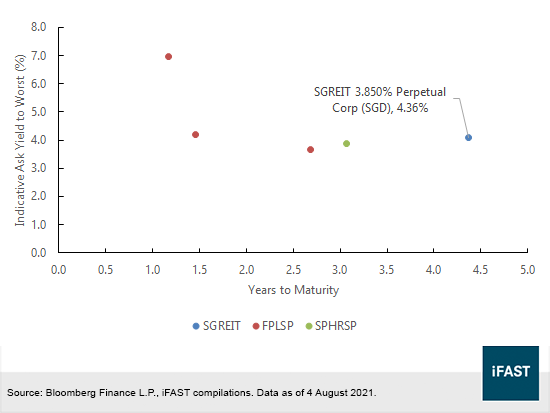
For high-yield seeking investors, they may consider the SGREIT 3.850% Perpetual Corp (SGD) that traded at an indicative yield to worst (“YTW”) of 4.36% on 4 August 2021. The perpetual note has a reset date on 15 December 2025 and every 5 years thereafter. The perpetual note also has a reset rate at the prevailing SGD 5Y Swap Offer Rate (“SOR”) + initial spread of 3.292%.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position SPHSP 4.500% Perpetual Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!