Having properties that are popular spots for tourists and business events, Suntec Real Estate Investment Trust (“REIT”) is yet another business being affected by COVID-19 measures. The SUNSP 3.800% Perpetual Corp (SGD), launched on Oct 19, raised S$200 million for Suntec REIT, which will give the trust more room to manoeuvre for its operations and financing activities. For investors, however, we believe there are more attractive investments out there.
Operating results
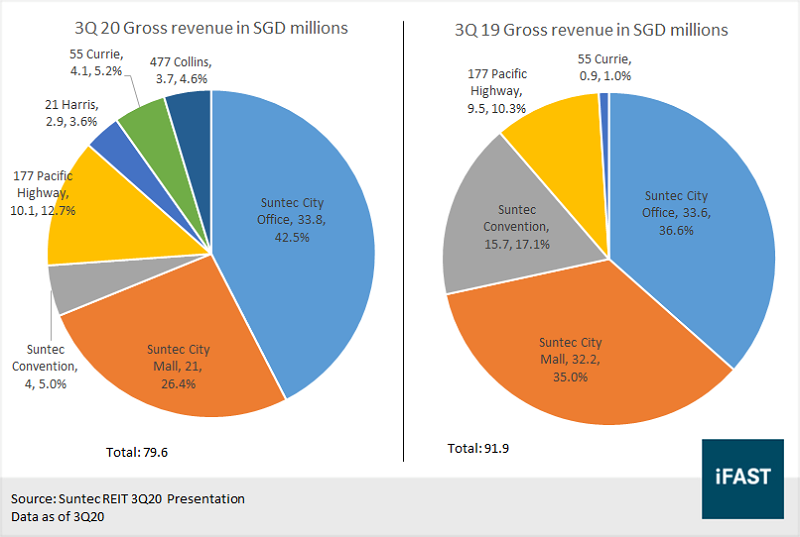
Although most people have been working from home for the large part of 2020, Suntec REIT’s revenue has not taken a substantial hit. On a YoY basis, gross revenue and net property income (“NPI”) declined by 13.4% and 19.0% respectively in 3Q20.
NPI and joint venture (“JV”) income from the REIT’s office buildings actually increased by 11.3% YoY in 3Q20 due to new acquisitions – 21 Harris, 55 Currie and 477 Collins. Office rentals were also less affected by COVID-19. However, the same cannot be said for the retail and convention segments. Due to the inability to hold large-scale events and circuit-breaker measures, revenue from Suntec City Mall and Suntec Convention were severely impacted, decreasing by 34.8% and 74.5% YoY respectively.
Although Singapore’s government has allowed a capacity of 250 for meetings, incentives, conferences and exhibitions events, the revenue from these relatively small-scale events will be a far cry of what Suntec REIT used to receive. Suntec REIT is trying to mitigate the downturn by reducing its fixed costs and has leased out the entire level 3 of Suntec Convention to North London Collegiate School of Singapore. The trust has also launched a hybrid broadcast studio to capitalise on live streaming demand.
Looking ahead, NPI from Suntec Convention will remain significantly affected due to smaller business crowds. NPI for Suntec City Mall should improve as rental assistance winds down in 4Q20 and footfall should increase as workers gradually return to their offices.
Figure 1: Resilient office performance, but the same cannot be said for others
Suntec REIT’s new acquisitions will provide another source of revenue, but is unable to compensate for the loss of income from Suntec City Mall and Suntec Convention. Suntec REIT is looking to acquire 50% interest in Nova North, Nova South and The Nova Building in London (subject to Suntec REIT’s unitholders’ approval).
These are high quality multi-tenanted office buildings with ancillary retail development. The agreed property value is GBP 430.6 million (S$766.5 million) with a NPI yield of 4.6% (~S$35.26 million). With 100% committed occupancy with a long-weighted average lease expiry (“WALE”) of 11.1 years, Suntec REIT seems to have acquired a stable source of income for the future.
According to Suntec REIT, the acquisition will provide additional net income of about S$8.64 million. The decrease in NPI from Suntec City Mall and Suntec Convention amounted to S$19 million in 1H20, resulting in a shortfall of about S$10 million even if we include a full-year net income contribution from the acquisitions. Thus, resumption of normal activities will still be a more important factor for Suntec REIT’s earnings recovery.
For its Singapore office portfolio, occupancy rate remains high at an average of 98.1%. The portfolio has a WALE of 3.01 years with 24.5% (598,619 sq ft) of its net lettable area expiring next year. While work-from-home arrangements have become more popular, Suntec REIT is looking at renewing its leases based on smaller areas, which may be a positive.
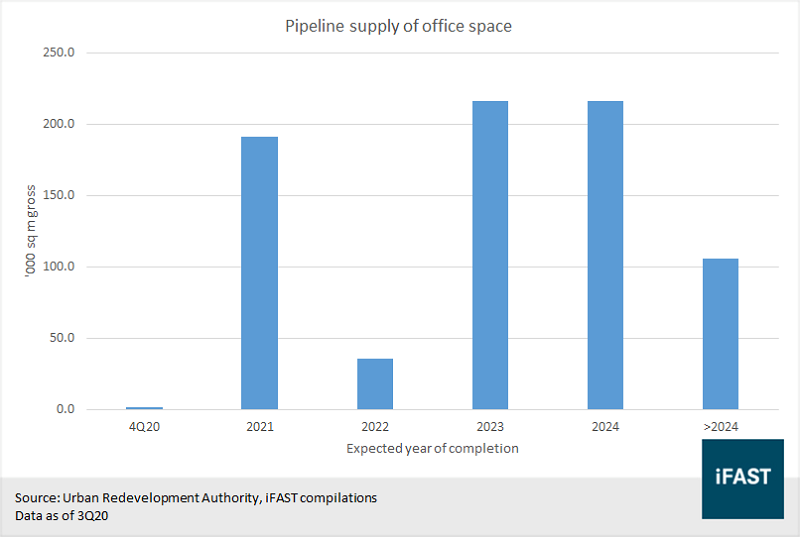
On the downside, office rental prices are still on a downward trend. 191,000 sqm of gross floor area of office space is expected to complete in 2021, which could continue to depress rental prices. While Suntec REIT’s office portfolio has benefited from ten consecutive quarters of positive rental reversions, the REIT is expecting rental reversions to be moderate in 4Q20. Hopefully, the increase in revenue from acquisitions would mitigate a decrease of rents from the Singapore office segment, if any.
Figure 2: Rental price of office space shows no signs of improvement
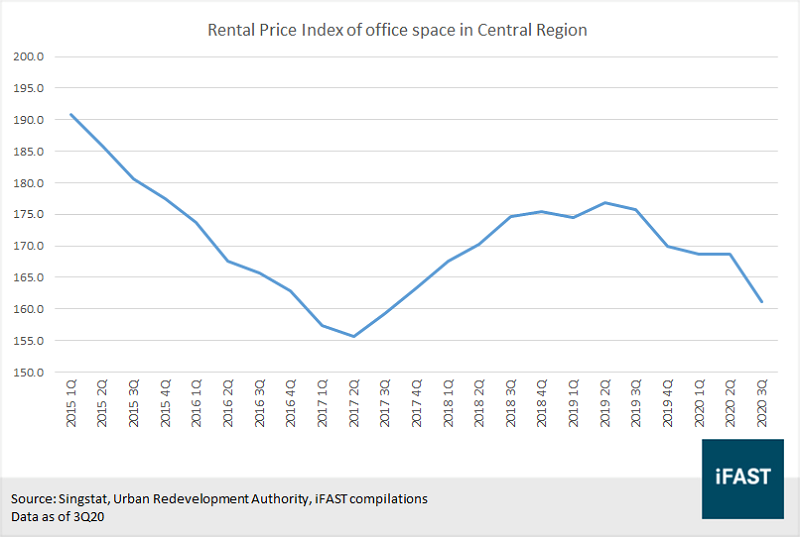
Figure 3: High office space supply coming in next year
Gearing
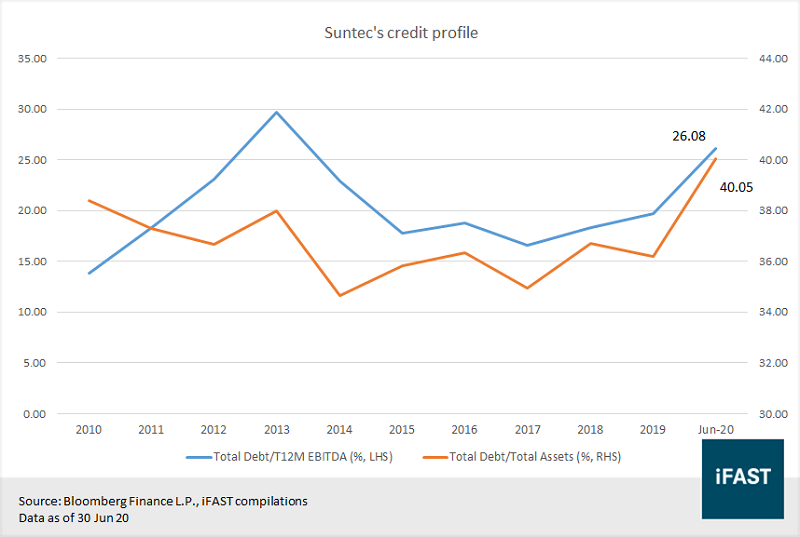
Suntec REIT’s total debt over trailing-twelve-month (“T12M”) EBITDA should continue to increase going forward due to the debt taken on for more acquisition. At the same time, new earnings are unable to fully compensate for the decline in other sectors.
Figure 4: Suntec REIT is looking more leveraged
Liquidity
Looking at Suntec REIT’s debt maturity profile and its cash balance, the new perp issuance does not look sufficient, on paper, to meet next year’s maturing debts. S$87m of convertible bonds have an adjusted conversion price of S$2.01 per new unit, and with the stock price at S$1.45 (as at Oct 27), it is unlikely that bondholders will choose to convert their bonds into shares.
The ratio of Suntec REIT’s secured debt to total assets stands at 7.52%, suggesting that Suntec REIT has the ability to obtain more secured loans by mortgaging its properties. Refinancing or acquiring new loans should not be a problem for the trust.
If worse comes to worst, Suntec REIT has almost S$3 billion valued in its joint ventures. Divesting the joint-venture interests would raise funds for debt redemption, although we think it is unlikely that it will come to this scenario.
Table 1: Liquidity analysis
|
S$ '000 |
|
|
Cash |
355,181 |
|
New perpetual bonds |
200,000 |
|
555,181 |
|
|
Debt maturing in FY212021 |
|
|
Bank loans |
370,000 |
|
Medium term notes |
150,000 |
|
Convertible bonds |
86,500 |
|
|
606,500 |
|
Source: Company's 1H20 financial results, 3Q20 update, iFAST estimates |
|
Suntec REIT’s bonds
The SUNSP 3.800% Perpetual Corp (SGD) looks attractive among Suntec REIT’s bonds. However, the same cannot be said when we compare the SUNSP 3.8% perp against other perps in the real estate sector, which include SPH and Wing Tai Properties.
Figure 5: The SUNSP 3.8% perp looks most attractive among Suntec REIT’s bonds
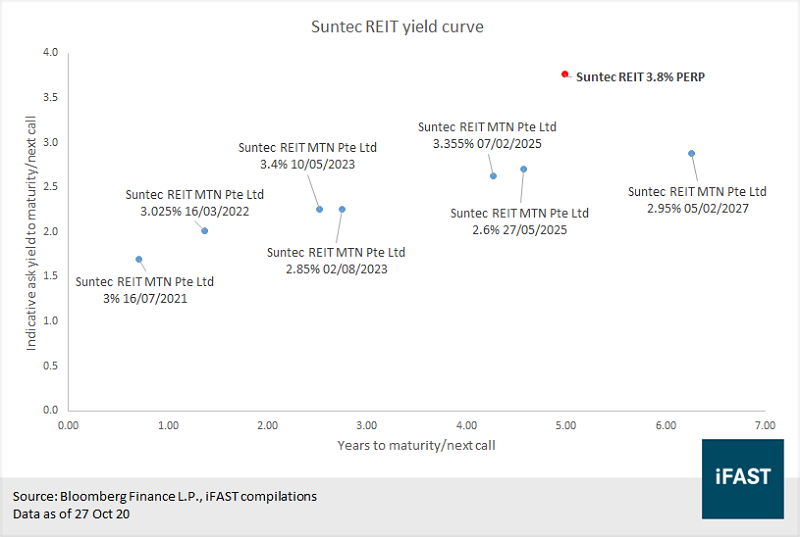
Table 2: Credit ratios
|
EBIT over interest (x) |
Net gearing (%) |
Total debt over total assets (%) |
|
|
AIMS APAC REIT |
2.8 |
66.5 |
39.1 |
|
ARA LOGOS Logistics Trust |
3.8 |
78.7 |
43.5 |
|
Ascendas Real Estate Investment Trust |
4.2 |
62.4 |
38.6 |
|
Ascott Residence Trust |
2.4 |
61.9 |
38.6 |
|
CapitaLand Ltd |
0.9 |
64.6 |
39.1 |
|
ESR-REIT |
2.8 |
87.1 |
44.2 |
|
Frasers Property Ltd |
2.0 |
111.9 |
52.7 |
|
GuocoLand Ltd |
2.3 |
96.6 |
47.5 |
|
Keppel REIT |
1.3 |
40.7 |
29.1 |
|
Mapletree Logistics Trust |
5.2 |
67.6 |
39.3 |
|
Singapore Press Holdings Limited |
3.9 |
49.1 |
35.8 |
|
SPH REIT |
5.4 |
41.1 |
29.5 |
|
Suntec Real Estate Investment Trust |
1.3 |
77.5* |
44.1* |
|
Wing Tai Holdings Ltd |
1.1 |
12.9 |
15.4 |
|
Source: Bloomberg Finance L.P., iFAST estimates Data as of 30 Jun 20, except Frasers Property Ltd (based on 31 Mar 20 numbers) * After accounting for acquisition of Nova Properties |
|||
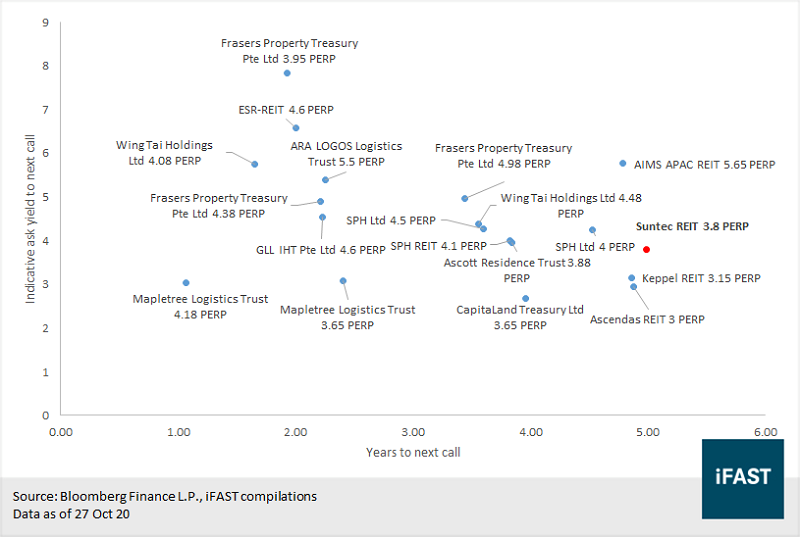
For investors looking for decent yields with good credit profile, the perps of Singapore Press Holdings and SPH REIT offer about the same yield with much better credit ratios, in our view. The perps issued by Frasers Property and Wing Tai Holdings look better priced too. Furthermore, after accounting for the acquisition, the SUNSP 3.800% Perpetual Corp (SGD) does not seem to offer good risk-reward currently.
Figure 6: Other perps look more enticing
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds positions in ARASP 5.200% Perpetual Corp (SGD), ARTSP 3.070% Perpetual Corp (SGD), FPLSP 4.980% Perpetual Corp (SGD) and SPHSP 4.500% Perpetual Corp (SGD). The analyst who produced this report holds a NIL position in the abovementioned securities.