


Up to Date with Rates
- In April, the People’s Bank of China (PBOC) kept 1y medium-term lending (MLF) facility rate unchanged at 2.5%. It also provided less liquidity than expected, as it offered just RMB 100b in loans through this 1y MLF facility compared to expectations of RMB 170b. A week later, they also kept their 5y and 1y loan prime rates unchanged at 3.95% and 3.45% respectively. Looking ahead, while China faces persistent deflationary fears and housing market weaknesses, the PBOC will likely also be mindful of how any rate cuts could worsen the downward pressure on the RMB, as the offshore RMB has already depreciated by -1.4% against the USD since the start of 2024.
- In April, the Bank of Canada (BoC) held policy rates steady, including its overnight rate of 5%. It also continued its quantitative tightening policy. The decision was driven by inflation remaining ‘still too high’, and by growth expected to pick up in 2024. Nonetheless, Governor Macklem noted ‘encouraging’ recent progress with the BoC expecting inflation to move closer towards the 2% target this year. Looking ahead, the BoC is looking for more data for assurance that the dip in inflation is sustained, before lowering policy rates.
- In April, the European Central Bank (ECB) kept its three policy rates unchanged, including holding its deposit rate at 4%, in line with consensus expectations. More importantly, there were signs that the ECB was setting the stage for its first rate cut in June. ECB President Lagarde reiterated the ECB’s data-dependent approach but highlighted that a few members of the Governing Council already felt ‘sufficiently confident’ about inflation in its April meeting but were waiting for further confidence from data by June (that inflation was falling sustainably towards the 2% target).
- In April, the Monetary Authority of Singapore (MAS) kept its policy settings unchanged, with no changes to the width of the S$NEER policy band, the level at which the band is centred, and the rate of appreciation of the SGD. This was in line with consensus expectations. On growth, MAS noted that global growth remained resilient at the turn of the year and that it expects the Singapore economy to strengthen over 2024. On inflation, the MAS expects core inflation to stay elevated in the immediate quarters, before stepping down more discernably in 4Q24 and into 2025.
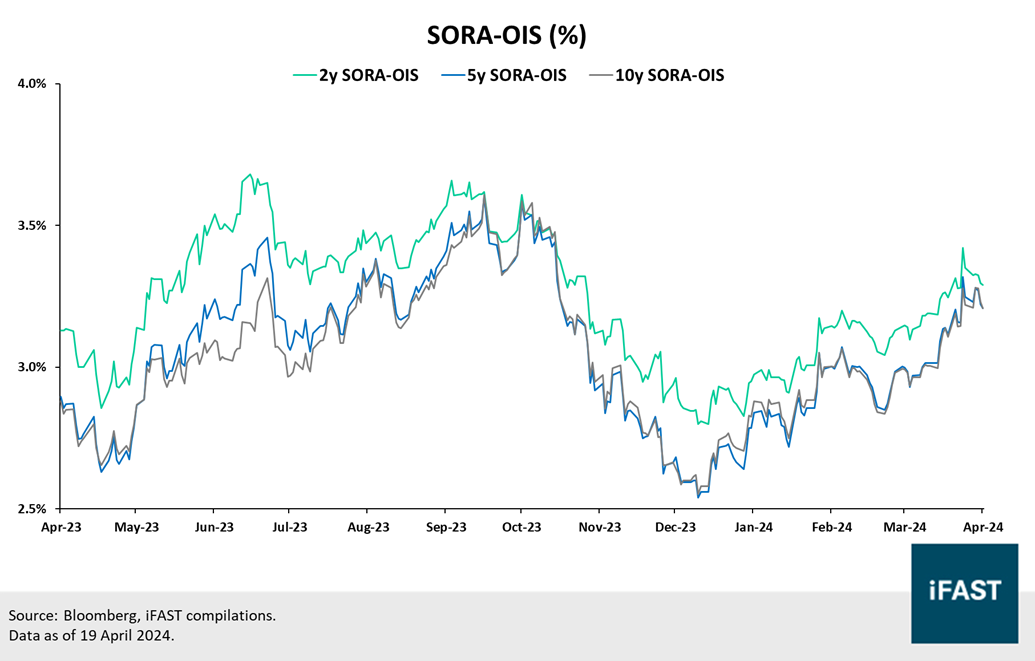
- Since our last article on 25 March 2024, the 2y SORA-OIS increased by 15bps to 3.290%, the 5y SORA-OIS increased by 24bps to 3.208%, and the 10y SORA-OIS increased by 24bps to 3.208% (as of 19 April).
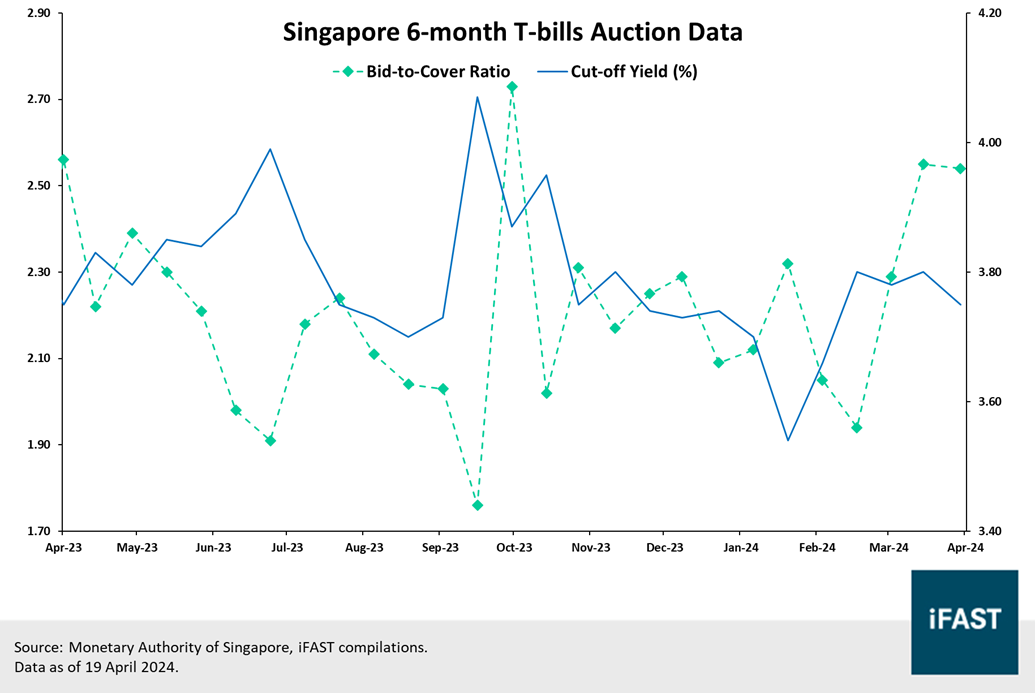
- The Singapore Treasury curve steepened over the same period. Benchmark yields for the 6m SG T-Bill rose by 1bps to 3.74%, while yields for the 1y SG T-Bill rose by 11bps to 3.61%. 5y SG T-Bill yields increased by 27bps to 3.27% while 10y SG T-Bill yields increased by 29bps to 3.35%. In the latest 6m SG T-Bill auction, we saw cut-off yields remaining fairly steady at 3.75% alongside solid demand observed from its bid-to-cover ratio (2.54x).
Favourite Bond Investment Ideas
- TMGSP 4.050% 28Jan2025 Corp (SGD) – Decent outlook despite cost uncertainties
Thomson Medical Group (TMG) recently acquired Far East Medical Vietnam Limited, purported to be Southeast Asia’s largest healthcare acquisition since 2020. We expect TMG’s credit profile to deteriorate post-acquisition, though we see little near-term worries considering its prudent cash position. Over the longer term, TMG’s development plans should help to improve its top-line, though the results on bottom-line performances will depend on cost management. We prefer the shorter-tenor 2025 bonds (over its 2028 bonds) for their shorter duration and comparable yields.
- RAKUTN 11.250% 15Feb2027 Corp (USD), SOFTBK 5.125% 19Sep2027 Corp (USD), & NSANY 3.522% 17Sep2025 Corp (USD) - Three high-yield issuers from Japan to consider
Japan is undergoing a resurgence, and this growth momentum coupled with ongoing corporate reforms could ultimately benefit Japanese bond issuers. We highlight three bonds from Rakuten, Softbank, and Nissan. The Rakuten bonds offer the highest indicative yields in the 9% region and are also available on our Bond Express for investors who wish to purchase odd lots. The Softbank bonds have indicative yields closer to 7%, while the Nissan bonds have indicative yields of just over 6%.
- FPLSP 4.250% 21Apr2026 Corp (SGD), FPLSP 4.150% 23Feb2027 Corp (SGD), FPLSP 4.490% 16Sep2027 Corp (SGD) – Retail, & FPLSP 3.000% 09Oct2028 Corp (SGD) – Bonds from one of Singapore’s most well-known property developers
FPL delivered a solid operating performance in FY23 with revenues and PBIT both growing by single-digit percentage terms. Still, net profits fell sharply (-83% YoY) in the high interest rates environment, primarily due to unrealised net fair value losses on properties (SGD -446m in FY23). Despite this, FPL’s credit profile remains decent with a well-distributed maturity profile, and think that default risks still look manageable. The choice of bonds will mainly differ depending on investors’ preferences for duration and coupon levels, except for the retail bond which we only recommend for investors who wish to invest in smaller denominations below SGD 250,000.
- HSBC 4.750% 12Sep2034 Corp (SGD) & HSBC 5.546% 04Mar2030 Corp (USD) – SGD and USD bonds from a global bank which recently delivered record profits
HSBC delivered a strong performance in FY23 and is poised to continue doing so given its diversified revenue exposures across the globe, cost discipline, and resilient banking net interest income. While it does have some exposure to the Greater China region, it looks well-managed for now and is fairly small compared to its overall operational size.
The former is a recently issued Tier 2 subordinated SGD bond with a little over 5 years to call (we think it is likely they will call the bond based on current circumstances), while the latter is a senior unsecured USD bond.
Hot New Issues
Table 1
|
Issue |
Issuer |
Issuance Date |
New Issue View |
|
Wing Tai Holdings Limited |
03 April 2024 |
Wing Tai Holdings announces 5-year senior notes at the IPG of 4.60% |
|
|
Deutsche Bank |
05 April 2024 |
Deutsche Bank announces new 4NC3 SGD senior non-preferred notes at the IPG of 4.70% |
|
|
AIA Group Limited |
05 April 2024 |
||
|
Great Eastern Life Assurance Company |
17 April 2024 |
Great Eastern Life announces new 15NC10 T2 Subordinated SGD bond at 4.25% IPG |
|
|
Source: Bondsupermart, iFAST compilations. Data as of 22 Apr 2024. |
|||
Corporate Updates You Should Know
- 26 March – Frasers Centrepoint Trust (FCT) announced the completion of the acquisition of NEX Partners Trust and its Trustee-Manager. FCT now owns an effective 50.0% interest in the retail mall “NEX”.
- 27 March – Mapletree Industrial Trust announced the completion of the divestment of the Tanglin Halt Cluster.
- 28 March – ESR-LOGOS REIT announced that its trustee has entered into an SGD 200m sustainability-linked unsecured revolving credit facility agreement.
Separately, ESR-LOGOS REIT also announced on 11 April that they had entered into a contract of sale to divest an Australian logistics facility for AUD 65.5m, at a 7.4% premium to valuation. - 01 April – Keppel Infrastructure Trust (KIT) and the Infrastructure Division of Keppel Ltd (Keppel) have proposed to amend and extend the Capacity Tolling Agreement and O&M contract for the Keppel Merlimau Cogen (KMC) Plant by 10 years from 2030 to 2040. This is expected to generate up to SGD 1,080m in long-term capacity payments for KMC. The pro-forma effects on KIT (for FY23, if the capital restructuring was effected on 1 January 2023) is about a +10.9% increase in distributable income.
- 04 April – Olam Group Limited (Olam) announced that it has secured a USD 625m Shariah-compliant (commodity Murabaha) financing facility. This facility is initially guaranteed by Olam, which will transfer to Olam Agri after the planned IPO and de-merger of Olam Agri.
- 09 April – Frasers Property Limited (FPL) released a profit guidance statement. FPL announced that based on preliminary results, it expects to record fair value losses and impairment (non-cash) primarily on certain commercial properties in the UK, and it expects to report a significant decrease in attributable profit in 1H24 (on a YoY basis). It will be releasing its unaudited 1H24 results on 10 May 2024.
Separately, Frasers Property Limited announced on 11 April that it has fully redeemed its SGD 600m fixed-rate perpetuals (FPLSP 4.980% Perpetual Corp (SGD)). - 15 April – Singapore Airlines Limited (SIA) released operating statistics for March 2024 (all growth figures are YoY). On the passenger side, available seat-km grew by +15.5%, revenue passenger-km grew by +13.9%, while passenger load factor fell by -1.3 percentage points. On the cargo side, cargo loads (in tonne-km) increased by 15.6%, while cargo load factor improved by 4.9 percentage points to 60.0%.
- 15 April – United Overseas Bank Limited (UOB) announced that it has fully redeemed its USD 600m Tier 2 subordinated notes (UOBSP 3.750% 15Apr2029 Corp (USD)).
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in RAKUTN 11.250% 15Feb2027 Corp (USD), HSBC 5.546% 04Mar2030 Corp (USD) and TMGSP 5.500% 31May2028 Corp (SGD). The analyst who produced this report holds an NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!


