


Highlights:
- Sun Hung Kai Company is actively expanding its fund management business and trying out a platform-based business model to create a reliable revenue stream. The performances of financing and investment segments are fair. However, the company’s investment skills are strong. The recent investment losses should only have a temporary impact on the company.
- The company’s substantial financial assets could be a potential liquidity source, with a good leverage level and low refinancing risk. The credit profile is quite decent.
- Investors could consider the 2026 bond, with a yield to maturity of 9.6%.
Trying Out a Platform-based Business Model with Fair Performance in Financing and Investment Segments
From 2021 onwards, Sun Hung Kai Company is actively expanding its fund management business, including establishing a fund management platform (Sun Hung Kai Capital Partners), establishing multiple funds to attract external capital and launching family office solutions. The company is trying out a platform-based business model to create a reliable revenue stream and build a robust business model.
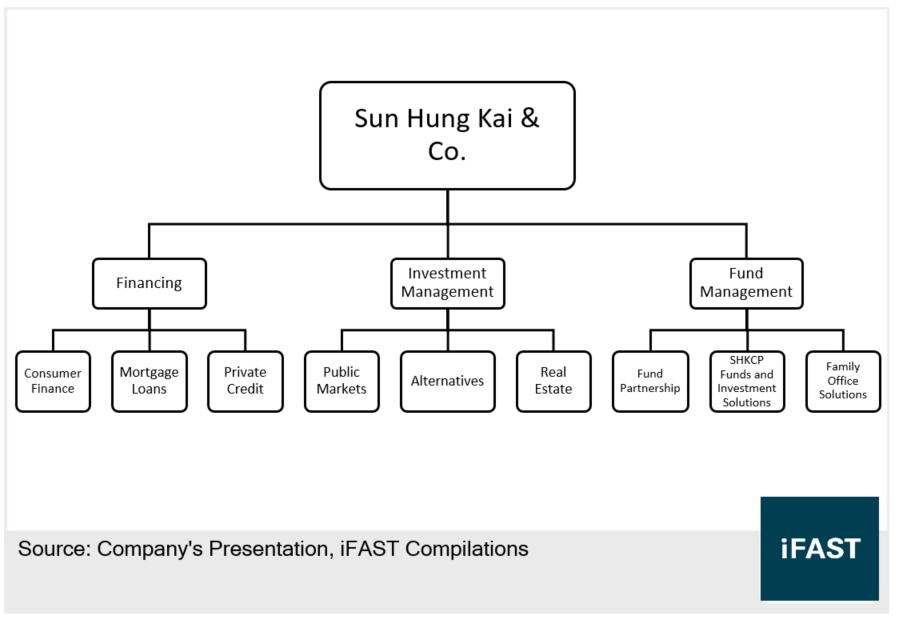
In contrast to the past, the company only has a financing business and an investment management business (see Chart 1). The investment is deployed by its own funds. In terms of earnings, both of them are generally more volatile and are susceptible to greater impacts from the macro environment and the capital markets.
Chart 1: Sun Hung Kai Company’s Main Businesses
In contrast, platform and management fees from the fund management business are generally more stable, especially as the company is focusing on a range of private equity and alternative investment funds. Over a longer term, we believe the earnings structure of the company will become more resilient as the earnings contribution from this business continues to grow. However, as it is still at the edge of breaking even, it is too early to see this trend from the current results.
As shown in Chart 2, the company's profits continue to be mainly driven by the financing and investment management businesses, with total revenue falling by 2.8% YoY to HKD 2.01 billion in the first half of 2023 (see Table 2). Among them, the segment profit of the financing business segment dropped by 18.3% YoY to HKD 590 million. The performance was not very decent. There is a decline in the company’s loan balance. The demand for loans from SMEs was reduced, due to the slowdown in the economic growth of Hong Kong and Mainland China and several interest rate hikes.
Chart 2: Sun Hung Kai
Company’s Segment Profit
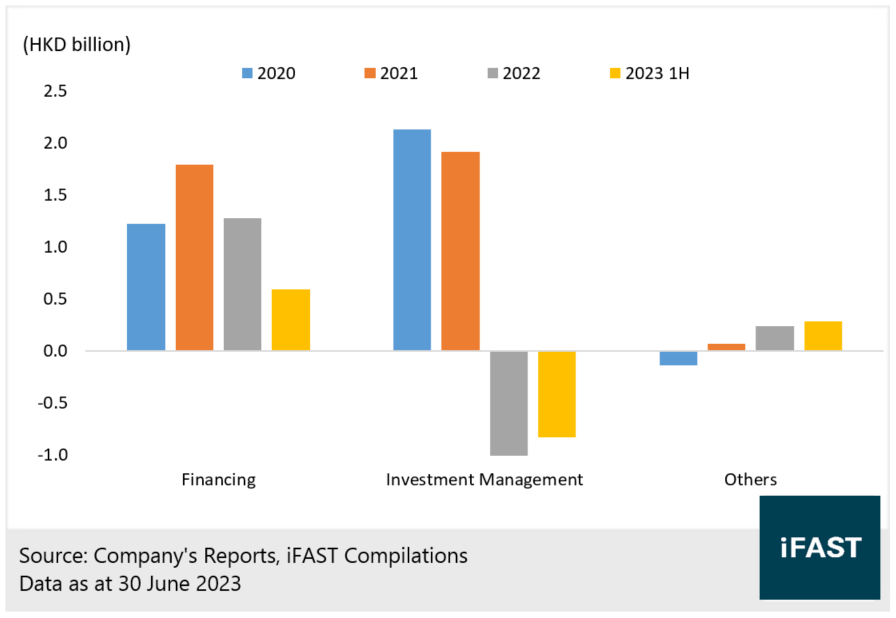
Table 1: Sun Hung Kai Company’s Main Operating Indicators
|
2021 |
2022 |
2023 1H |
|
|
Total Revenues (HKD billion) |
4.44 |
4.15 |
2.01 |
|
EBITDA (HKD billion) |
4.55 |
0.02 |
-0.06 |
|
Total Loan Balance (HKD billion) |
17.7 |
15.8 |
14.9 |
|
Total Return on Loans (Financing Business) (%) |
26.9% |
29.4% |
23.4% |
|
Investment Portfolio Value at the end period (HKD billion) |
21.1 |
17.6 |
16.3 |
|
Return on Investment (Investment Management Business) (%) |
14.4% |
-8.3% |
-2.3% |
|
Sources: Company’s Reports, iFAST Compilations Data as at 30 June 2023 |
|||
With Company’s Strong Investment Skills, Last Year’s Investment Losses should only have a Temporary Impact
On the other hand, in 2022 and the first half of 2023, the investment management segment turned the profit into a loss, where it recorded a loss of HKD 2.4 billion and HKD 0.83 billion, mainly due to the mark-to-market loss of financial instruments. In 2022, the poor performance of the global market year-to-date along with double-digit declines in most mature markets would undoubtedly drag down the company’s short-term performance. Since year-to-date, the weak performance in China and Hong Kong markets dragged down the company’s performance.
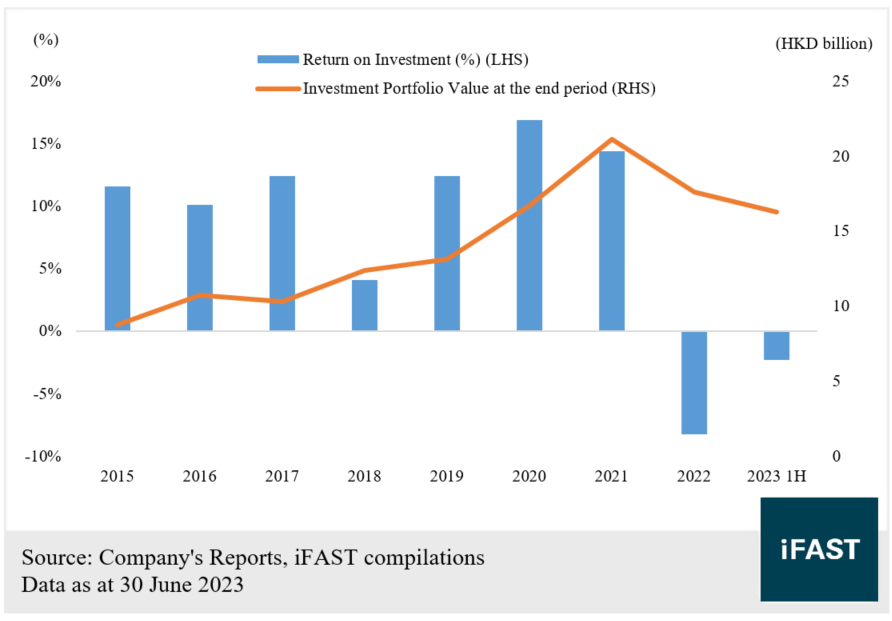
However, since the company's track record (see Chart 3), the company delivered impressive investment performances in most of the years, which proves that the company's investment skills are strong. We believe that the recent investment losses should only have a temporary impact on the company. In the long run, the investment management business should continue to bring the company good profit.
Chart 3: Sun Hung Kai Company’s Past Returns on Investment and Investment Portfolio Value
Substantial Potential Liquidity Source; Credit Profile is Decent
As of the end of June 2023, the company had total debt of HKD 14.5 billion. The net gearing ratio dropped to 31.6% (See Table 2). The debt level was improved. The company had financial assets of up to HKD 14.0 billion. These substantial financial assets could be a potential liquidity source for the company. If we classify these financial assets as cash and cash equivalents, the company can be considered to be in a net cash position. The company’s leverage level is good.
Table 2: Sun Hung Kai Company’s Credit Indicators
|
Dec 21 |
Dec 22 |
Jun 23 |
|
|
Total Assets (HKD billion) |
48.8 |
42.9 |
41.4 |
|
Total Cash (HKD billion) |
6.0 |
5.9 |
6.6 |
|
Financial Assets (HKD billion) (Mainly equities, bonds, funds and derivatives) |
18.7 |
14.7 |
14.0 |
|
Total Debts (HKD billion) |
18.7 |
16.2 |
14.5 |
|
Net Gearing Ratio (%) |
44.6% |
45.2% |
31.6% |
|
Average Cost of Borrowing (%) |
4.0% |
5.2% |
6.3% |
|
Sources: Company’s Reports, iFAST Compilations Data as at 30 June 2023 |
|||
In terms of the debt structure, the USD bonds (two bonds due in November 2024 and September 2026 respectively) and bank loans account for 39% and 61% of the company’s debt respectively.
The company has sufficient cash to repay the November 2024 USD bond, which amounted to around USD 320 million (equivalent to HKD 2.52 billion). For bank borrowings, its short-term refinancing risk is low as it is currently in a stable business position and will be able to refinance under normal circumstances. Overall, the company's credit profile is quite decent.
Investors Could Consider 2026 Bond with a Yield to Maturity of 9.6%
Taking reference to its two USD bond yields (see Table 3), the 2024 bond yield is only 6.8%, which has a lower attractiveness. However, the 2026 bond yield reaches over 9%, indicating a higher attractiveness.
Based on the strong credit position and the availability of financial assets for liquidation, we believe the risk of default on its medium and short maturity bonds is low. Investors could consider the 2026 bond, with a yield to maturity of 9.6%.
Table 3: Sun Hung Kai Company’s Bonds
|
Bond Name |
Years To Maturity |
Ask Price (Investors Buy) |
YTM (%) |
| SUNHKC 5.750% 15Nov2024 Corp (USD) | 1.3 |
98.5 |
6.8% |
|
3.1 |
88.5 |
9.6% |
|
|
Source: Bondsupermart Data as of 18 August 2023 |
|||
Related Risks
The company relies heavily on the returns of its investment portfolio for profitability. The performance of the company's portfolio may be affected if the global economy enters a severe recession.
With the slowdown in economic growth in Hong Kong and Mainland China and interest rate remaining higher for longer, the demand for loans might be reduced and the loan default rate might be increased.
Conclusion
Sun Hung Kai Company is actively expanding its fund management business and trying out a platform-based business model to create a reliable revenue stream. The performances of financing and investment segments are fair. However, the company’s investment skills are strong. The recent investment losses should only have a temporary impact on the company.
The company’s substantial financial assets could be a potential liquidity source, with a good leverage level and low refinancing risk. The credit profile is quite decent.
Investors could consider the 2026 bond, with a yield to maturity of 9.6%.
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!











