- WCT Holdings Berhad (WCT) plans to issue a 4-year unsecured bond with an indicative yield of 5.40% (equivalent to MGS +210bps). The proposed issuance size is up to RM300 million.
- The bonds are unsecured bond and rated A+ by MARC with positive outlooks.
- WCT is a publicly listed property company with a market capitalisation of RM640 million as of 16 July 2026. As of 1QFY26 (March 2026), approximately 56% of its revenue is generated from the engineering and construction.
- Recently, WCT has secured three construction contracts worth a combined RM880.3 million in 2026, including two major residential developments in Abu Dhabi and a highway infrastructure project in Taiwan. These contract wins strengthen its order book and improve earnings visibility over the medium term (Table 1).
Table 1: Recent Construction Contract Wins
|
Announcement Date |
Project |
Contract Value (WCT Share) |
Details |
|
7 Jul 2026 |
Yas Riva Residences, Abu Dhabi |
RM926.2m (~RM463.1m, 50:50 JV) |
Construction of six 11-storey residential buildings with a common basement for Aldar Development. Expected Commencement in 3Q26; completion within approx. 1,218 days. |
|
18 Jun 2026 |
Yas Living Main Works Package, Abu Dhabi |
RM529.0m (~RM264.5m, 50:50 JV) |
Construction of three 12-storey mixed-use residential and commercial buildings on Yas Island. Expected Commencement in 3Q26; completion within approx. 972 days. |
|
18 May 2026 |
Taiwan Sun Yat-Sen Freeway Project |
RM152.7m (100% WCT) |
Road, bridge and drainage work for a 4.1km freeway section in Kaohsiung. Construction starts Aug 2026 with a approx.42-month duration. |
|
Total |
RM880.3m |
||
|
Source: WCT, iFAST Compilation. Data as of 7 July 2026 |
|||
- The Property Development segment remains healthy is supported by over RM2.4 billion of ongoing GDV, strong take-up rates across its key projects, and approximately RM2.5 billion of earnings visibility from upcoming launches and unbilled sales as at 1Q26 (Table 2)
Table 2: Property Development Pipeline and Upcoming Launches
|
Project |
Location |
Estimate GDV (RM’ Million) |
Status (Launch Date / Take-up Rate) |
Targeted Completion |
|
Ongoing Property Projects |
|
|||
|
Aras Residences (Tower A) |
WCity OUG, Kuala Lumpur |
503 |
Launched 3Q 2025; 35% take-up rate |
Q4 2029 |
|
Phase 1A Adison |
W City Larkinton, Johor Bahru |
551 |
Launched Mar 2024; 96% take-up rate |
Q2 2028 |
|
Phase 1B Adison |
W City Larkinton, Johor Bahru |
584 |
Launched end Dec 2024; 72% take-up rate |
Q4 2028 |
|
Pavilion Mont’ Kiara ok |
Kuala Lumpur |
820 |
Launched Aug 2023; 98% take-up rate. |
Q3 2027 |
|
Future Property Projects (Planned Launch 2026) |
||||
|
Commercial (Strata shop/shop office) |
W City OUG, Kuala Lumpur |
626 |
Planned Launch 2026 |
- |
|
Aras Residences (Tower B) |
W City OUG, Kuala Lumpur |
527 |
- |
|
|
Residences (Phase 2B) |
W City Larkinton, Johor Bahru |
383 |
- |
|
|
Source: WCT, iFAST compilations. Data as of 31March 2026 |
||||
- For the Property Investment segment, as highlighted in our previous article. WCT continues to hold a 65% stake in Paradigm REIT, providing a stable source of recurring income through dividend distributions and asset management fees. The REIT's portfolio of three retail assets continues to record near-full occupancy, reflecting resilient tenant demand and strong tenant retention.
- WCT's 1Q26 revenue declined 6% YoY to RM445.3 million, mainly due to the absence of rental income following the injection of assets into Paradigm REIT in June 2025, as well as lower Property Development revenue, as 1Q25 was boosted by significant land sales. Nevertheless, Engineering & Construction revenue increased 10% YoY to RM246 million, supported by faster project execution.
- From a credit perspective, WCT's net gearing ratio remained relatively stable at 73%, while its interest coverage ratio improved to 2.2 times in 1Q26 from 1.6 times in FY25, indicating an improvement in its debt-servicing capacity despite still being relatively modest.
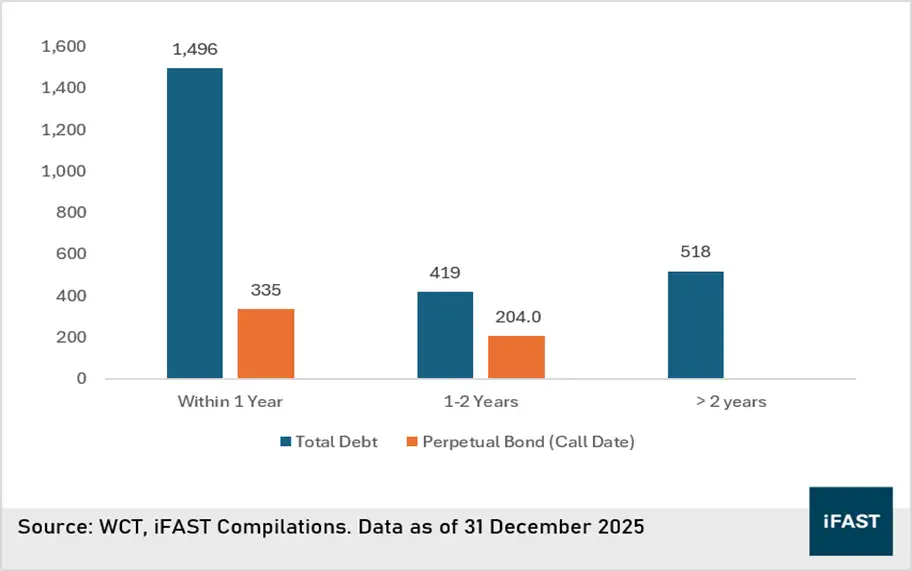
- In FY25 (Dec 25) around 62% of WCT’s borrowings (approximately RM1.8 billion) are due within one year (Chart 1). However, refinancing risk is mitigated by cash and bank balances of RM587 million and RM2.0 billion in undrawn credit facilities, providing liquidity headroom for near-term obligations.
Table 3: WCT’s Debt Maturity Profile
- While leverage remains elevated compared with higher-rated peers, improving earnings and stronger construction execution should provide further support to its credit profile if these trends are sustained.
- We are upgrading our view on WCT from Neutral to Slightly Positive, compared with our previous article, supported by its recent contract wins, which have strengthened earnings visibility in medium term, together with a modest improvement in its credit metrics.
- Investors may consider WCT's 4-year bond with an indicative yield of 5.40%. We prefer the 4-year tenor over longer-dated bonds, as longer maturities carry greater execution and cyclical risks, particularly given the construction sector's sensitivity to project timing, economic conditions, and industry cycles.
- Investors should note that the final issuance price may not necessarily align with the guidance yield.
- For further insights, please refer to our previous article: WCT 3Y bond at 5.25%: Property-led growth, but caution on construction orderbook pressures | Bondsupermart
Declaration
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report holds a NIL position in the abovementioned securities.