


Zetrix: Share Price Sell-Off Raises Market Confidence Concerns
Zetrix AI's share price fell sharply by approximately 50% from RM0.595 to RM0.295 on 28 August 2026, before declining further to RM0.265 on 1 September 2026. The share price subsequently increased slightly to RM0.270 as of 9 September 2026, amid elevated trading volume (Chart 1).
Chart 1: Zetrix Share Price
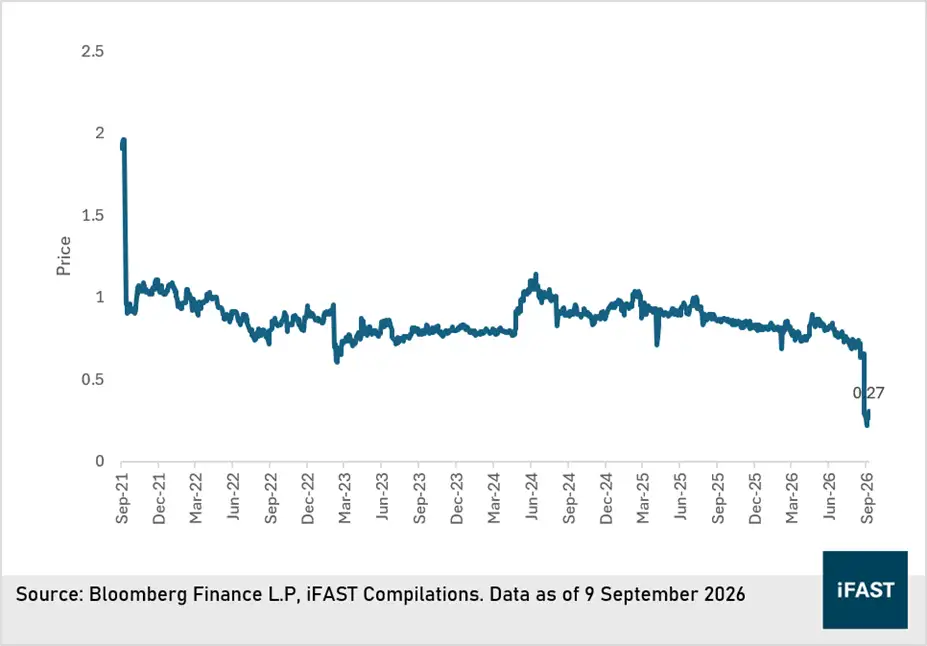
The sell-off appears to have reflected several negative developments occurring within a short period:
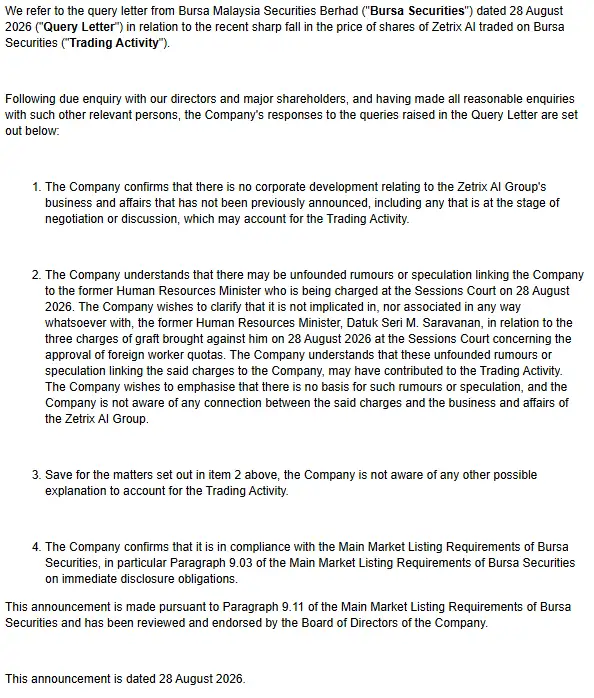
1. 28 August 2026 – Corruption case speculation: News involving former Human Resources Minister Datuk Seri M. Saravanan triggered speculation over a possible connection with Zetrix AI. The company subsequently clarified that it was not involved and that the entity referenced in the case was separate from Zetrix AI.2. 27–28 August 2026 – Co-founder margin call share disposals: According to a report by The Edge Malaysia, selling pressure intensified following substantial disposals by co-founder Wong Thean Soon and his investment vehicle, reportedly linked to margin-call pressure and forced sales of pledged shares. Approximately 960.7 million shares, valued at around RM228 million, were disposed of, reducing his combined direct and indirect interest from approximately 29.49% to 13.14% as of 9 September 2026.
3. 1 September 2026 – Auditor-related concerns: News that TGS TW PLT had resigned as auditor for several listed companies raised concerns among investors, as TGS TW is also Zetrix AI's external auditor. Although Zetrix AI clarified that TGS TW remained its auditor, the development added to existing uncertainty and investor concerns.
4. 1 September 2026 – Acquisition funding and dilution concerns: The proposed RM130 million MYEG Philippines acquisition will be funded mainly through new share issuance, with only RM29 million in cash consideration. While the relatively small cash component limits near-term liquidity pressure, the new share issuance could result in further shareholder dilution.
Figure 1: Letter Subject or Reference - UNUSUAL MARKET ACTIVITY
Source: Bursa Malaysia, iFAST Compilation. Data as of 28 August 2026
Relevant Link: Announcement details
From our perspective, the corruption-related speculation should not be viewed as a fundamental issue for Zetrix AI. The company has clarified that it was not involved in the matter, and the business referenced in the corruption case is separate from Zetrix AI.
In addition, Zetrix AI's previous foreign-worker permit-related business was revoked by the Malaysian government in July 2025. As such, the Group's current business is increasingly focused on its blockchain and AI-related businesses, with the key question being whether its sizeable development cost can be successfully monetised and generate sufficient cash flow to support its higher debt burden. As highlighted in our previous article Credit Update: Zetrix Moderate Refinancing Risk Ahead and strategic pivot into Blockchain | Bondsupermart
MYEG Philippines Acquisition Supports Strategic Expansion
On 1 September 2026, Zetrix AI announced a RM130 million acquisition of a 50% stake in MYEG Ventures, which was subsequently terminated and restructured before being re-announced on 7 September 2026 with IPVG Employees Inc as the seller. Upon completion, Zetrix’s effective interest in MYEG Philippines would increase to 74.5%, allowing it to consolidate the business and benefit from its established government-services operations.
MYEG Philippines has demonstrated improving operating performance, with revenue increasing from RM24.4 million in FY2023 to RM49.0 million in FY2025, while the Group's share of profit rose from RM0.44 million to RM1.16 million. After incurring initial losses due to high upfront investments and low transaction volumes, the business turned profitable from FY2023 as transaction volumes increased and more government agencies were onboarded, suggesting it has moved beyond its initial ramp-up phase.
The transaction is manageable from a near-term liquidity perspective, as 78% of the consideration will be settled through new shares and only RM29 million in cash. Nevertheless, the share issuance will result in shareholder dilution.
Table 1: MYEG Philippines Financial Performance
|
Year |
MYEG Philippines Total Revenue (RM Million) |
JV Net Profit / (Loss) (RM Million) |
Group's Equity Share |
Group's Share of Profit / (Loss) (RM Million) |
|
FY2021 |
12.38 |
(1.64) |
40% |
(0.65) |
|
FY2022 |
16.18 |
(0.31) |
40% |
(0.12) |
|
FY2023 |
24.42 |
(0.89) |
49% |
0.44 |
|
FY2024 |
31.66 |
1.41 |
49% |
0.69 |
|
FY2025 |
48.98 |
2.37 |
49% |
1.16 |
|
Source: Zetrix AI, iFast Compilation. Data as of 31 December 2025 |
||||
Revenue Mix Shifts Towards Commercial and Blockchain/AI Activities
MYEG’s revenue mix has shifted materially towards commercial and blockchain/AI-related activities. Commercial services remained the largest revenue contributor, increasing from RM459.3 million in FY2021 to RM618.5 million in FY2025 and accounting for approximately 46% of total Group revenue. Meanwhile, blockchain and AI-related services grew rapidly from RM127.7 million in FY2023 to RM643.5 million in FY2025, accounting for approximately 48% of total Group revenue and highlighting the Group’s increasing exposure to these businesses.
In contrast, traditional concession-related revenue has declined significantly. Concessions-based services fell from RM59.6 million in FY2021 to RM30.1 million in FY2025, while concession-related services and rentals declined from RM123.8 million to only RM0.35 million over the same period (Table 2).
Overall, the revenue mix indicates a structural shift away from MYEG’s traditional concession-based model towards commercial and blockchain/AI-related activities. While this diversification supports future growth potential, the increasing reliance on blockchain/AI-related revenue also makes the Group’s earnings increasingly dependent on its ability to monetise these newer businesses.
Table 2: MYEG Revenue Breakdown Over Past 5 year
|
FY2021 |
FY2022 |
FY2023 |
FY2024 |
FY2025 |
|
|
RM Million |
RM Million |
RM Million |
RM Million |
RM Million |
|
|
Concessions-based services |
60 |
43 |
30 |
23 |
30 |
|
Services rendered (Commercial) |
459 |
518 |
565 |
548 |
618 |
|
Sales of goods (Commercial) |
55 |
37 |
21 |
42 |
14 |
|
Concession-related services / rentals |
124 |
17 |
0.01 |
11 |
0.35 |
|
Blockchain and AI-related services |
- |
- |
128 |
363 |
644 |
|
Financing Receivables |
18 |
22 |
19 |
17 |
13 |
|
Rental and dividend income |
5 |
14 |
12 |
14 |
15 |
|
Total |
722 |
651 |
774 |
1,017 |
1,335 |
|
Source: Zetrix AI, iFast Compilation. Data as of 31 December 2025 |
|||||
Strong Operating Cash Flow May Moderate Refinancing Risk
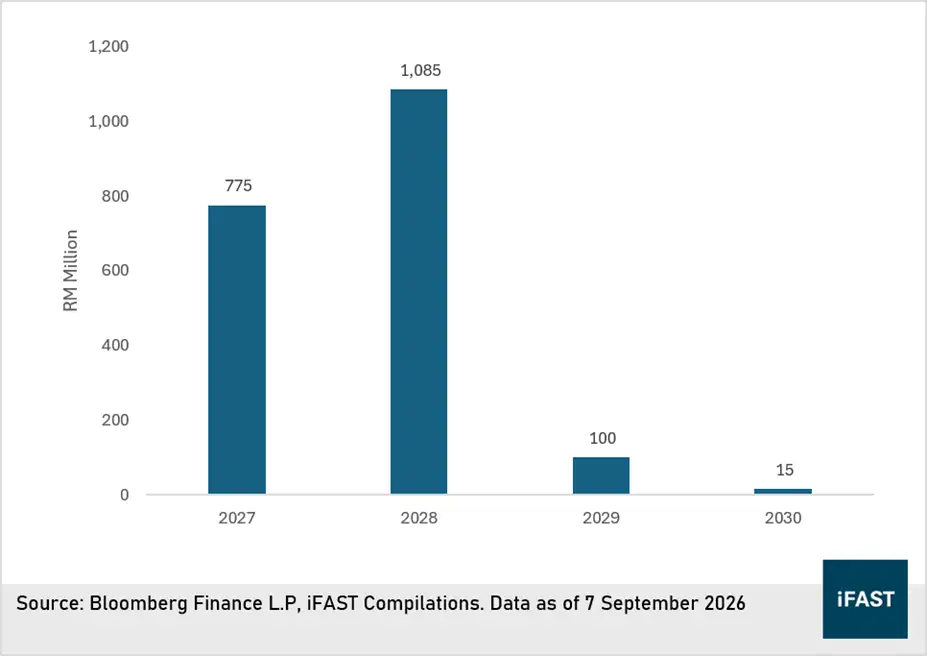
From a credit perspective, the share-price decline does not directly affect Zetrix AI's current debt-servicing capacity. However, the significant insider selling and weaker equity valuation could undermine market confidence and increase perceived risk, potentially making future equity or debt-market funding more challenging and potential more expensive, thereby affecting its refinancing ability. This is a key consideration as Zetrix AI approaches sizeable debt maturities of approximately RM775 million in FY27 and RM1.08 billion in FY28, representing a combined maturity wall of around RM1.86 billion (Chart 2).
Chart 2: Zetrix AI Bond Debt Maturity Profile
Looking at the latest 2Q26 financial results, Zetrix AI has significantly increased its blockchain-related development spending since FY2021, with capitalised development costs rising from RM323 million in FY2021 to RM3.7 billion in 2QFY26. The expansion has been increasingly debt-funded, with total borrowings rising from RM161 million to RM2.2 billion over the same period, while net gearing increased to approximately 38% (Table 3).
Despite the significant increase in development spending and leverage, the Group has demonstrated strong and growing operating cash generation. Net cash from operating cash flow increased from RM121 million in FY2021 to RM982 million in FY25, and remained substantial at RM558 million in 2Q26, indicating a strong underlying ability to generate cash from its operations. While the Group continues to incur substantial investment outflows (resulting in negative free cash flow), this is broadly consistent with its strategy of expanding and developing its blockchain and AI-related businesses.
From a credit perspective, current leverage and interest-servicing capacity remain relatively manageable against the Group's revenue and cash-generating ability. Net debt-to-revenue stood at 1.07 times in 2Q26, while interest coverage remained strong at 11.1 times, indicating comfortable current interest-servicing capacity despite the significant increase in borrowings. The Group's RM982 million FY25 operating cash flow also provides meaningful support against the RM775 million debt maturity due in 2027.
Table 3: Key Credit Metrics
|
FY21 |
FY22 |
FY23 |
FY24 |
FY25 |
2Q26 |
|
|
Development costs - Cash Flow Statement (RM Million) |
243 |
467 |
468 |
662 |
1,030 |
970* |
|
Development cost - Balance Sheet (RM Million) |
323 |
763 |
1,206 |
1,848 |
2,854 |
3,731 |
|
Net Cash from Operating Cash Flow (RM Million) |
121 |
311 |
541 |
860 |
982 |
557* |
|
Net cash used in investing cash flow (RM Million) |
319 |
529 |
800 |
829 |
1,169 |
1,136* |
|
Free Cash Flow (RM Million) |
(160) |
(222) |
67 |
100 |
(57) |
(414) |
|
Total Debt |
161 |
443 |
847 |
1265 |
1,681 |
2,190 |
|
Cash and cash equivalent (RM million) |
89 |
133 |
84 |
374 |
533 |
542 |
|
Net Gearing Ratio (%) |
5% |
20% |
35% |
31% |
31% |
38% |
|
Net debt/revenue (Times) |
0.19 |
0.77 |
1.29 |
1.06 |
0.86 |
1.07 |
|
Interest coverage ratio (Times) |
48.2 |
44.5 |
13.2 |
11.8 |
11.44 |
11.05 |
|
*6 month only Source: Zetrix AI, iFast Compilation. Data as of 30 June 2026 |
||||||
Developments seen on the Zetrix AI front, but the effects are yet to be seen
On 26 February 2026, International Finance Corp (IFC), the private-sector investment arm of the World Bank Group, invested US$40 million (RM156 million) in Zetrix AI through the subscription of 199.5 million new shares, giving it an approximately 2.5% stake. The proceeds will fund the development and expansion of Zetrix’s blockchain-based digital public infrastructure and AI initiatives in Malaysia and ASEAN, while supporting its regional expansion, providing some credibility to the legitimacy of Zetrix’s blockchain venture.
A potential key mitigant to the Group's refinancing risk is the planned Nasdaq listing of its AI Foundation Lab subsidiary through a SPAC business combination. Zetrix AI has indicated that it is targeting completion of the listing by end-2026, while the Group entered into an MOU with Nasdaq-listed Forefront Tech Holdings Acquisition Corp (FTHAC) in May 2026 for a potential business combination.
If successfully completed, the transaction could provide Zetrix AI with access to a larger pool of international capital and potentially unlock the value of its blockchain and AI businesses. Management has also indicated the possibility of transferring some existing debt to the new SPAC-listed entity, which could reduce the Group's refinancing burden. However, the listing and potential debt transfer remain subject to successful completion.
All in One
Overall, Zetrix AI's credit profile remains supported by strong operating cash flow and manageable current interest-servicing capacity. While the monetisation potential of its blockchain and AI ventures remains uncertain, the Group's established commercial services continue to contribute almost half of revenue, providing a more stable earnings and cash flow base. We therefore continue to view the Group's refinancing position as manageable up to the November 2027 bond maturity (Table 4), supported by its strong historical operating cash generation and RM542 million cash balance as of 2Q26, based on the company's financial results. We therefore recommend investors to continue holding the bonds (Table 4).
However, refinancing risk becomes more significant thereafter, given the sizeable FY28 maturity wall of approximately RM1.1 billion, continued investment requirements and potentially higher funding costs amid weaker equity-market confidence. The proposed Nasdaq listing of AI Foundation Lab could provide an additional source of liquidity if successfully completed, but we acknowledge that it is currently only at the Memorandum of Understanding (MOU) stage and therefore remains an uncertain mitigant.
As highlighted in our previous article, we remain cautious on new bond issuances and bonds maturing beyond FY27, given Zetrix AI’s growing exposure to blockchain and token-related activities, which introduces greater earnings volatility. Blockchain adoption remains at an early stage, with limited transparency and visibility into its contribution to sustainable earnings. Meanwhile, token-related income may be non-recurring and remains subject to market sentiment and price volatility. We will monitor the situation and may change our recommendation based on further information.
Previous article: Credit Update: Zetrix Moderate Refinancing Risk Ahead and strategic pivot into Blockchain | Bondsupermart
Table 4: Existing Zetrix Bonds Under Coverage
|
Bonds |
Years to Maturity |
Outstanding Amount (RM million) |
Yield to Maturity |
Credit Rating (RAM) |
|
6M |
215 |
4.5% |
AA- |
|
|
11M |
110 |
4.9% |
AA- |
|
|
1Y2M |
100 |
5.1% |
AA- |
|
|
*Above Fixed Income Paper only Cover 2027 Source: Bondsupermart, iFAST Compilations. Data as of 8 September 2026 |
||||











