• A path towards sustainable profitability: a regulatory clampdown on irrational price war and a renewed focus on profitability provides scope for earnings improvement.
• Entrenched logistics moat: supports the group’s operating efficiency, which, combined with regulatory tailwinds, strengthens the pathway to sustained profitability.
• Net Cash Balance Sheet: supports debt-servicing capacity as the group works its way to sustainable profitability.
• About the bonds: focusing on the short to medium tenor issues (2-5 years), these issues provide decent yield pickup compared to peers of comparable tenors (>50+bps) and compared to sovereigns (>80+bps).
Company Profile
Meituan stands out as China’s leading local services powerhouse. The group offers food delivery services, helps consumers purchase local services from merchants such as hotels, attractions, and transportation, and provides other services and sales, including cloud computing, online marketing, and grocery shopping.
Recent Financial Highlights
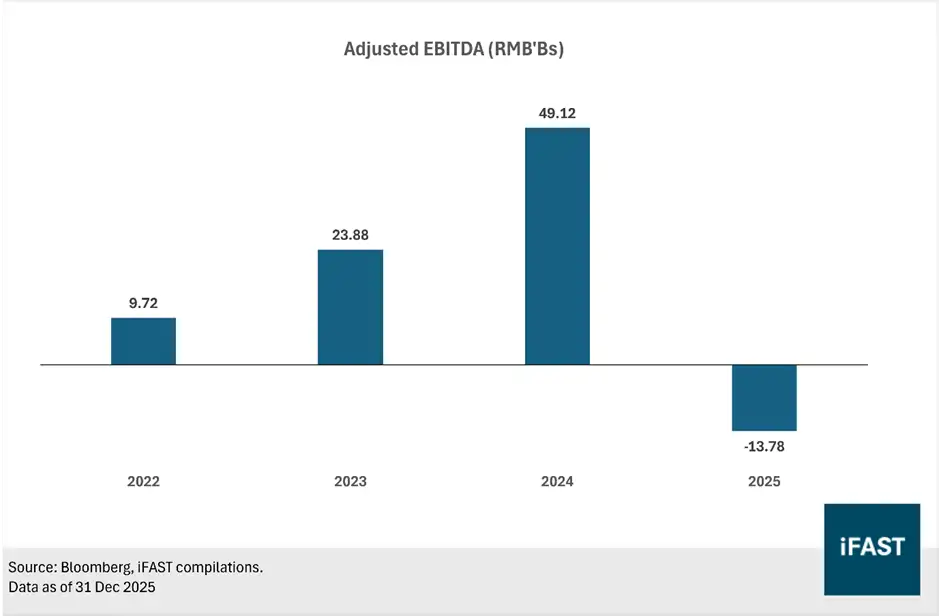
For the year ending 31 December 2025 (FY2025), Meituan reported a lacklustre performance. While the top line held up, growing 8% year on year (YoY) to RMB 364.9b (See Chart 1 below), the focus is that the group swung from profitability to loss-making. Operating income loss was recorded at RMB 25.0b, compared to FY2024’s profit of RMB 36.8b (see Chart 1 below). As shown in Chart 2 below, core operations (EBITDA) followed suit, coming in at a loss of RMB 13.8b, compared to a profit of RMB 49.1b in FY2024.
The main reason for Meituan reporting a disappointing 2025 is due to intense price competition in China, alongside the group’s aggressive global expansion (via its KeeTa brand) in the Middle East and Brazil. For reference, selling and marketing expenses ballooned 60.9% YoY to RMB 102.9b compared to FY2024’s RMB 64.0b.
Chart 1: Revenue growth sustained; operating income swings to loss in 2025
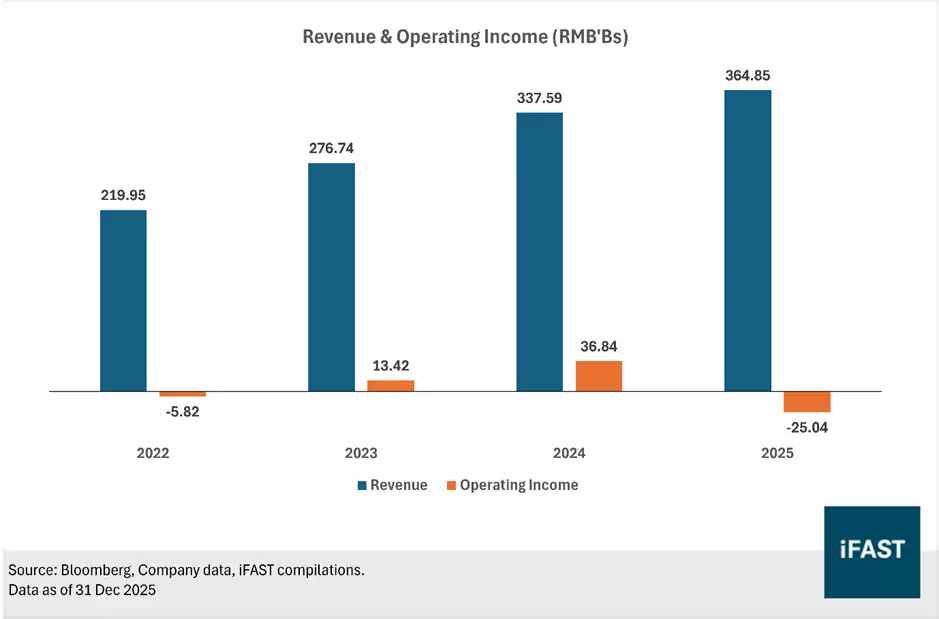
Chart 2: EBITDA swings to loss in 2025 amid price war headwinds
Path towards sustainable profitability
On a more constructive note, China’s regulator recently announced it will clamp down on zero-sum competition and discourage irrational price wars and incentives/subsidies. Hence, over the medium to long term, we expect Meituan to moderate its losses and eventually recover its profitability. That said, this is subject to the condition that all the local players in China abide by the decision to cease competing on price alone and return to rational competition.
Beyond regulatory support, we highlight that Meituan (on its latest conference call) is actively redirecting incentives away from “low-quality”, price-sensitive users toward its high-value member base. This disciplined approach directly moderates losses per order, decoupling revenue growth from subsidy burn. This is evidenced in the group’s improved operating loss margin of (18.1%) in its fourth quarter compared to the (20.7%) operating loss margin in its third quarter. As bond investors, we welcome this renewed focus on the group’s profitability as it will bolster Meituan’s debt-servicing capacity.
Underpinning the group’s sustainable path to profitability is management’s guidance that its Middle East operations (Saudi Arabia) are still expected to reach profitability by the end of December 2026. Additionally, we note that management has expressed a more disciplined approach to global expansion; instead of pursuing growth at all costs, they are now focused on operational refinement and achieving operating profits, ensuring the international segment will contribute positively to earnings.
Looking forward, we expect the regulatory tailwind and Meituan’s own reduction of incentives/subsidies to moderate its core earnings (EBITDA). We note that our base case does not assume a return to FY2024’s peak profitability. Rather, we expect a mean reversion to 2022-2024 normalised levels, a more modest yet credible recovery. Our conservative framing is intentional: it reflects both regulatory execution risk and competitive discipline risk, while still supporting material debt-servicing improvements.
Meituan’s entrenched logistics network adds an element of support for its credit case
Meituan’s formidable logistics network serves as a significant credit strength, underpinning its market dominance and resilience. We highlight that this extensive ecosystem comprises approximately 3.36 million monthly active delivery drivers (per Meituan’s last update in 2024) and partners with roughly 14.5 million active merchants. This vast scale creates substantial barriers to entry for competitors, as replicating such a network demands immense capital and time. The efficient dispatch algorithms, honed over more than a decade, enable a shortened average delivery time of less than 28 minutes, which enhances user satisfaction and merchant loyalty.
We think this operational efficiency is critical for long-term profitability, as it optimises rider utilisation and reduces per-order costs. Combined with the regulatory tailwind and Meituan’s own initiative in reducing subsidies/incentives (highlighted in the previous section), we see a credible path forward to earnings normalisation over the medium term (1-3 years), supporting debt servicing.
Credit Profile
Overall, Meituan’s credit profile has softened for 2025 compared to 2024. Interest coverage (adjusted EBITDA / Gross Finance Costs) swung to negative from 2024’s coverage of 36.7x (see table 1 below) due to the negative EBITDA recorded for 2025, owing to the intense price competition faced in China. That said, we highlight Meituan’s leverage remains low: the group still carries a net cash position of RMB 86.6b (looking at table 1 below, the group consistently carries net cash on its balance sheet over the last few years), providing a decent buffer against its debt obligations as the group progresses towards earnings normalisation. We note that, given the nature of Meituan’s operations, the group has a lot of short-term payables, which inflate its net cash position; nevertheless, the group still has a war chest of cash available.
Looking at the group’s upcoming maturities, we note that RMB 17.2b comes due within the next year. Further out, RMB 63.0b comes due over the next five years. Given the group’s net cash position of RMB 86.6b, we do not expect any difficulty in covering its outstanding debts. While operating and free cash flow are negative for 2025, we expect improvements across both metrics owing to the regulatory tailwind against irrational price war and the improving profitability for its international operations. To put things into perspective (see table 2 below), both operating and free cash flow have been supportive from 2022 to 2024 (pre-delivery war). On the cash flows front, we do not expect new highs, but even a reversion to previous year figures will substantially support Meituan’s ability to meet its interest and debt obligations.
Overall, we expect Meituan’s leverage and coverage to moderate from the poor performance of 2025, trending back towards pre-delivery war figures, which will support the improvement of its credit profile. However, we still caveat that our analysis hinges on execution risk on Meituan’s part, and the general industry complying with China’s regulatory push towards price sustainability.
Table 1: Credit Metrics
|
Credit Metrics |
FY2022 |
FY2023 |
FY2024 |
FY2025 |
|
Ending 31 December 2022 |
Ending 31 December 2023 |
Ending 31 December 2024 |
Ending 31 December 2025 |
|
|
Net Debt / Equity |
NM* |
NM* |
NM* |
NM* |
|
Interest Coverage Ratio (EBITDA / gross finance costs) |
6.0x |
16.8x |
36.7x |
(7.3x) |
|
*NM, as the group has a net cash position Data as of 31 December 2025. Source: Bloomberg, company data, iFAST compilations. |
||||
Table 2: OCF and FCF over the years have been decent, except in 2025
|
Cash Flow Metrics (RMB’billions) |
FY2022 |
FY2023 |
FY2024 |
FY2025 |
|
Net Operating Cash Flow (RMB’billions) |
11.41 |
40.52 |
57.15 |
(13.82) |
|
Less: Capex (RMB’billions) |
(5.73) |
(6.88) |
(11.00) |
Undisclosed |
|
Free Cash Flow (RMB’billions) |
5.68 |
33.64 |
46.15 |
Negative |
|
Data as of 31 December 2025 Source: Company data, iFAST compilations. |
||||
Table 3: Bond recommendations
|
Issue |
Issuer |
Ask Price |
Yield to Worst (%) |
Years to maturity |
Credit Rating (S&P / Fitch / Moody’s) |
|
Meituan |
99.92 |
4.54% |
1.98 |
BBB+ / BBB+ / Baa1 |
|
|
Meituan |
99.60 |
4.75% |
3.48 |
BBB+ / BBB+ / Baa1 |
|
|
Meituan |
92.43 |
4.93% |
4.56 |
BBB+ / BBB+ / Baa1 |
|
|
Meituan |
97.59 |
5.04% |
5.00 |
BBB+ / BBB+ / Baa1 |
|
|
Alibaba Group Holding Limited |
102.56 |
4.18% |
4.13 |
A+ / A / A1 |
|
|
Alibaba Group Holding Limited |
90.62 |
4.29% |
4.84 |
A+ / A / A1 |
|
|
Baidu Inc |
96.69 |
4.34% |
4.00 |
-/ A / A3 |
|
|
Tencent Holdings Limited |
99.65 |
4.10% |
3.01 |
A+ / A / A1 |
|
|
Tencent Holdings Limited |
93.29 |
4.17% |
4.15 |
A+ / A / A1 |
|
|
Weibo Corporation |
94.32 |
4.87% |
4.25 |
BBB / - / Baa2 |
|
|
Xiaomi Best Time International Limited |
95.70 |
4.55% |
4.06 |
BBB / BBB+ / Baa1 |
|
|
Source: Bloomberg, Bondsupermart, iFAST compilations. Data as of 9 April 2026 |
|||||
Overall, we expect Meituan’s credit profile to remain decent and moderately improve moving forward. Our analysis depends on all players complying with China’s regulatory requirements, increasing profitability across its international operations, and the group’s strong net cash position.
In Table 3 above, we compare Meituan’s short to medium tenor bonds (2-5 years) against its closest technology peers (do note the difference in credit ratings). We find that Meituan’s bonds provide a decent yield pickup of >50+ bps against comparable peers of similar tenors, partially due to the group’s poor 2025 performance (which we expect to improve moving forward). Against comparable sovereigns of similar tenors, we highlight that Meituan’s outstanding bonds provide an attractive spread of >80+bps.
In sum, we believe Meituan’s outstanding bonds provide decent income for investors comfortable with the execution risk involved as the group undertakes proceedings to moderate its losses and eventually swing back to profitability.
Disclosure: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds NIL positions in the abovementioned securities. The analyst who produced this report holds NIL positions in the abovementioned securities. This research report was prepared with the assistance of artificial intelligence (AI) tools. iFAST Financial Pte Ltd does not rely exclusively on AI for content generation; the content of this report – including all investment theses, ratings, price targets and conclusions – has been independently reviewed and verified by the research analyst(s) to ensure accuracy and professional integrity.