- AAREIT for 1H22 reported gross revenues of SGD 65.2m and NPI of SGD 47.7m, a YoY increase of 13.0% and 19.4% respectively.
- Since 2011, NPI for AAREIT grew at a compound annual growth rate (“CAGR”) of 5.1%.
- On 15 November 2021, AAREIT announced the completion of an acquisition of a freehold property located at 1 Woolworths Way, Australia for approximately AUD 463.25m.
- AA REIT obtained commitments of up to SGD 220 m and AUD 100 m to refinance several of its secured debt facilities due in 2021 and 2022.
- With its recurring stable rental income and cash flows, we think AAREIT’s 5.375% perps will be able to provide stable and reliable cash flows to its investors for the next few years.
Demand for industrial spaces in Singapore continues to pick up even with Covid-19. Tenants for these spaces are from essential sectors such as consumer staples and the impact of Covid-19 did not have a significant impact in demand for these goods and services.
Looking at the new ‘normal’ where potential new variants and further lockdowns will continue to impact our daily lives, we think industrial REITs will still provide stable and reliable cash flows to investors during and after the pandemic.
About AIMS APAC REIT (AAREIT)
AAREIT is an industrial REIT with properties in Singapore and Australia. As of 15 November 2021, AAREIT has 29 properties in its portfolio, 26 in Singapore and 3 in Australia. AIMS Financial Group (“AIMS”) is the sole sponsor of AA REIT and is a diversified financial service and investment group headquartered in Sydney, Australia.
The sponsor, AIMS has vast experience in funds management and property investment, previously turning around distressed MacarthurCook during the Global Financial Crisis (“GFC”) in 2009. AIMS successfully turned around the MacarthurCook Industrial REIT (now known as AIMS APAC REIT) when it was in distress during the GFC as the REIT entered into an acquisition without first securing finance. AIMS grew the REIT from a market capitalisation of SGD 60.2m in 2009 to SGD 1,030m in 2021.
1H22 Financial Results
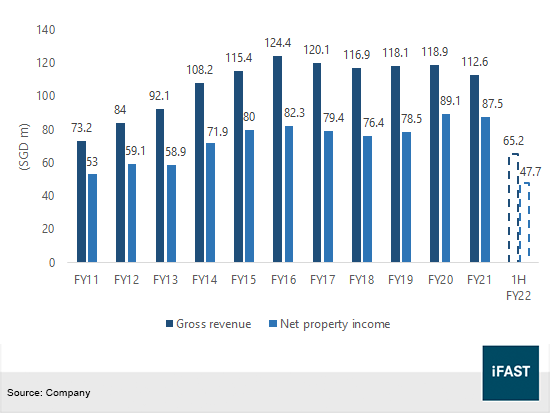
During the 6 months financial results ended 30 September 2021 (“1HFY22”), AAREIT reported gross revenues of SGD 65.2m, a 13.0% increase year-on-year (“YoY”) from SGD 57.7m. Net property income (“NPI”) also saw 19.4% YoY increase from SGD 40.0m in 1HFY21 to SGD 47.7m in 1HFY22.
The increase in gross revenue was due to its recent acquisitions of 7 Bulim Street (acquired in October 2020), as well as higher rental and recoveries for properties at 20 Gul Way, 8 & 10 Pandan Crescent and 541 Yishun Industrial Park A.
Since 2011, NPI for AAREIT grew at a compound annual growth rate (“CAGR”) of 5.1%. Despite the pandemic affecting rental income, NPI have largely remained stable. As seen from Figure 1, NPI dipped slightly during FY21 but is on track to beat FY20 numbers.
Figure 1: Gross revenues and NPI
On 15 November 2021, AAREIT announced the completion of an acquisition of a freehold property located at 1 Woolworths Way, Australia (“Woolworths Property”) for approximately AUD 463.25m (~SGD 454.0m). The acquisition was funded by a combination of debt financing, acquisition fee units and also from the net proceeds raised from the issuance of AAREIT 5.375% Perpetual Corp (SGD).
The master tenant of the Woolworths Property is Woolworths Group Limited (“Woolworths”), a publicly-listed company on the Australian Securities Exchange. They are a major retail operator in Australia and New Zealand with 3,357 stores with business operations in Australian Food, New Zealand Food and a retail chain, Big W.
Additionally, the Woolworths lease has a fixed rental escalation of 2.75% per annum which will provide AAREIT rental growth throughout the balance lease term of 10 years.
Along with the proposed acquisition of 315 Alexandra Road as mentioned in our previous article on AAREIT (See AIMS APAC REIT launches SGD NC5 Perpetual Notes at 5.50% IPG), AAREIT’s portfolio of properties will increase to 30 properties in Singapore and Australia.
Demand for E-commerce
E commerce will be one of the main drivers for these logistics and warehouse spaces as more users start using these services. According to a report by Google, Temasek and Bain, e-commerce in Singapore is expected to grow at a CAGR of 16% from 2021 to 2025. The pandemic brought about many new users to e-commerce as Covid-19 related lockdowns prevented people from doing their shopping in malls. As seen from Figure 2, e-commerce product and services such as apparels, groceries and electronics, saw significant gain in users during 2020 and 2021.
Figure 2: % of internet users across digital services
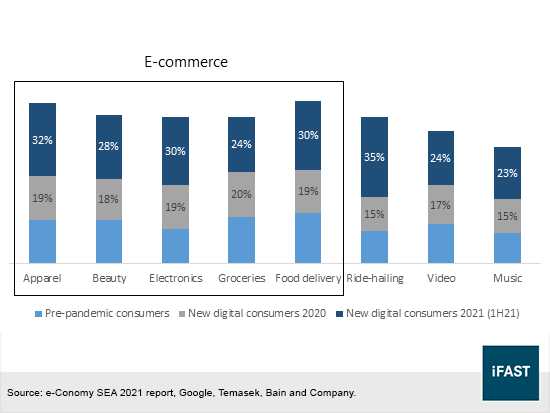
Referring to the gain in users during the pandemic, we think e-commerce will continue to grow and be resilient during pandemic related lockdowns or restrictions. Adjusting to the new ‘normal’ where potential new variants will continue to impact our economy and unexpected lockdowns will occur, e-commerce will be largely unaffected as these businesses do not require physical stores to do their daily operations.
Thus, we think that demand for warehouse and logistics spaces will be fuelled mainly by the growth of e-commerce and therefore providing industrial REITs with rental and cash flow stability as their operations will not be largely impacted by the pandemic.
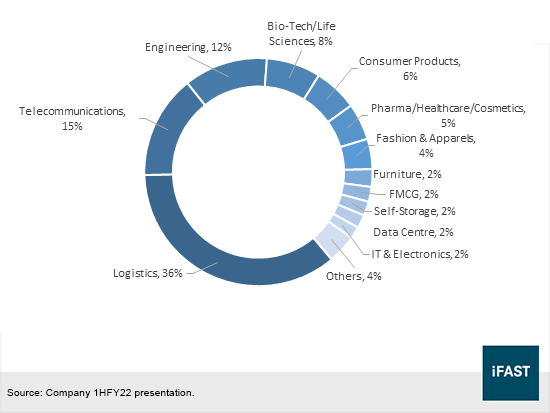
AAREIT will be able to capture this growth and demand for e-commerce as tenants look for spaces to expand or set up operations in Singapore. 36% of AAREIT’s current tenants are from the logistics industry (Figure 3). Within its property portfolio, 50.2% of its properties are logistics and warehouse spaces.
Figure 3: AAREIT’s tenant base
Additionally, portfolio occupancy rate for the REIT is also high at 97.3%. By comparison, the JTC’s industry average occupancy rate was 90.1% as of 2Q 2021. Weighted Average Lease Expiry (“WALE”) for AAREIT was 3.98 years and this is in line with most other industrial REITS. There were 13 renewal leases signed in 2Q22 and the weighted average rental increase was 2.1%.
Liquidity and credit profile
AAREIT’s liquidity improved with cash and cash equivalents increasing to SGD 108.3m from the issuance of AAREIT 5.375% Perpetual Corp (SGD). Additionally, the REIT has access to available undrawn committed facilities of SGD 151.8m, which will be more than enough to repay its fixed rate notes due in March 2022.
As seen in Figure 4, AA REIT obtained commitments of up to SGD 220 m and AUD 100 m to refinance several of its secured debt facilities due in 2021 and 2022 while using its available credit facility of SGD 151.8m to repay its March 2022 notes. Weighted average debt maturity on a pro forma basis will increase to 2.7 years.
Figure 4: Pro-forma debt maturity profile of AA REIT
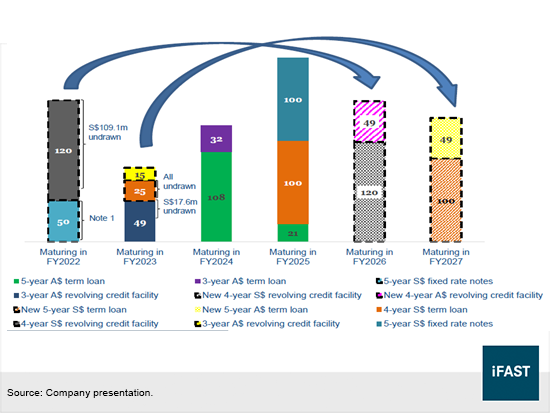
Table 1: Credit profile
|
1H FY2022 |
1H FY2021 |
|
|
Cash and cash equivalents ( SGD m) |
108.3 |
11.2 |
|
Total Debt (SGD m) |
467.3 |
593.8 |
|
Weighted average debt maturity (years) |
2.1 |
2.6 |
|
Interest coverage ratio (x) |
4.5 |
3.7 |
|
Aggregate leverage ratio (%) |
24.7 |
33.6 |
| Source: Company. | ||
We think the credit and liquidity profile of AAREIT is decent with an interest coverage ratio of 4.5x (3.3x when including perpetual notes). Aggregate leverage (total borrowings/total assets) was 24.7%. Aggregate leverage is expected to increase from the completion of Woolworths Property but calculated leverage will still be below the regulatory requirements of 50%.
Recommendation
Table 2: AAREIT bonds
|
Bond name |
Coupon (%) |
Maturity/ Call date |
Ask Price |
Ask Yield to Worst (%) |
|
AAREIT 5.375% Perpetual Corp (SGD) |
5.375 |
1 Sep 2026 |
102.02 |
4.88 |
|
AAREIT 5.650% Perpetual Corp (SGD) |
5.650 |
14 Aug 2025 |
103.73 |
4.50 |
|
AAREIT 3.600% 12Nov2024 Corp (SGD) |
3.600 |
12 Nov 2024 |
102.01 |
2.85 |
|
AAREIT 3.600% 22Mar2022 Corp (SGD) |
3.600 |
22 Mar 2022 |
100.46 |
0.81 |
| Source: Bloomberg Finance L.P., iFAST compilations. Data as of 19 January 2022. | ||||
From the available bonds issued by AAREIT, the AAREIT 5.375% Perpetual Corp (SGD) looks the most attractive providing an indicative ask yield to worst (“YTW”) of 4.88%. The 5.375% perps provide a 38 basis point step up from the AAREIT 5.650% Perpetual Corp (SGD) for a difference of ~1 year in their call dates.
We think from its recent acquisitions and early refinancing of its expiring debt in FY22 and FY23, the management has taken proactive steps to manage capital well within the REIT. Along with its new acquisitions and warehouses and logistics properties, the REIT is underpinned by e-commerce which we think will be a resilient industry during the pandemic. With its stable rental income and cash flows, we think AAREIT’s 5.375% perps will be able to provide stable and reliable cash flows to its investors for the next few years.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in AAREIT 5.375% Perpetual Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!