Important Events
- On Thursday,
the European Central Bank (“ECB”) announced its monetary policy decisions and
revised the purchase schedule for its Asset Purchase Programme (“APP”). Monthly
net purchases under the APP will amount to EUR 40b in April, EUR 30b in May and
EUR 20b in June. The Governing Council will conclude net purchases under the
APP in the third quarter of 2022, given if data support the expectation that
the medium-term inflation outlook will not weaken even after the end of its net
asset purchases.
For key ECB interest rates, the ECB has kept the interest rate on the main refinancing operations and the interest rates on the marginal lending facility and the deposit facility unchanged at 0.00%, 0.25% and -0.50% respectively. In regards to ECB’s Pandemic emergency purchase programme (“PEPP”), the ECB will discontinue its net asset purchases under the PEPP at the end of March 2022. ECB intends to raise key ECB interest rates gradually after the end of the Governing Council’s net purchases under the APP.
In the press conference following the monetary policy decisions, ECB’s Christine Largarde said that the ECB has revised GDP growth downwards for the near term due to the war in Ukraine. The ECB projects the economy growing at 3.7% in 2022, 2.8% in 2023 and 1.6% in 2024.
Speaking on inflation, inflation in the Eurozone increased to 5.8% in February, and the ECB expects inflation to rise further in the near term. Energy prices surged by 31.7% in February as well as food prices. Largarde mentioned that there will be further pressure on some food and commodity prices owing to the war in Ukraine.
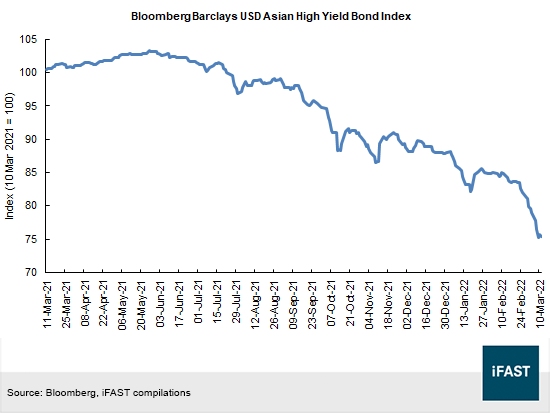
Asian High Yield Bond Index
- The Barclays USD Asia High Yield Bond Index decreased 4.5% for the week ended 11 March 2022.
- On Wednesday, Jiayuan International Group announced that the Group will arrange all necessary funds to trustee’s bank account to repay outstanding principal amount and accrued interest of the USD bond maturing in March 2022.
- On Wednesday, CIFI Holdings announced that the Group deposited all necessary funds into the designated bank account of China Securities Depository and Clearing Corporation Limited to repay outstanding principal amount and accrued interest of the RMB bond mature on 21 March 2022.
- On Thursday, Longfor Group reported its monthly contracted sales. In February, the group achieved total contracted sales of RMB6.08 billion, and contracted sales area of 374 thousand square meters. In addition, the Group has acquired one new land with attributable GFA of 101 thousand square meters and cost of acquisition on attributable basis amounting to RMB 0.87 billion.
Interest Rates and Currencies
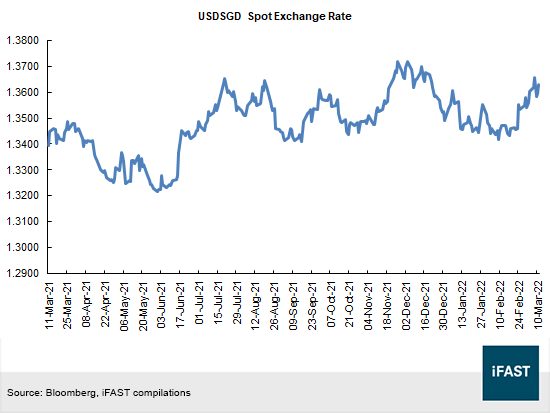
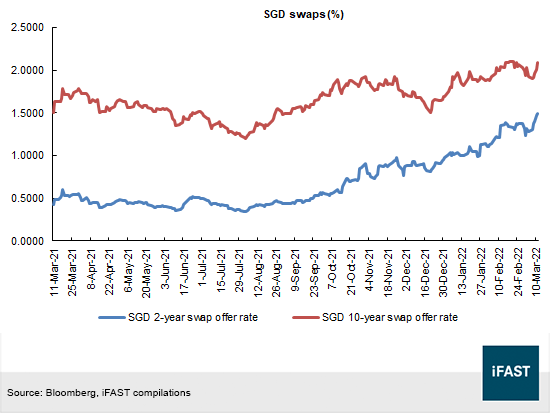
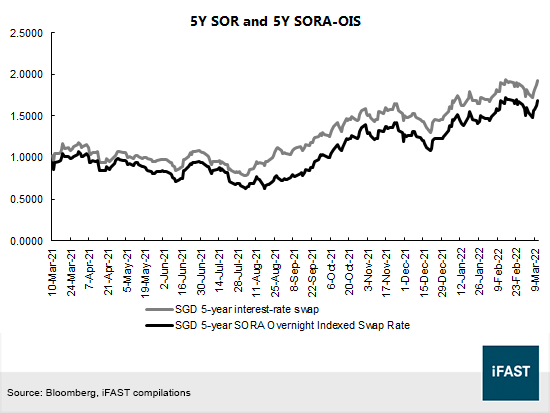
- The US dollar appreciated against the Singapore dollar last week with the USD/SGD currency pair ending at 1.3629. The 2-year SGD Swap Offer Rate (“SOR”) increased by 20 basis points (“bps”) to 1.4875 while the 10-year SGD SOR increased by 16 bps for the week to 2.0900%. Both the 5-year SOR and the 5-year SORA-OIS increased by 15 bps to 1.9250% and 1.6900% respectively.
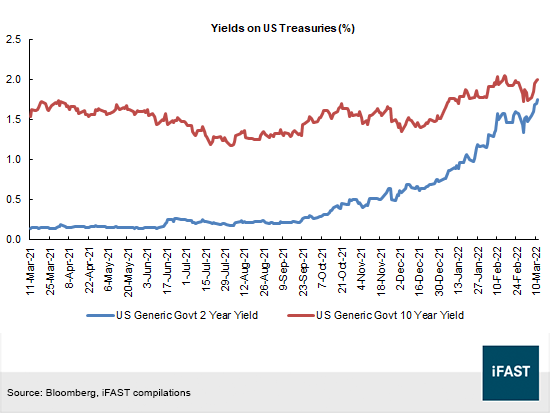
- Last week, the yield of 2-year US Treasuries (“UST”) and the 10-year UST increased 27 bps and 26 bps to 1.7480% and 1.9917% respectively. Consumer price index (“CPI”) for the US increased 0.8% in February. Over the last 12 months, CPI for all items index increased by 7.9% before seasonal adjustment. Gasoline, shelter and food was the largest contributors to the increase in CPI.
Corporate Updates and New Issues
- On Tuesday, Singapore’s Housing and Development Board (“HDB”) announced that they will be tapping the bond market to issue its inaugural green bond at a final price guidance of 1.845%. The SGD bond is senior unsecured with a tenor of 5 years, maturing in March 2027. Proceeds from this bond offering will be used to finance or refinance HDB’s Eligible Green Projects under the project category of Green Buildings, which is in line with its Green Finance Framework. This includes the development of new residential and non-residential projects that are planned to achieve the BCA Green Mark certification of Gold Plus or above. HDB will allocate these proceeds to Eligible Green Projects on a portfolio basis no later than 2 years from the date of issuance, subject to unforeseen circumstances and market conditions. Investors who are interested may read the new issue view here.
- On Wednesday, Mapletree North Asia Commercial Trust (“MNACT”) announced that Mapletree North Asia Commercial Treasury Company (HKSAR) Limited has fully redeemed SGD 100m in principal amount of its 2.43% Notes due 9 March 2022.
- On Friday, Olam International Limited (“Olam”) provided an update on the settlement date for its exchange offer and consent solicitation memorandum dated 18 January 2022. The settlement date is expected to be on 23 March 2022 and on the settlement date, Olam will pay the relevant Early Consent Fee or Expiration Time Consent Fee and will deliver the Exchange Consideration to the relevant holders.
- On Friday, Ezion Holdings Limited (“Ezion”) announced that the Liquidators of the Company is intending to convene a meeting of the creditors of Ezion to address the following: 1) an update to creditors on the status of liquidation of Ezion; 2) appointing a committee of inspection, if thought fit; and 3) any other business. The Creditors’ Meeting will be held on 22 March 2022 at 2pm. To attend the meeting, a creditor must submit the Proof of Derbt Form, the Proxy Form and the Confirmation of Details to Attend Meeting to the Liquidators by 21 March 2022, 4pm.
- This morning, Cromwell EREIT Management Pte. Ltd., the manager of
Cromwell European REIT (“CEREIT”) provided an update on CEREIT’s business in
Europe in relation to the Russia-Ukraine crisis. More than 85% of CEREIT’s
European portfolio is located in Western Europe with about 10% in Poland and 2%
in Slovakia, two countries that border Ukraine. 2% of CEREIT’s leases in Poland
and Slovakia are expiring in the near term.
No CEREIT counterparties have been identified to be on any sanctions list and majority of CEREIT’s tenant-customers in Poland and Slovakia are multinational companies such as European banks, global pharmaceutical companies as well as technology companies. Amongst the tenant-customers in Poland, 8 so far have some business exposure to Russia with most still assessing the impact. One tenant-customer in Poland is an importer of coal mined by a Russian company, domiciled in Switzerland and occupies ~400 sqm out of 1.8m sqm in CEREIT’s portfolio.
The manager announced that there is no immediate impact on CEREIT’s operation across its portfolio and will closely monitor the rapidly evolving situation in Russia and Ukraine.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!