Receive first-hand news on the latest bond issues, credit updates and special events when you join us on our Telegram channel at https://t.me/bondsupermart!
Important Events
- On Monday, the Monetary Authority of Singapore (MAS) released its Monetary Policy Statement for January 2024. It made no changes to its key policy settings, by maintaining the prevailing rate of appreciation of the S$NEER policy band and making no changes to the width and level at which it is centred. MAS expects the Singapore economy to strengthen in 2024 with growth becoming more broad-based. MAS also expects core inflation to remain elevated in the earlier part of the year, partly due to the one-off impact of the 1pp GST hike this year and an increase in the carbon tax; however, it also expects core inflation to decline gradually and step down by 4Q24.
- On Tuesday, Eurostat released data for Eurozone GDP. Advance estimates for Eurozone GDP growth came in at 0.0% QoQ and 0.1% YoY in 4Q23, while analysts had previously forecast a -0.1% QoQ contraction and 0.1% YoY expansion in 4Q23. Germany was a lag on the region’s growth, recording a -0.3% QoQ and -0.2% YoY contraction; in contrast, countries like Portugal (0.8% QoQ / 2.2% YoY) and Spain (0.6% QoQ / 2.0% YoY) helped the Eurozone likely avoid a recession.
On Wednesday, Eurostat released data for Eurozone CPI inflation. Flash estimates for January 2024 indicated that CPI inflation was 2.8% YoY, while core CPI inflation was 3.3% YoY. These figures came in slightly higher than consensus expectations of 2.7% and 3.2% YoY respectively. The ‘food, alcohol, and tobacco’ sub-category continued to be a large driver of inflation, with prices there rising by 5.7% YoY. - On Wednesday, the Australian Bureau of Statistics released data on CPI inflation. 4Q23 CPI inflation was reported at 4.1% YoY, much lower than both consensus expectations of 4.3% as well as the previous quarter’s reading of 5.4%. Some sub-categories which saw a large increase in prices were alcohol and tobacco (6.6% YoY), and housing (6.1% YoY).
- On Wednesday, Statistics Canada released data on GDP growth. Canada’s GDP grew by 0.2% MoM in November 2023, slightly quicker than analyst estimates of 0.1% MoM. Goods-producing industries led the way in November with a 0.6% MoM growth compared to service-producing industries’ 0.1% MoM growth. Advance estimates by Statistics Canada also indicate that GDP likely grew by 0.3% MoM in December 2023, and 1.5% in 2023 as a whole. Official estimates for 2023 will be available on 29 February 2024.
- On Thursday, the US Federal Reserve opted to hold policy rates steady, with the target range remaining at 5.25% to 5.50%. It also issued its yearly statement on longer-run goals and monetary policy strategy, where it reaffirmed its commitment to anchor longer-term inflation expectations at 2%.
On Sunday evening US time (Monday morning SG time), Fed Chairman Powell gave an interview with CBS News, where he continued to push back against a policy rate cut in the Fed’s March meeting.
Asian High Yield Bond Index
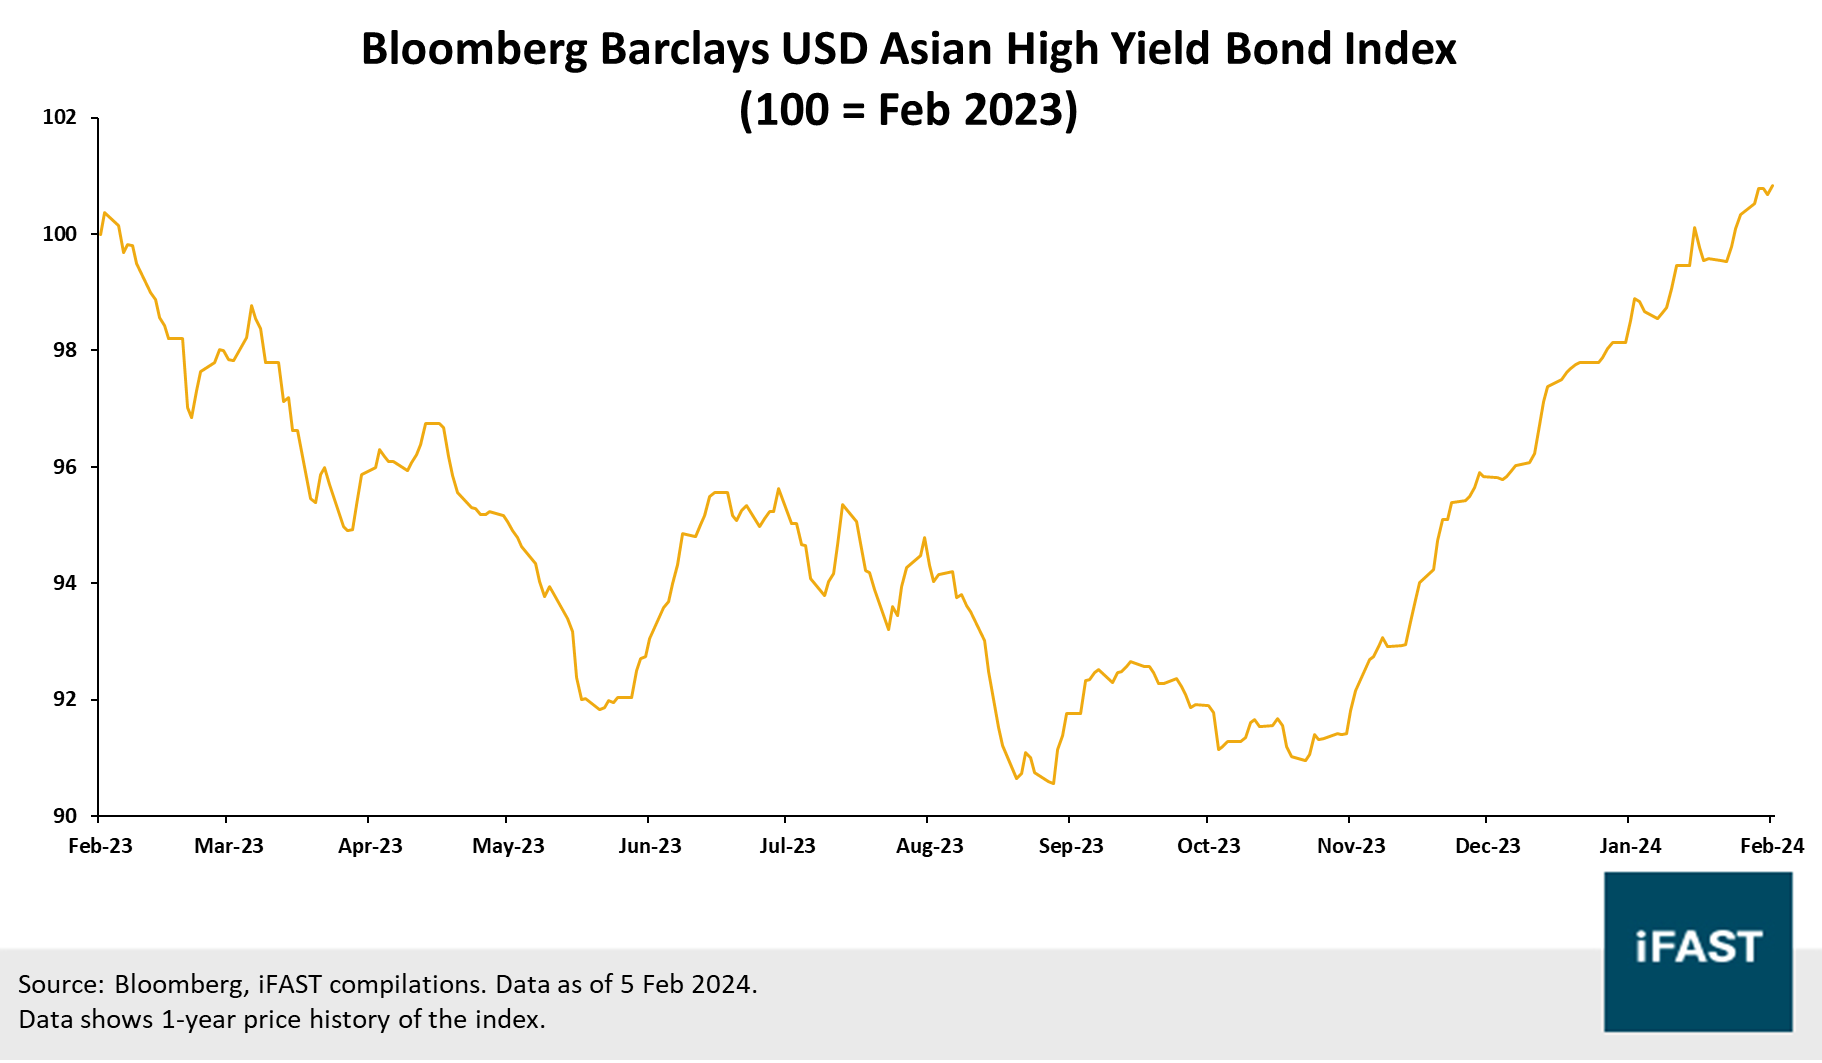
- The Barclays USD Asia High Yield Bond Index rose by 0.48% for the week ended 5 February 2024.
- On Monday, Evergrande was ordered to be wound up by the Hong Kong High Court as it has been unable to offer a concrete restructuring plan for more than 2 years after defaulting on its offshore debt.
- On Thursday, Jiayuan’s liquidators announced they have received more than RMB 30 billion in claims. They believe that it is complicated to raise the funds required for the restructuring but they are working to seek support from creditors to ensure the success of its restructuring.
- On Friday, China South City proposed to sell around 30.6% stake in CSC Xian via public tender to repay debts.
Interest Rates and Currencies
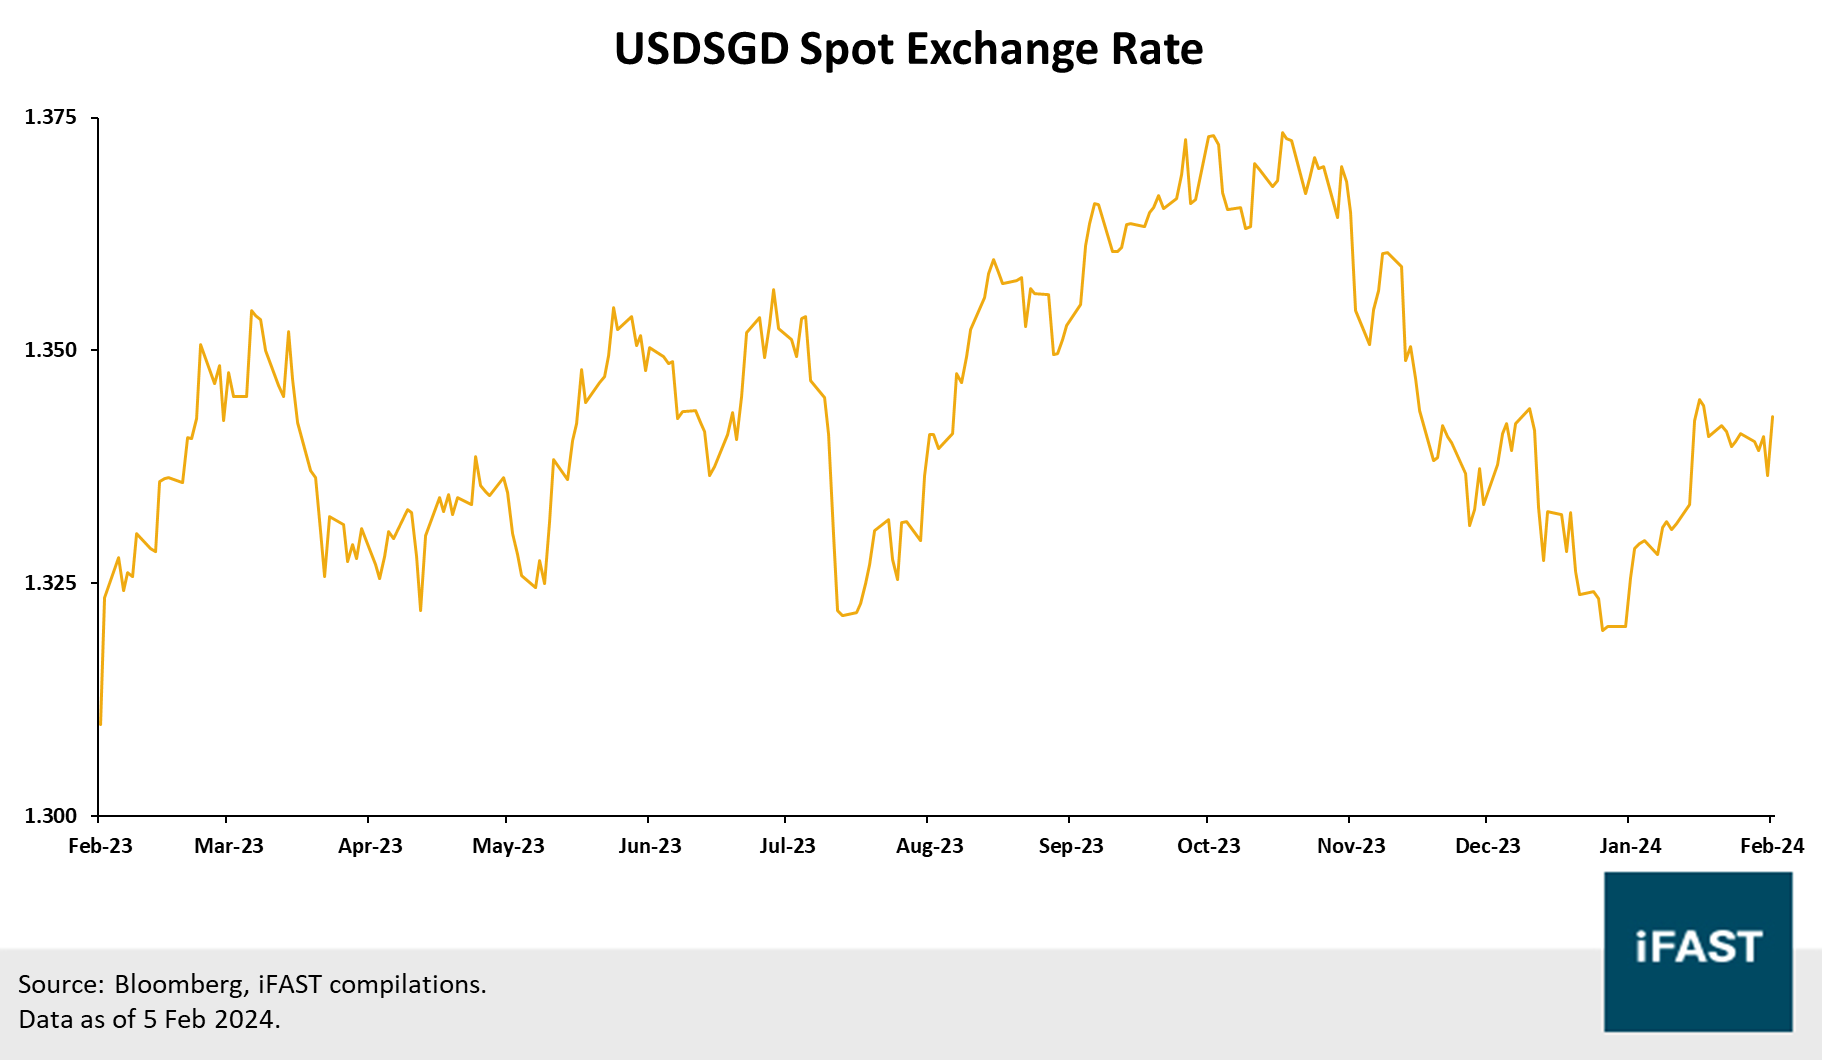
- The US Dollar (USD) appreciated against the Singapore Dollar (SGD) last week by 0.13%, with the USDSGD currency pair closing at 1.3429.
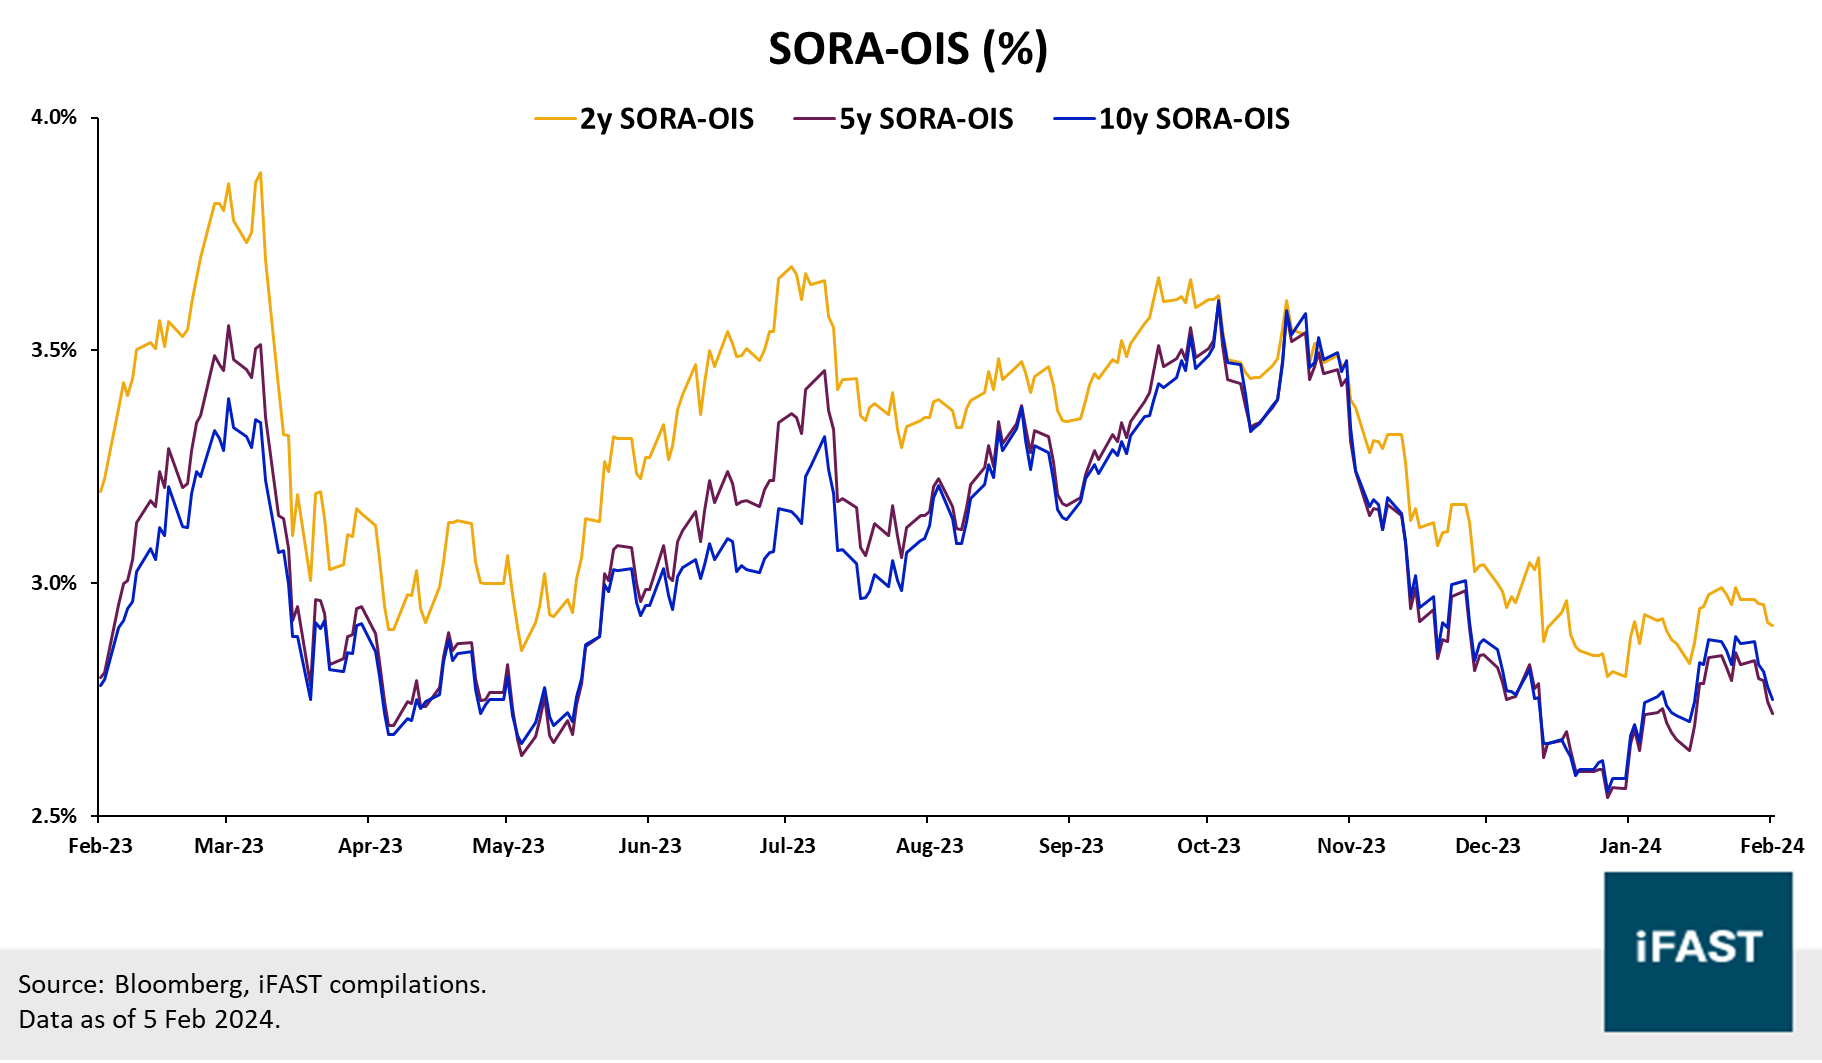
- The 2-year Singapore Overnight Rate Average-Overnight Index Swap (SORA-OIS) decreased by -6 bps to 2.9095%, the 5-year SORA-OIS decreased by -11 bps to 2.7200%, and the 10-year SORA-OIS decreased by -12 bps for the week to 2.7500%.
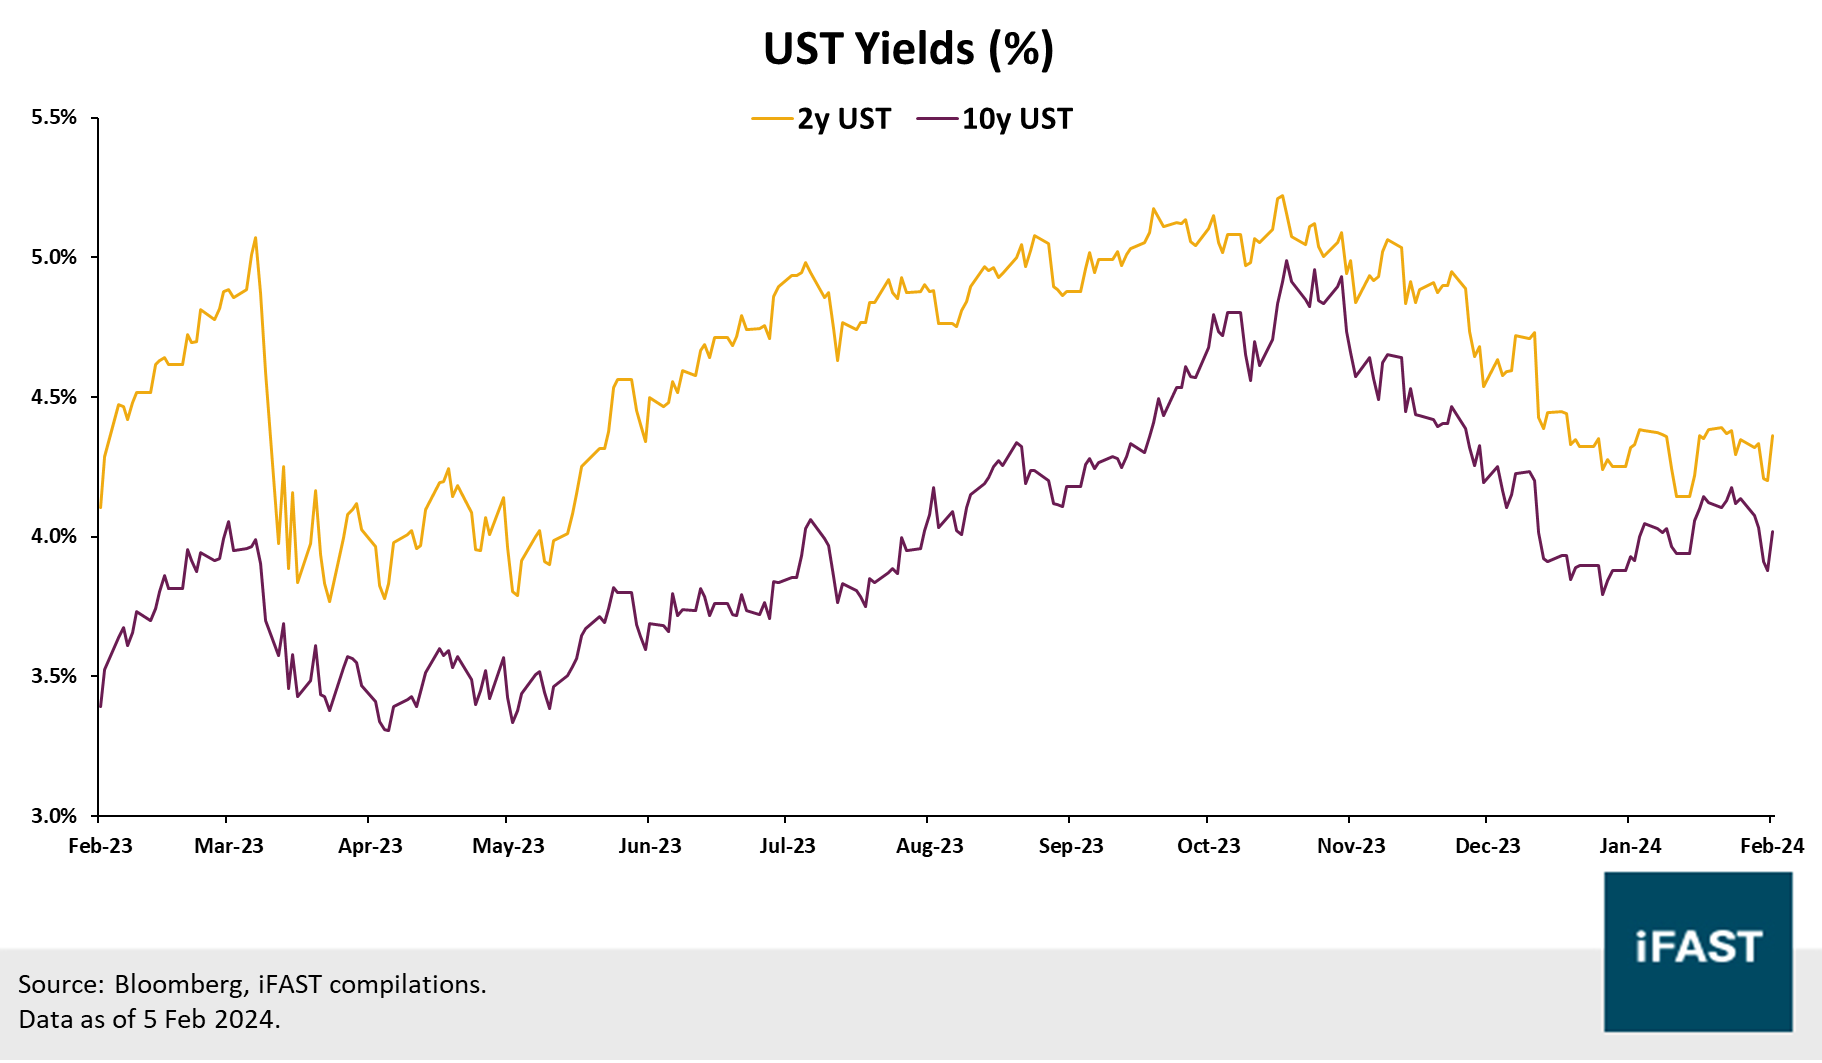
- The yield on 2-year US Treasuries (USTs) increased by 1 bps to 4.3638% while the yield on 10-year USTs decreased by -12 bps to 4.0199%.
Corporate Updates and New Issues
- On Monday, Mapletree Logistics Trust (MLT) announced that HSBC Institutional Trust Services (Singapore) Limited, in its capacity as MLT’s Trustee, has entered into a Purchase Agreement with an unrelated third party for the proposed divestment of 73 Tuas South Avenue 1 in Singapore at a sale price of SGD 16.8m. The proposed divestment is expected to be completed by FY23/24 and is not expected to have a material impact on MLT’s net asset value and net property income for FY23/24.
- On Tuesday, Temasek Financial (I) Limited announced that it will be issuing offshore RMB 750m 3.20% Guaranteed Notes due 2029. These bonds will be unconditionally and irrevocably guaranteed by Temasek Holdings (Private) Limited. These bonds are expected to be issued on 6 February 2024 and listed on SGX on 7 February 2024.
- On Wednesday, CapitaLand Investment Limited (CLI) announced that it has formed an RMB 2.4b joint venture with AIA Life Insurance (AIA), to recapitalise Capital Square Beijing, a Grade A office building in Beijing, China. Under this partnership, CLI will divest a 95% stake in Capital Square Beijing to AIA and hold the remaining 5% stake.
- On Wednesday, Lippo Malls Indonesia Retail Trust’s (LMIRT) manager announced that LMIRT’s wholly-owned subsidiary PT Cibubur Utama (PT CU) has entered into a cooperation agreement with Perusahaan Umum Daerah Pembangunan Sarana Jaya to extend the term of PT CU’s right to operate Cibubur Junction, which now expires on 29 July 2045. The total value of this cooperation agreement is approximately IDR 254b (approximately SGD 21.6m). In addition, LMIRT will pay its sponsor (PT Lippo Karawaci Tbk) IDR 3.1b (about SGD 0.26m) for its assistance in obtaining this extension, as well as its legal advisors IDR 3.0b (about SGD 0.25m).
On Wednesday, LMIRT’s manager also announced that Fitch has upgraded LMIRT’s long-term issuer default rating to CC from C. Its senior unsecured notes due 2024 and 2026 have also been upgraded to CC from C. The rating reflects Fitch’s view that LMIRT is unlikely to raise sufficient funding to repay the remaining USD 138.4m of unsecured notes maturing on 19 June 2024 at par value. - On Wednesday, STT GDC Pte. Ltd. announced that the issuance of SGD 50m 5.7% sustainability-linked perpetuals, to be consolidated and form a single series with the existing SGD 450m 5.7% sustainability-linked perpetuals, was completed on 31 January 2024.
- On Wednesday, Koh Brothers Group Limited announced that the Group is expected to report a net loss for the full financial year ended 31 December 2023. Further details will be disclosed when it announces its FY23 unaudited financial results later in February 2024.
- On Thursday, Hatten Land Limited announced that it has received a notice of default dated 30 January 2024 from the solicitor representing Haitong International Financial Products (Singapore) Pte. Ltd. related to the USD 20.0m convertible loan extended to the company on 21 May 2020. This loan facility is secured by a corporate guarantee from a subsidiary in Malaysia and a charge of over 760m shares in the company, as well as 345 retail units of the group and personal guarantees by certain directors of the company.
- On Thursday, E-LOG’s manager also announced that E-LOG’s wholly-owned subsidiary ESR -LOGOS REIT INV3 Pte. Ltd. has entered into a subscription agreement with ESR Japan Income Fund, SCSp, concerning E-LOG’s investment of USD 70.0m in ESR Japan Income Fund.
- On Friday, CapitaLand Ascott Trust (CLAS) announced that it is divesting Citadines Mount Sophia Singapore to an unrelated third party for SGD 148m, at 19.4% above book value. Net proceeds of the divestment are expected to be about SGD 138.6m. The exit yield is about 3.2% and CLAS will recognise a net gain of about SGD 14.6m. The divestment is expected to be completed in 1Q24.
- On Friday, DBS Group Holdings Ltd announced that it will be merging equity capital markets, brokerage DBS Vickers, and DBS Digital Exchange, with its existing Treasury Markets business, with the new group to be renamed Global Financial Markets. This will take effect on 1 March 2024.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!