Receive first-hand news on the latest bond issues, credit updates and special events when you join us on our Telegram channel at https://t.me/bondsupermart!
Important Events
- On Tuesday, the Bank of Japan announced that Japan's PPI inflation was 0.0% YoY and 0.3% MoM for December 2023, higher than expectations of -0.3% YoY and 0.0% MoM respectively. However, the latest YoY reading still marked the 12th consecutive month of a deceleration in inflation, and was the lowest reading in almost three years (since February 2021). The lumber/wood and utilities sub-segments saw the largest declines in producer prices, at -15.5% YoY and -27.6% YoY respectively.
On Friday, Japan’s Ministry of Internal Affairs and Communications released data on CPI inflation. CPI inflation decelerated to 2.6% YoY in December 2023 from 2.8% YoY in the previous month, marking its lowest reading since July 2022. Core CPI excluding fresh food also slowed to 2.3% YoY from 2.5% YoY, while core CPI excluding fresh food and energy moderated to 3.7% YoY from 3.8% YoY. - On Tuesday, Statistics Canada announced that CPI inflation increased slightly to 3.4% YoY in December 2023, compared to 3.1% in the previous month. This was in line with consensus expectations of 3.4% YoY. Core inflation also rose from November to December based on both trim (3.5% to 3.7%) and core (3.4% to 3.6%) metrics, with both coming in above expectations. The shelter sub-segment continued to see elevated inflation of 6.0% YoY, while the gasoline sub-segment also saw a rebound in inflation from -7.7% YoY in November 2023 to 1.4% YoY in December 2023.
- On Wednesday, Enterprise Singapore announced that Singapore non-oil domestic exports (NODX) fell by -1.5% YoY in December 2023. This marked a downturn from the previous month’s 1.0% YoY growth and was also significantly below consensus estimates of a +3.0% growth. This growth decline was primarily driven by the electronics segment which declined by -11.7% YoY, and mitigated by the non-electronics segment which grew by 1.4% YoY.
- On Wednesday, the UK Office for National Statistics announced that CPI inflation rose modestly to 4.0% YoY in December 2023 from 3.9% YoY in the previous month, contrasting with expectations which had forecast a slight decline to 3.8% YoY. This was helped by a slight re-acceleration in services inflation to 6.4% YoY (previously 6.3% YoY). Core CPI inflation remained stable at 5.1% YoY, again above expectations of 4.9% YoY.
- On Wednesday, Eurostat announced that Euro Area MUICP inflation rose to 2.9% YoY in December 2023, compared to 2.4% YoY in the previous month, and in line with expectations of 2.9% YoY. The increase was driven by lesser low-base effects in energy inflation (-11.5% YoY in November compared to -6.7% in December), while services inflation remained elevated at 4.0% YoY and continued to be a key driver. Meanwhile, core inflation (excluding energy, food, alcohol & tobacco) fell from 3.6% YoY to 3.4% YoY.
- On Thursday, the US Department of Labor announced that initial jobless claims fell to 187k for the week of 13 January 2024, compared to the revised figure of 203k in the previous week. This contrasted with expectations, which had instead forecast a mild increase to 205k.
Asian High Yield Bond Index
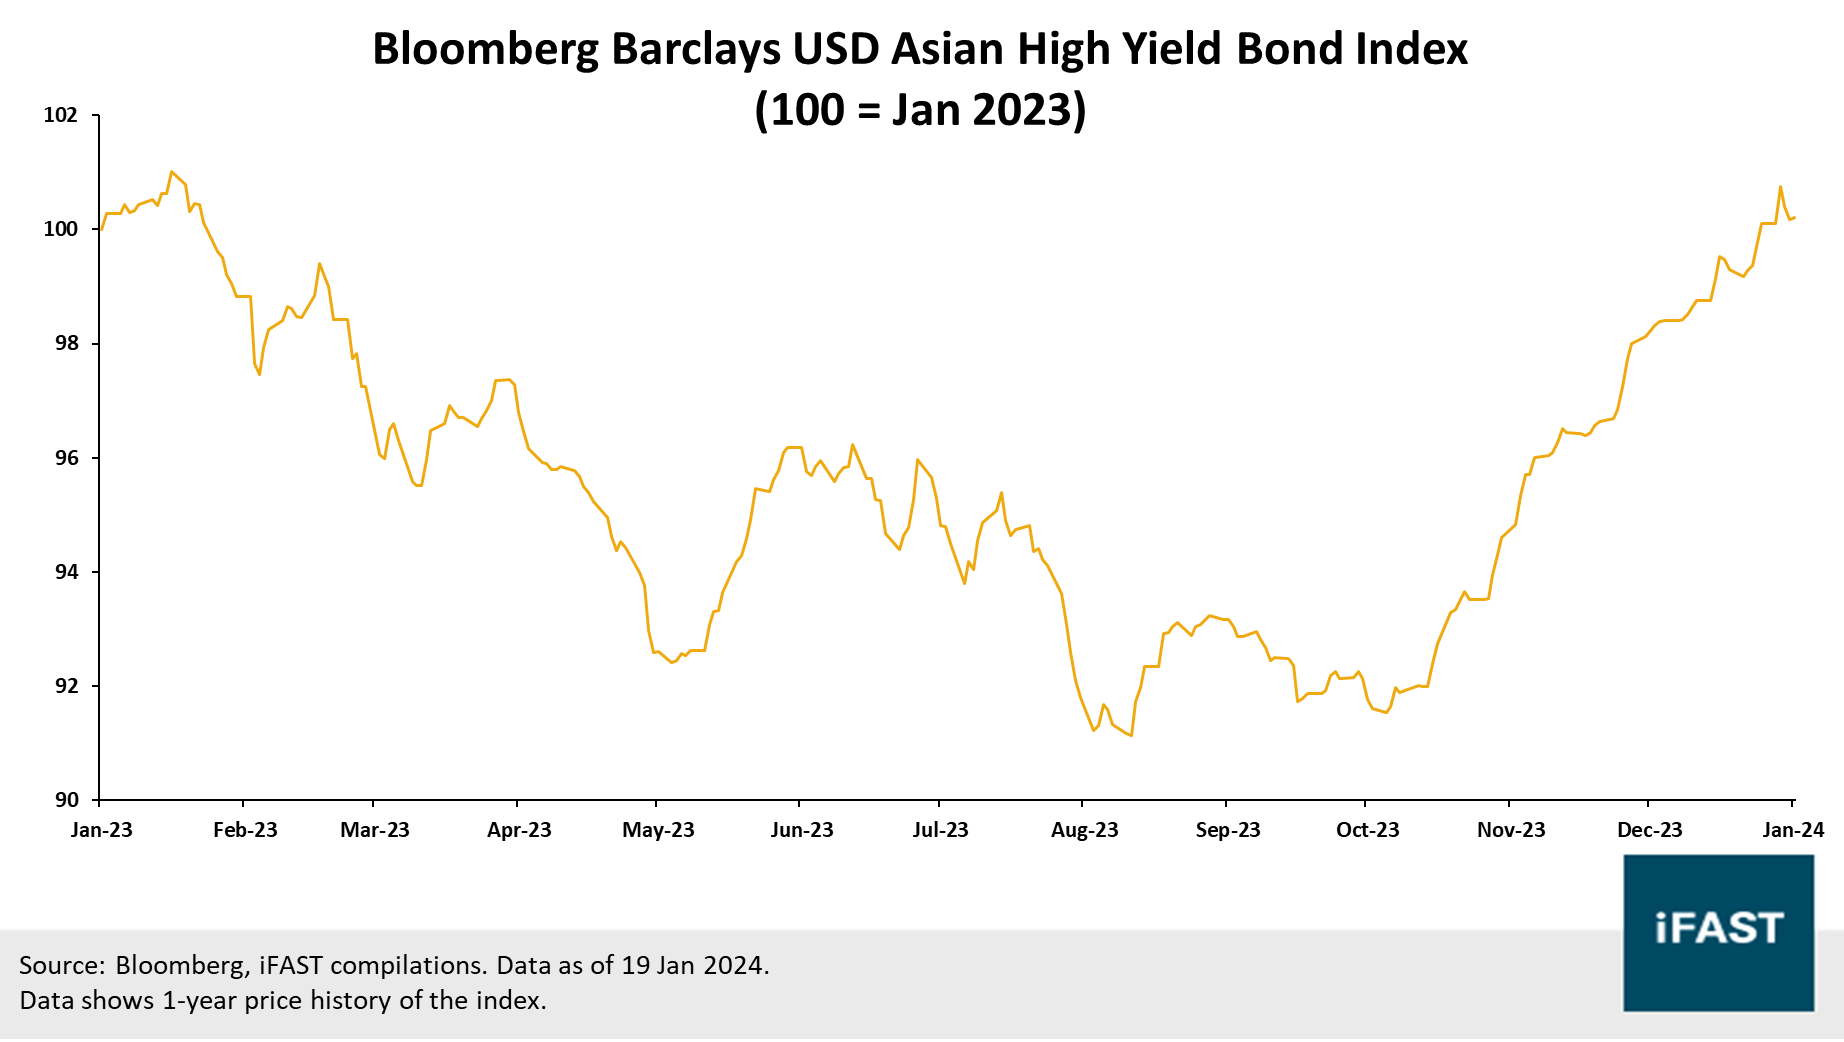
- The Barclays USD Asia High Yield Bond Index rose by 0.10% for the week ended 19 January 2024.
- On Monday, Jiayuan announced that its liquidators will work with the senior management on a debt restructuring plan and shares will remain suspended.
- On Monday, Sino-ocean announced a 2.5 years rollover plan for 7 onshore credit bonds with a balance of RMB 13.27 billion.
- On Thursday, Country Garden confirmed its plan to sell its Australian project for AUD 240 million and the deal is expected to be completed in the first half of the year.
- On Thursday, Logan appointed Alvarez & Marsal Corporate Finance Limited to join the joint financial advisory team for offshore debt restructuring.
Interest Rates and Currencies
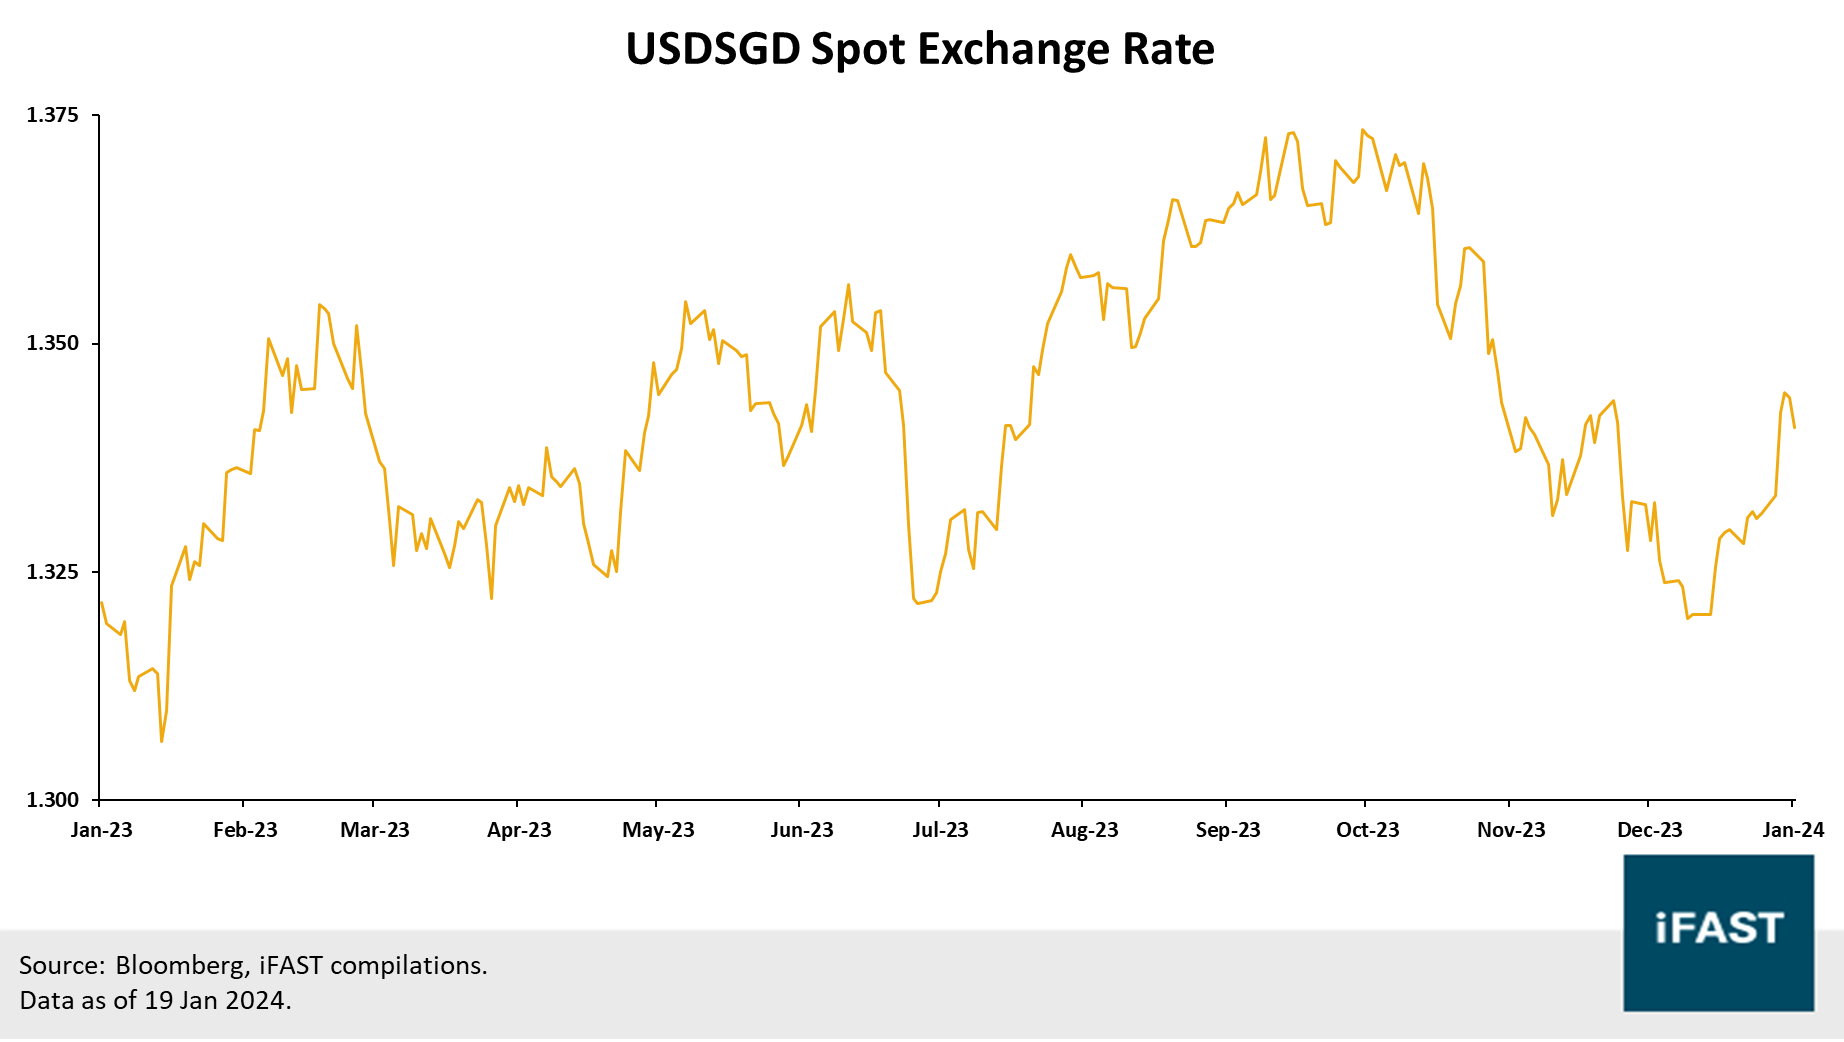
- The US Dollar (USD) appreciated against the Singapore Dollar (SGD) last week by 0.71%, with the USDSGD currency pair closing at 1.3408.
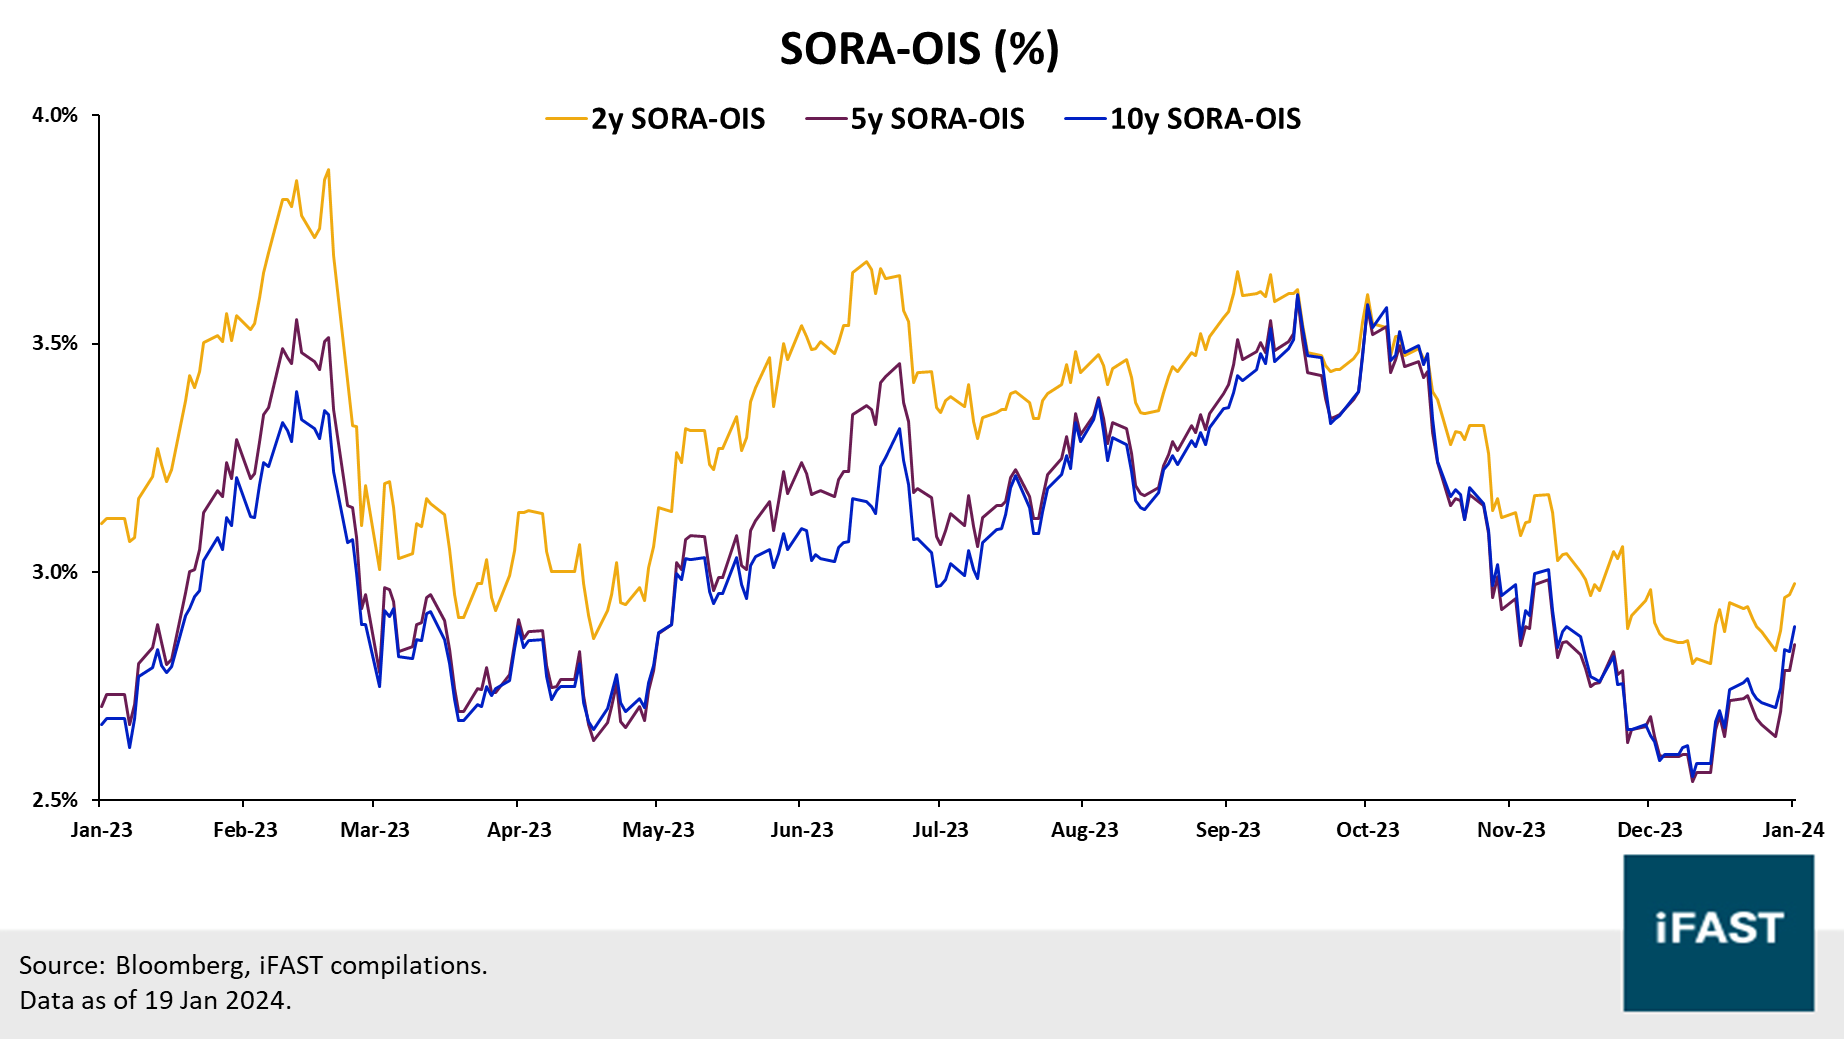
- The 2-year Singapore Overnight Rate Average-Overnight Index Swap (SORA-OIS) increased by 11 bps to 2.9750%, the 5-year SORA-OIS increased by 18 bps to 2.8400%, and the 10-year SORA-OIS increased by 17 bps for the week to 2.8800%.
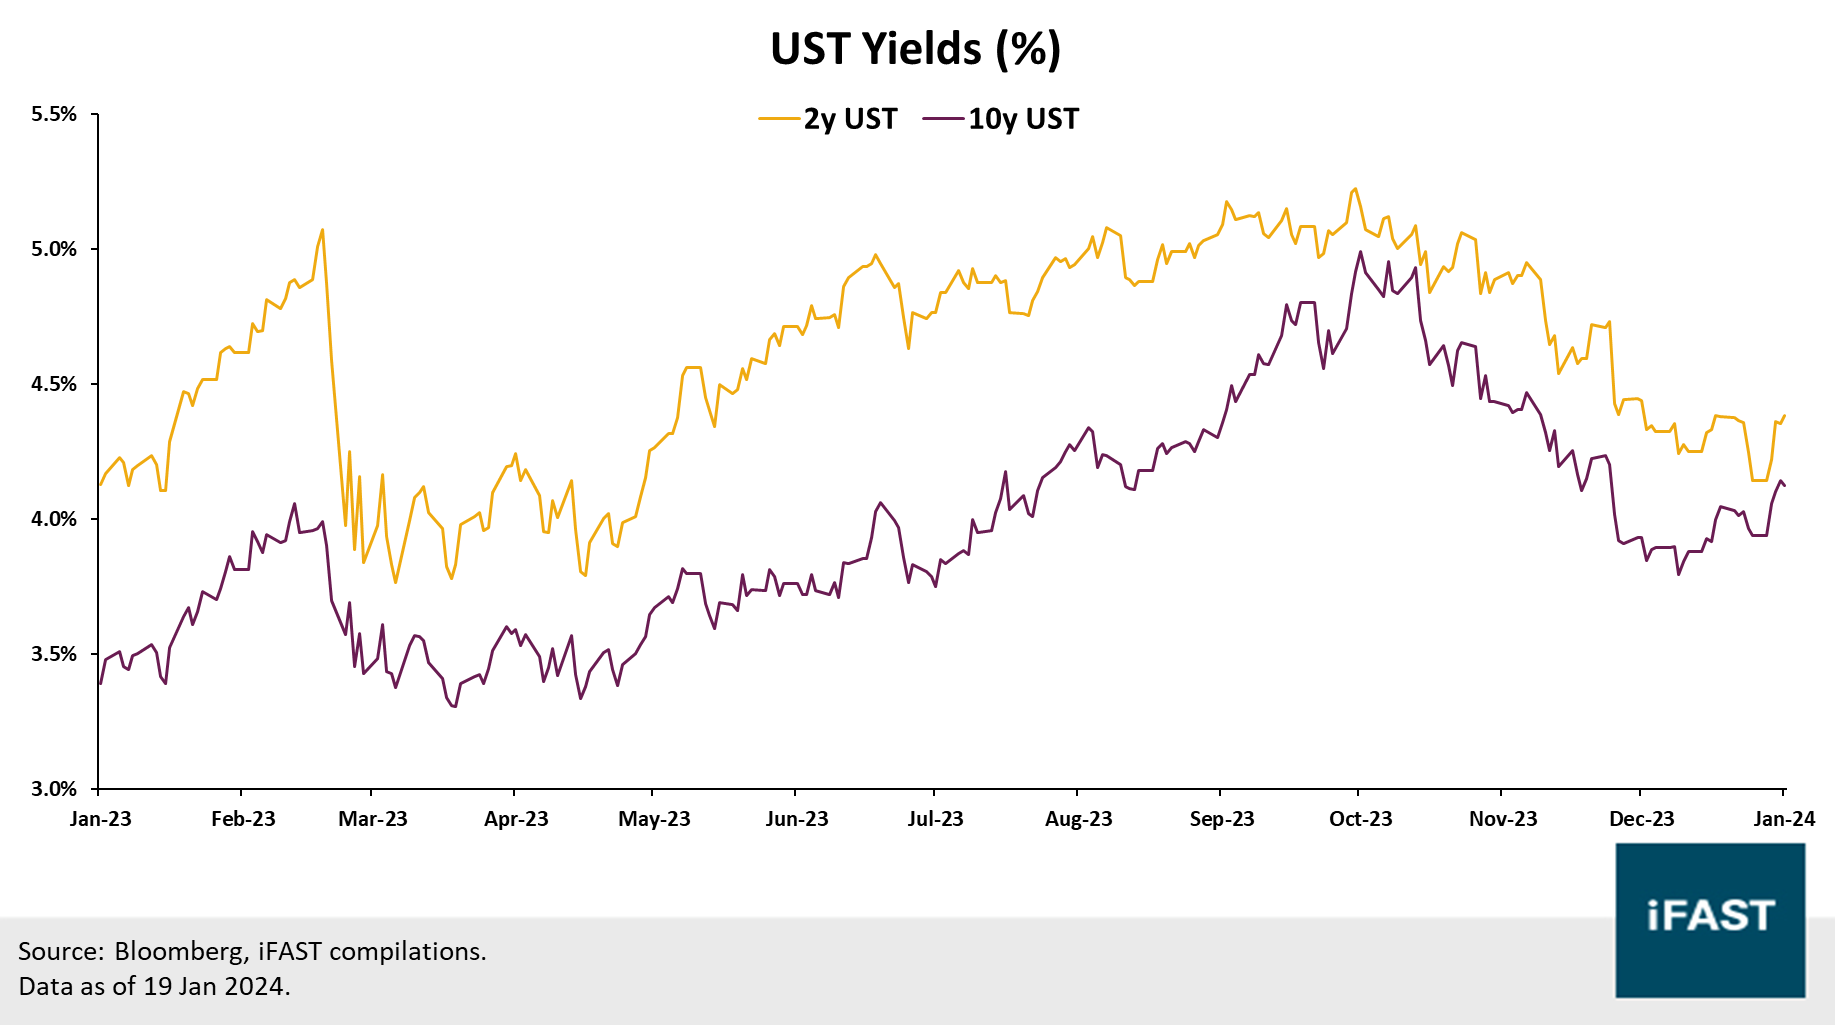
- The yield on 2-year US Treasuries (USTs) increased by 24 bps to 4.3845% while the yield on 10-year USTs increased by 18 bps to 4.1226%.
Corporate Updates and New Issues
- On Monday, Keppel DC REIT’s Manager announced that the Singapore High Court has, on 12 January 2024, issued a judgment preferring Keppel DC Singapore 1 Ltd.’s (KDC) contractual interpretation of the agreement between KDC and DXC Technology Services Singapore Pte. Ltd. (DXC) in respect of the colocation services at 25 Serangoon North Avenue 5. The dispute is set down for trial in February 2024, largely to determine the actual quantum to be paid to KDC by DXC. Any judgment is not expected to have an impact on Keppel DC REIT’s DPU for the financial year ending 31 December 2023.
- On Monday, Frasers Property Limited (FPL) announced several key organisational changes effective 1 February 2024. The new organisation structure will see four Group executive leadership roles reporting to the Group CEO, while the business units’ structure will see six business unit leaders reporting directly to the Group CEO instead of eight. Notable departures include Group Chief Corporate Officer Mr Chia Khong Shoong and Chief Executive Officer (Frasers Property China) Ms Lorraine Shiow.
- On Monday, Singapore Airlines Limited (SIA) reported operating results for December 2023 for the Group, including Singapore Airlines and Scoot (all figures YoY). Passenger traffic (revenue passenger-km) grew by +15.8%, while passenger capacity (available seat-km) rose by +16.1%, resulting in the passenger load factor falling by -0.3pp. Meanwhile, cargo load (tonne-km) fell by -0.9%, and cargo load factor decreased by -1.7pp.
- On Tuesday, Wilmar International Limited (Wilmar) announced that it denies involvement in an alleged China palm oil fraud, and reiterates it has zero tolerance for corrupt practices and does not condone any corrupt acts by any of its employees or office holders.
On Friday, Wilmar responded to several queries by SGX, relating to the ongoing litigation by Yihai (Guangzhou) Grain and Oil (Guangzhou Yihai), which is a 100%-owned subsidiary of Yihai Kerry Arawana Holdings Co., Ltd. (YKA), which is in turn a listed subsidiary of Wilmar. Wilmar disclosed that Guangzhou Yihai contributed 2.2% of revenue, 1.2% of net profits, and 0.3% of net assets of Wilmar (group) based on the latest available audited financial results for FY22. - On Tuesday, Lippo Malls Indonesia Retail Trust’s (LMIRT) Manager commenced separate tender offers for its 2024 and 2026 Senior Notes, for an amount equal to all or part of the net proceeds of the Credit Facility. LMIRT will prioritise the 2024 notes Offer over the 2026 Notes Offer and expects to allocate at least 80% of the Acceptance Consideration for purchasing the 2024 Notes and the remaining for purchasing the 2026 Notes. The relevant purchase price will be determined by an ‘unmodified Dutch auction’ process.
- On Wednesday, Thomson Medical Group (TMG) announced that FV Hospital has officially become a member of Thomson Medical Group. It held an announcement ceremony in Ho Chi Minh City, attended by government officials from both Singapore and Vietnam and the wider medical fraternity.
On Wednesday, TMG also announced that SGX-ST has approved the (i) granting of a 3-month extension to the Company until 10 April 2024 to explore options to restore its public float; and (ii) continued trading of TMG’s shares during this period. In conjunction with the restoration of its public float, the Company intends to undertake roadshows after the festive period in February 2024. - On Thursday, The Ascott Limited (Ascott), the lodging business unit wholly owned by CapitaLand Investment (CLI), shared an update on its Oakwood portfolio. Following its strategic acquisition of Oakwood Worldwide in 2H22, the Oakwood portfolio has grown by more than 20% post-acquisition, making it one of the fastest global brands in the Ascott portfolio with over 20 new signings since acquisition.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!