Receive first-hand news on the latest bond issues, credit updates and special events when you join us on our Telegram channel at https://t.me/bondsupermart!
Important Events
- Last Wednesday, the Australian Bureau of Statistics released the inflation data for October 2023, with headline inflation easing from 5.6% year-on-year (“YoY”) in September to 4.9% in October. This marks the first decline in inflation rate since July, largely due to a slower pace of increase for transport and housing prices. The monthly CPI indicator excluding volatile items and travel was down slightly at 5.1% YoY in October, as compared to the 5.5% figure in September.
- Last Wednesday, the Bank of Thailand announced the decision to sustain the key interest rate at 2.5% during the November meeting, the first pause since the beginning of the hike in late 2022. The Committee mentioned that the current policy interest rate is appropriate for supporting long-term sustainable growth. It also expects the Thai economy to gradually recover towards its potential, with inflation to be within the target range.
- Last Thursday, Eurostat released the flash estimates of the inflation data for the Euro Area for November, with headline inflation falling to 2.4% YoY, down from 2.9% for the previous month. The core inflation rate similarly went down to 3.6% YoY, a considerable drop from the 4.2% observed in October 2023. On a monthly basis, consumer prices had fallen by 0.5% month-on-month (“MoM”) in November, as compared to a 0.1% increase in October.
- Last Friday, Indonesia announced that the annual inflation rate saw a
slight climb from 2.56% YoY in October to 2.86% in November, beating the market
forecasts of a 2.7% rise. The climb was primarily due to the larger than
expected increase in transport prices, and prices of food & beverages. On
the other hand, the core inflation rate continued on its downward trend,
falling from 1.91% YoY in October to 1.87% in November. The monthly CPI saw
prices increasing by 0.38% MoM in November, the largest figure in 11 months.
Asian High Yield Bond Index
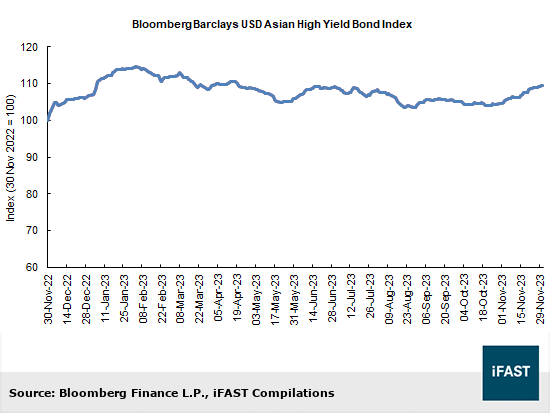
- The Barclays USD Asia High Yield Bond Index rose by 0.47% for the week ended 1 December 2023.
- On Tuesday, Greentown China announced that its subsidiary has repurchased onshore bonds and asset-backed securities for a total of RMB 609m.
- On Wednesday, Powerlong have failed to make coupon payment of USD 15.92m for its USD bond within the grace period, constituting a default.
- On Thursday, Moody's downgraded Road King's ratings to ‘B3’ and maintained the negative outlook, mainly because of an expected deterioration of financial flexibility and weakening of liquidity buffer.
Interest Rates and Currencies
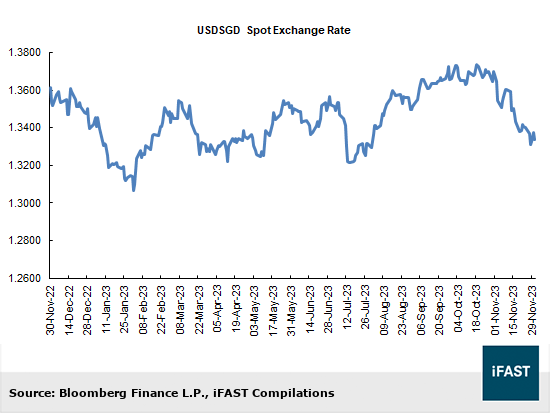
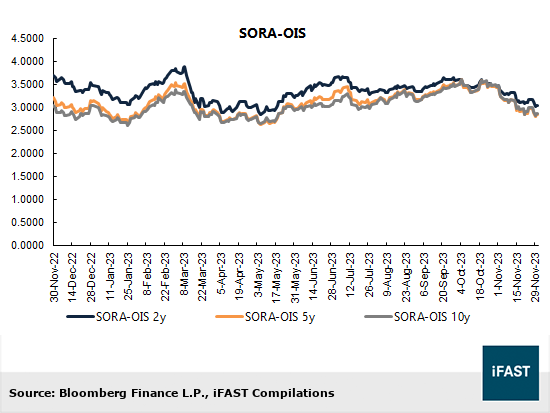
- The US dollar depreciated against the Singapore dollar last week with the USDSGD currency pair closing at 1.3335. The 2-year Singapore Overnight Rate Average-Overnight Index Swap (“SORA-OIS”) decreased by 13 basis points to 3.04%, the 5-year SORA-OIS decreased by 12 bps to 2.8475% and the 10-year SORA-OIS decreased by 12 bps for the week to 2.88%.
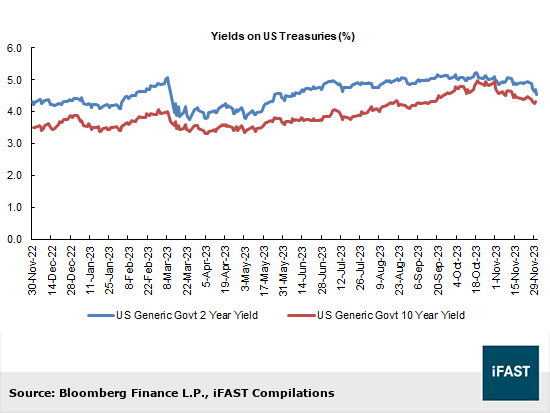
- Last week, the yield of 2-year US Treasuries (“UST”) decreased by 41 bps to 4.5384% while the 10-year UST yield saw a decrease of 27 bps to 4.1956%.
Corporate Updates and New Issues
- On Tuesday, Mapletree Industrial Trust Management Ltd. (“MINT”) announced that its subsidiary, Yuri Tokutei Mokuteki Kaisha, entered into a bond purchase agreement in connection to the acquisition of a data centre asset in Osaka, Japan.
- On Tuesday, Singapore Post Limited (“SingPost”) announced that it has conducted adjustments since the completion of the acquisition of Freight Management Holdings Pty. Ltd., and it has been determined that the total consideration paid for the acquisition is approximately SGD 173.4m.
- On Wednesday, Keppel Corporation Limited (“Keppel”) announced that it has entered into an agreement with Aermont Capital Group SCSp to acquire an initial 50% stake in leading European real estate manager, Aermont Capital (“Aermont”). The consideration for the initial 50% stake is valued at approximately SGD 517m, which is expected to be funded through a combination of cash and treasury shares acquired through Keppel’s earlier share buyback programme.
- On Wednesday, CapitaLand Ascott Trust Management Limited (“Ascott REIT”) announced that it has entered into a facility agreement with DBS Bank Ltd., for a revolving credit facility of up to an aggregate principal amount of SGD 200m.In another announcement on Thursday, Ascott REIT made the announcement on the use of proceeds of the private placement in 2022 and equity fund raising in 2023. It indicated that the proceeds have been used to partially fund the purchase consideration of the acquisition of interests in serviced residence properties in France, Vietnam and Australia, rental housing properties in Japan and a student accommodation property in South Carolina, US. The proceeds will also be used to partially fund any future potential acquisitions. Lastly, the proceeds have also been used to pay the professional fees and expenses related to the private placement, and also for the repayment of debts.
- On Thursday, Yanlord Land Group Limited (“Yanlord”) announced that Moody’s Investors Service (“Moody’s”) have downgraded Yanlord’s corporate family rating from ‘Baa3’ to ‘B1’, while the backed senior unsecured bonds have been downgraded from ‘B1’ to ‘B2’. Moody’s maintained the negative rating outlook on Yanlord and indicated that the downgrade is due to the expectation that Yanlord’s credit metrics and liquidity buffer will weaken further over the next 12 to 18 months.
- On Friday, SATS Ltd. (“SATS”) announced that its indirect wholly-owned subsidiaries have been granted several uncommitted bilateral facilities amounting to EUR 25m, EUR 33m and USD 30m. Separately, SATS has acquired uncommitted bilateral facilities of SGD 80m. The uncommitted bilateral facilities are to replace the revolving credit facilities, part of the integration plan for the acquired WFS Group and to further generate cost savings for SATS.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!