Up to Date with Rates
- In the April meeting, the Bank of Japan (“BoJ”) kept the range for its policy rate unchanged at 0% to 0.1%, a move that was largely expected by the market. In its summary of the meeting, BoJ noted upside risks to inflation owing to cost-push factors, highlighting a need to examine the possibility of pass-through of such costs to consumers. However, it believes that the ongoing yen’s depreciation would help with increasing production and income in the medium to long run, despite its impact on underlying inflation. Finally, while it intends to adjust the policy rate according to the ongoing inflation, BoJ anticipates accommodative financial conditions to be maintained for the time being.
- In the May meeting, the Federal Reserve (“Fed”) left the Federal Funds Rate target range unchanged at 5.25% to 5.50%, marking the 6th consecutive rate pause decision. In addition, the Fed plans to reduce the speed of quantitative tightening from June onwards, by reducing the monthly redemption cap on Treasury securities from USD 60b to USD 25b. The Fed also specified that “there has been a lack of further progress toward the Committee’s 2 percent inflation objective” in recent months. We see this reflected by resilient economic data – particularly with headline inflation rising from 3.1% year-on-year (“YoY”) in Jan, to 3.2% in Feb and 3.5% in Mar.
- In its May meeting, the Reserve Bank of Australia (“RBA”) decided to leave the cash rate constant at 4.35%, being the fourth time that the rate was left unchanged. RBA expects the process of returning inflation to target unlikely to be smooth, noting a slower decline in inflation – with its core inflation now higher than headline inflation. Returning inflation to the target range of 2% to 3% remains RBA’s primary concern and it mentioned that it is not ruling anything in or out at the moment. The bank is expected to remain data dependent before making its next decision.
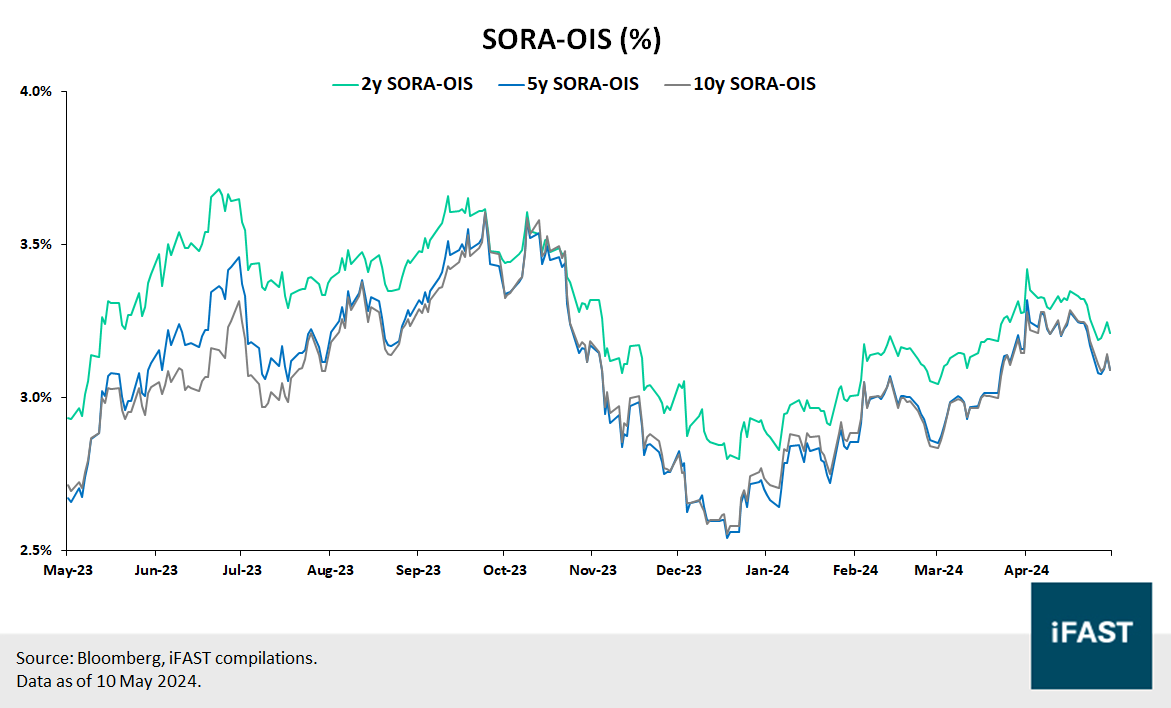
- Across the past three weeks, the 2-year Singapore Overnight Rate Average-Overnight Index Swap (“SORA-OIS”) decreased by 8 basis points to 3.209%, the 5-year SORA-OIS decreased by 12 bps to 3.090% and the 10-year SORA-OIS decreased by 12 bps to 3.088%.
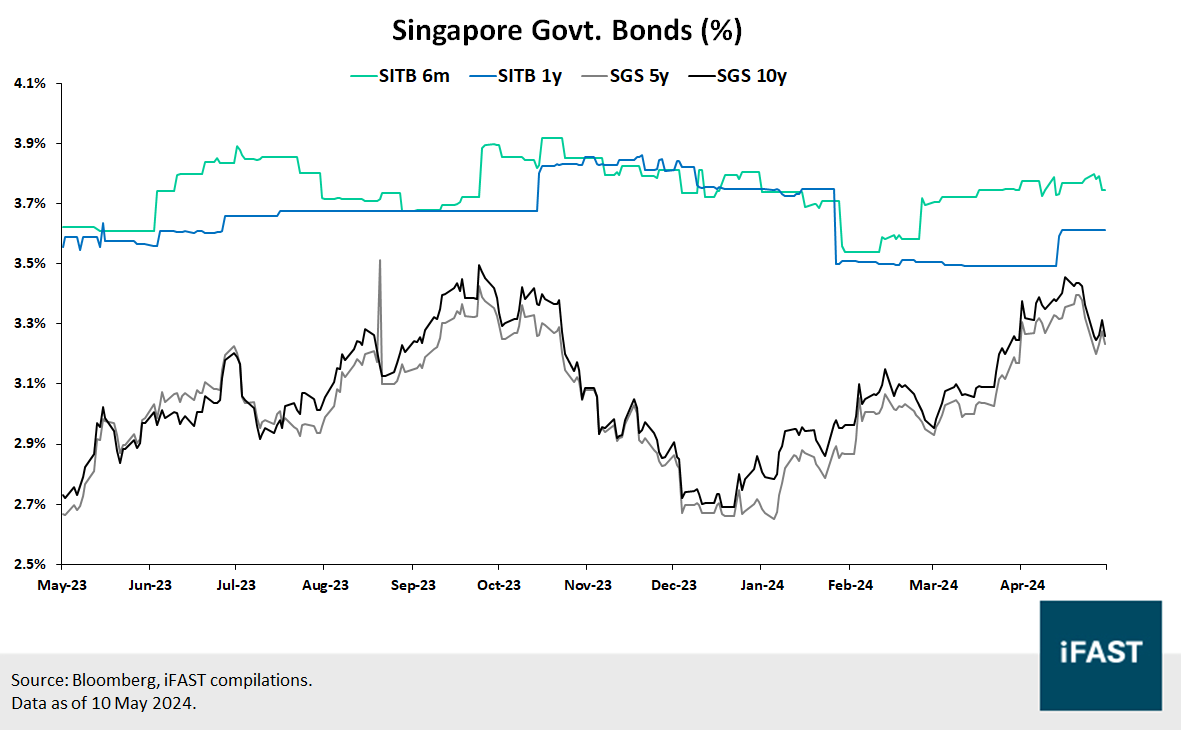
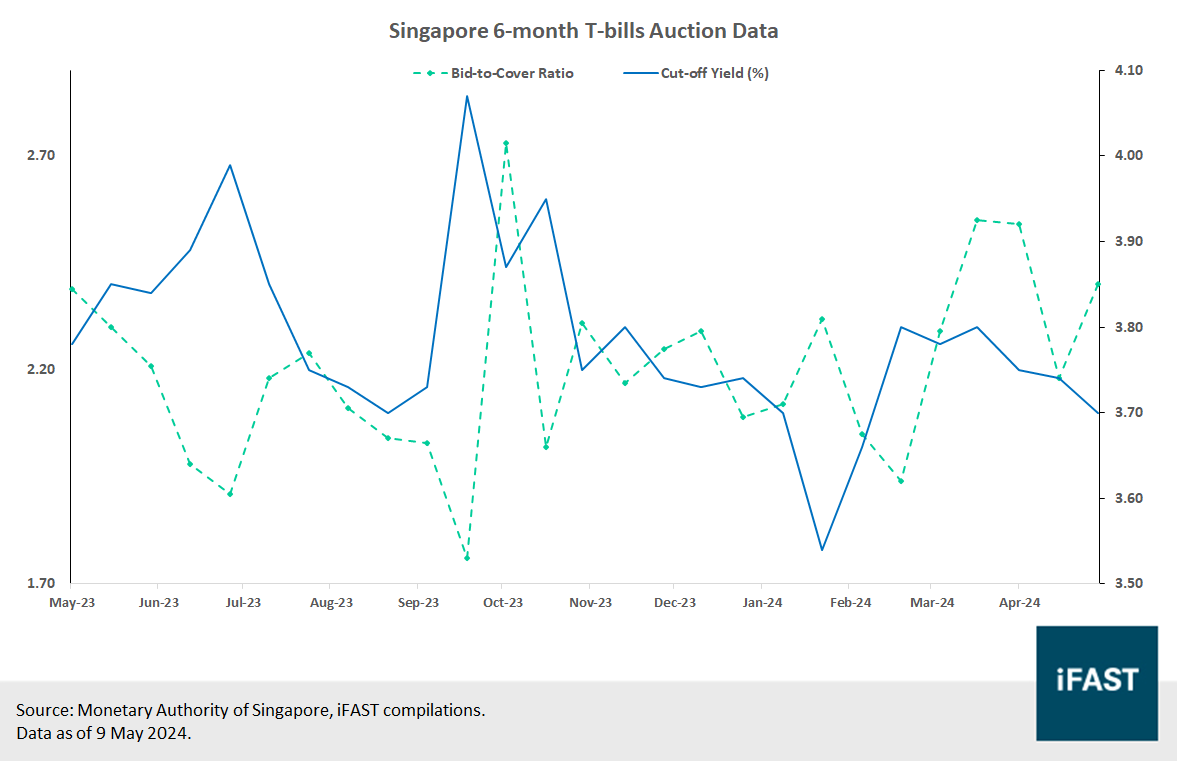
- Over the same period, average yields for the 6-month SGD T-bills stood constant at 3.75%, while the 1-year SGD T-bills rose by 12 basis points to 3.61%. The 5-year Singapore Government Securities decreased by 4 basis points to 3.23%, while the 10-year Singapore Government Securities decreased by 9 basis points to 3.26%. In the recent 6-month T-bills auction, we see an uptick in the bid-to-cover ratio to 2.40 times, which is also likely the reason for a slight drop in the cut-off yield to 3.70% last week.
Favourite Bond Investment Ideas
Olam’s 2026 fixed rate note remains highly popular on our platform, and this is no surprise considering the >5% yield it offers. Meanwhile, we remain positive on its credit profile despite a slight deterioration from last year. Given the expectation that Olam’s earnings will recover gradually on the backdrop of easing profit headwinds and potential growth opportunities, we see room for credit metrics to improve from here.
ESR remains a quality issuer in our view, with ratings of AA- (stable) from Japan Credit Rating Agency and AAA (stable) from China Chengxin International Credit Rating Agency. The 2025 fixed rate paper is attractive given the combination of short duration and good yield at such credit quality. We anticipate an improvement in ESR’s credit profile, as it plans to optimise its balance sheet to syndicate assets and divest non-core properties to pay off debt.
Recently onboarded to Bond Express, this 2030 paper provides a good yield opportunity from a major bank. At yields close to 5.8%, it can be difficult to find other offerings from OCBC at such alluring yields. OCBC will be a great banking name to add to investors’ portfolios given its strong capital position and optimistic earnings outlook ahead.
- BNKEA 6.750% 15Mar2027 Corp (USD) and BNKEA 6.625% 13Mar2027 Corp (USD) – Senior papers at more than 6% yields
The senior non-preferred papers offered by the Bank of East Asia (“BEA”) offer high yields of ~6.2% at a relatively short duration. Banks have generally performed well owing to the high interest rates environment, and BEA has undoubtedly benefitted from higher net interest income. While there might have been some negative impacts from loan impairments last year, we expect a normalisation on its non-performing loans – especially with a gradually decreasing loan exposure to China’s real estate sector. Furthermore, BEA’s credit metrics look robust, having one of the higher CET1 ratios across the industry at 17.3%.
Hot New Issues
Table 1
New
issuances over the past weeks
|
Issue |
Issuer |
Issuance Date |
New Issue View |
|
Hotel Properties Limited |
03 May 2024 |
||
|
Thomson Medical Group Ltd |
13 May 2024 |
Thomson Medical Group announces 3-year SGD senior unsecured notes at IPG of 5.60% |
|
|
Oversea-Chinese Banking Corporation Limited |
21 May 2024 |
OCBC announces USD 10NC5 Tier 2 subordinated notes at IPG of CT5 + 145 bps |
|
|
Sources: Bondsupermart, iFAST Compilations. |
|||
Corporate Updates You Should Know
- 23 April – OUE-REIT Management Pte. Ltd. (“OUE-REIT”) announced that it has successfully obtained an unsecured sustainability-linked loan amounting to SGD 600m – for the early refinancing of SGD 540m existing secured borrowings due in 2025 and general corporate purposes. OUE REIT has no further refinancing requirements until 2H25, with about 25% of total debt due then. The weighted average cost of debt is expected to remain largely stable.The loan facility is the REIT’s first sustainability-linked loan, which will allow it to enjoy sayings in interest costs when the reduction target of absolute Greenhouse Gas emissions of commercial properties is achieved. The intended goal is to achieve a 40% reduction in the emissions for its commercial properties, with FY23 as a base year.
- 26 April – OUE Limited (“OUE”) announced that it has been awarded the tender by Changi Airport Group for the lease and development of a new hotel to be located at Changi Airport Terminal 2. The new hotel is expected to be completed by 2028. OUE indicated that it expects to fund the development with a combination of internal cash resources and borrowings.
- 29 April – Singapore Telecommunications Limited (“Singtel”) announced that it expects to recognise exceptional non-cash impairment provisions of approximately SGD 3.1b for the second half year ended 31 March 2024. The provisions consist of the impairment on the following: (1) Optus enterprise fixed access network assets of approximately SGD 470m, on the goodwill of (2) Optus Group and (3) its Asia-Pacific cybersecurity business of approximately SGD 2b and SGD 340m respectively, and on (4) NCS Australia of approximately SGD 280m. Singtel indicated that it expects to report a net loss for the second half year and a lower net profit for the financial year ended 31 March 2024.
- 30 April – ESR-LOGOS Fund Management (S) Limited (“ESR-LOGOS REIT”) announced that it has completed the divestment of 182-198 Maidstone Street, Altona, VIC, Australia for a sale consideration of AUD 65.5m. The divestment of the non-core asset is at a 7.4% premium to the valuation of the property and remains in line with ESR-LOGOS REIT’s objective of capital recycling to focus on New Economy Assets.
- 8 May – LMIRT Management Ltd. (“LMIRT”) announced an exchange offer for its LMRTSP 7.250% 19Jun2024 Corp (USD) bonds. The offer will allow bondholders to receive USD 600 in cash and USD 432 in principal amount of LMRTSP 7.500% 09Feb2026 Corp (USD), for each USD 1,000 principal amount of the 2024 notes. Due to the minimum denominations required for the 2026 notes, bondholders are required to tender at least USD 463,000 of the 2024 notes to be accepted.In a separate announcement on the same day, LMIRT announced that it has obtained a secured amortising term loan (non-revolving, committed and advised) facility of up to approximately SGD 126.3m, with an average lift of approximately 6 years. The proceeds from the loan facility will be used to partially repay LMIRT’s maturing debt, which includes the 2024 bond and the associated exchange offer.
- 10 May – Oversea-Chinese Banking Corporation Ltd (“OCBC”) announced a voluntary unconditional general offer for all the issued ordinary shares in the capital of Great Eastern Holdings Limited (“GE”), which represents an 11.56% stake in GE that it does not currently own. OCBC is expected to utilise about SGD 1.4b from its internal cash, which translates into a 60 basis points drop for its CET1 ratio.OCBC’s decision to purchase the remaining ownership of GE will likely be beneficial to the Group, given a possible moderation in net interest margin in the medium to long term. It expects the Group’s FY23 Return on Equity to improve from 13.7% to pro-forma 14.0%. Meanwhile, despite the impact on the CET1 ratio, OCBC’s capital position remains relatively resilient with a pro forma CET1 ratio of 14.5%.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in OLAMSP 4.000% 24Feb2026 Corp (SGD), ESRCAY 5.100% 26Feb2025 Corp (SGD), and OCBCSP 1.832% 10Sep2030 Corp (USD). The analyst who produced this report holds an NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!