Important Events
- On Tuesday, the Reserve Bank of Australia (“RBA”) announced a 50 basis points (“bps”) hike to the cash rate, marking its largest increase in 22 years. The move caught markets by surprise, as most economists were mostly divided between a 25 and 40 bps rate hike in the June policy meeting. RBA Governor Phillip Lowe said that based on the current inflationary environment and low level of interest rates, the Board decided to take a larger step to hike its cash rate up to 0.85% to curb inflation. Going forward, the central bank still expects to increase rates further to normalize monetary conditions in Australia, as inflation is expected to come in hotter than expected in the near term due to higher electricity and gas prices.
- On Wednesday, the Bank of Thailand (“BOT”) kept its benchmark interest rate unchanged at a record low of 0.50% in a 4 - 3 vote among the monetary policy committee members. The central bank raised its inflation target this year from 4.9% to 6.2%, but expects the economy to grow at a slightly faster pace of 3.3% compared to its previous forecast of 3.2%. Nonetheless, the latest policy meeting suggests a hawkish turn towards raising rates in the near future, as 3 members proposed to tighten interest rates by 25 bps due to the rising inflationary risks. As economic recovery continues to gain momentum, the BOT could scale back on its accommodative monetary policy going forward.
- On Wednesday, the Reserve Bank of India (“RBI”) raised its key interest rate by 50 bps to 4.90%, and will continue to tone down its accommodative stance to bring inflation back to its target. RBI Governor Shaktikanta Das said that inflation risks highlighted in previous policy meetings have materialized earlier than expected, with CPI prints expected to exceed 7% over the next 2 quarters. Nonetheless, the central bank maintained its 2022 - 2023 growth projection at 7.2%, as liquidity in the financial systems still remains above its pre-pandemic levels.
- On Thursday, the European Central Bank (“ECB”) announced that it will look to increase interest rates at subsequent policy meetings, starting with a 25-bps rate hike next month, followed by another round of tightening in September with a possibility of larger rate increment. The last time it raised interest rates was back in 2011, and a potential 50-bps rate hike in September would mark the largest one-time increment since 2000.Furthermore, the ECB will also end net purchases under its asset purchase program (“APP”) from 1 July 2022 onwards, but will continue to reinvest the principal payments of maturing securities when it starts raising key ECB interest rates to ensure sufficient liquidity within the financial systems. Notably, the central bank raised its inflation estimates this year to 6.8% versus a previous forecast of 5.1%, before slowing down to 3.5% in 2023 and 2.1% in 2024. Growth forecast for the eurozone was also cut from 3.7% to 2.8% this year.
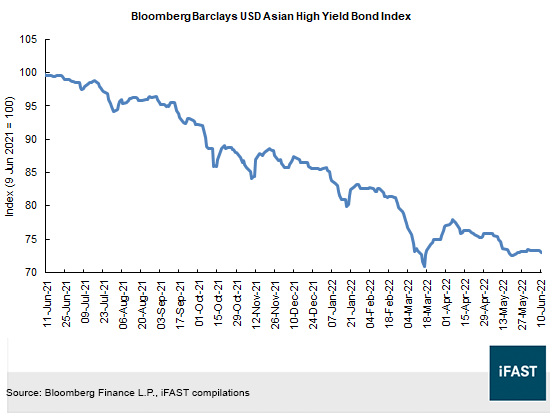
Asian High Yield Bond Index
- The Barclays USD Asia High Yield Bond Index decreased by 0.3% for the week ended 10 June 2022.
- On Tuesday, Nan Hai Corporation said that its creditors are freezing some of its assets due to its failure to meet the part of the financial obligations for its USD 350m 2.9% credit-enhanced notes that was due on 11 June 2022. The Group will continue to restructure its liabilities and look to sell its assets to improve its liquidity position.
- China’s fourth largest property developer, Sunac China Holdings, announced on Thursday that it is planning to extend the payment deadline of a maturing onshore bond that is due on 13 June 2022. It intends to repay the principal of the CNY 2.3b bond in 4 instalments over the next 2 years, while interest payments will be delivered semi-annually over the 2 years of extension period. The Group proposed to pay 10%, 15%, 20% and 55% of the principal every 6 months through 13 June 2024. In addition, Sunac plans to collateralize a project in Hainan Province to help pay off the debt.
Interest Rates and Currencies
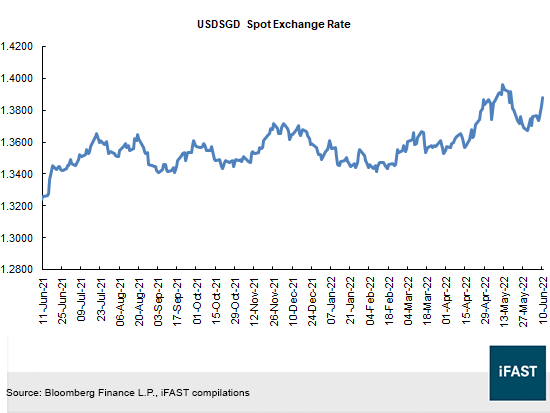
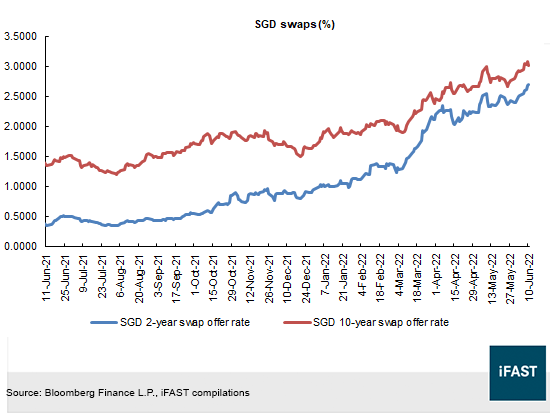
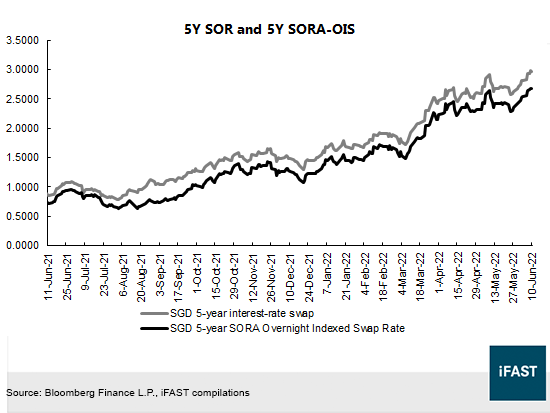
- The US dollar appreciated against the Singapore dollar last week with the USD/SGD currency pair ending at 1.388. The 2-year SGD Swap Offer Rate (“SOR”) increased by 18 basis points (“bps”) to 2.695% while the 10-year SGD SOR increased by 9 bps for the week to 3.015%. Meanwhile, the 5-year SOR increased by 15 bps to 2.968% while the 5-year SORA-OIS increased by 14 bps to 2.685%.
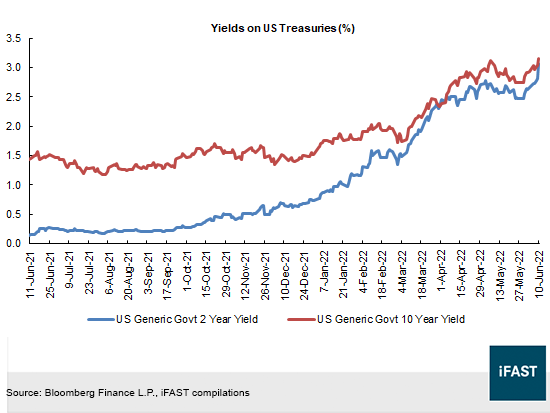
- Last week, the yield
of 2-year US Treasuries (“UST”) increased by 41 bps to 3.063% while the 10-year
UST increased by 22 bps to 3.156%. This marks the highest 2-year UST yield
since 2008 following the aggressive sell-off in US Treasuries. US Treasury
yield curve bear-flattened sharply last week after May inflation data surpassed
expectations, with markets pricing in a possible 75 bps rate hike in the
upcoming FOMC meetings.
This resulted in the shorter-end of the yield curve to reprice significantly higher, as short-term rates tend to be more sensitive to Fed rate hikes. US Consumer Price Index in May came in at 8.6%, higher than an expected 8.3% while consumer sentiment fell to a record low in June on inflation concerns.
Corporate Updates and New Issues
- On Monday, China Construction Bank Singapore branch priced a 2-year SGD fixed rate bond at 2.85%, tightening 20 bps from its initial price guidance of 3.05%. The new issue is expected to be rated “A1” by Moody’s, and orderbooks were in excess of SGD 720m, which is slightly more than 2x as compared to its issue size of SGD 350m.
- On Tuesday, CapitaLand Investment Limited (“CLI”) announced the acquisition of a freehold office tower in the Western Core of Melbourne’s CBD for its CapitaLand Open End Real Estate Fund (“COREF”). The 22-storey office tower, 120 Spencer Street, is strategically located opposite the Southern Cross Station, which is a major public transport hub that connects to the wider Melbourne region, and it has a net lettable area of 32,000 square metres. 120 Spencer Street has a strong committed office occupancy of 97.5% and a weighted-average lease expiry (“WALE”) of 6.7 years. CLI believes that its strategic location, coupled with the upgrading works implemented over the past 5 years, would benefit from the post-covid recovery.
- Meanwhile, CapitaLand Malaysia Trust (“CLMT”) on Tuesday signed a sale and purchase agreement to acquire 2 plots of contiguous freehold land and industrial properties located in Sungai Jawi, Penang. CLMT intends to fund the purchase consideration of RM 80m with bank borrowings. Following the acquisition, CLMT’s gearing will increase from 35.9% to 37.2%, which still remains well below the 50% regulatory limit. The proposed acquisition is expected to be completed in the second half of 2022.
- On Tuesday, Olam Group Limited announced that it intends to redeem its SGD 350m 5.50% of subordinated perpetual bond on 11 July 2022 (first call date). Payments will be only made on the following business day, since 11 July is a Singapore public holiday.
- On Friday, Mapletree Industrial Trust (“MIT”) entered into a sale and purchase agreement for the proposed divestment of a data centre located in Southfield, Michigan for a consideration of USD 10m. The data centre has a net lettable area of ~52,940 square feet with an occupancy rate of 74.3% since its acquisition back in 2017. It contributed to ~0.3% of MIT’s portfolio gross revenue for the financial year ended 31 March 2022. Net proceeds from the divestment will be used to pare down existing debt and/or fund working capital requirements.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!