China Aoyuan Group Limited (“CAPG”), a Chinese real estate company listed on the Hong Kong Stock Exchange (2883:HK), is looking to issue a new USD 3.6-year bond (non-callable in 2.6 years) to refinance existing offshore borrowings. The company is a constituent of a few equity indices such as MSCI China, Hang Seng Composite LargeCap & MidCap Index and the Hang Seng Stock Connect Greater Bay Area Composite Index.
Credit rating agencies Fitch Ratings, Moody’s Investors Services and S&P Global Ratings have assigned BB- (positive) / B1 (positive) / B+ (positive) to the issuer. Meanwhile, the new issue is expected to be rated BB-, B2 and B by Fitch, Moody’s and S&P respectively.
With a 3.6-year maturity, the bond has an initial price guidance of 6.75% and will be listed on the Singapore Exchange. Furthermore, the bond is callable at 102 at any time on or after 8 Feb 23.
About China Aoyuan
CAPG is a real estate developer with properties in a number of cities including Beijing, Shanghai, Guangzhou, Shenzhen, Sydney and Hong Kong. As at 31 Dec 19, the group oversees 85 projects covering a total of 45.0m square meters (“sqm”), with approximately RMB 458.5 billion of total saleable resources (RMB 684.5 billion if urban redevelopment projects were included). Nearly 42% of the projects are located in South China, while 27% and 17% are situated in the core region of Central & Western China and East China respectively.
80% of the group’s land bank is made up of residential real estate, while 16% are commercial properties. Completed and held-for-sale developments account for 8% of the land bank; 51% is undergoing construction and 38% of the land bank is held for future development.
Financials
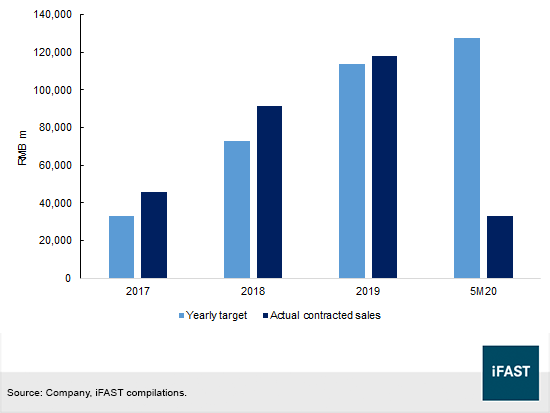
Contracted sales have been on an uptrend before COVID-19 happened. CAPG exceeded their sales targets in the past three years and achieved nearly 26% of their 2020 target in the first five months of the year (“5M20”). The group sold RMB 33.3 billion of real estate this year, which is a laudable achievement in view of the recent pandemic outbreak and sharp slowdown at the start of 2020 (Figure 1).
Figure 1: Contracted sales since 2017
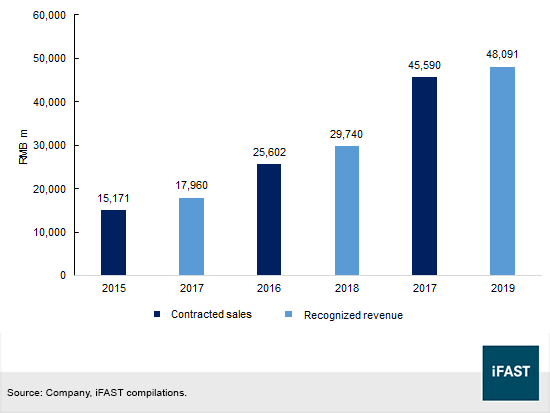
Unbooked revenue provides good visibility into the group’s earnings for the next two years. According to the company’s guidance, approximately RMB 170.5 billion will be gradually booked in the income statement between 2020 and 2021. Contracted sales were RMB 45.6 billion in 2017 and recognized revenue were RMB 48.1 billion in 2019 (Figure 2).
Figure 2: Contracted and recognized revenue from property development
During the first five months of this year, contractual sales have declined from a year ago which suggest slower top-line growth but average selling prices of projects have increased, rising from RMB 7,397 per sqm in 2017 to RMB 9,227 per sqm in 2019.
Last year, CAPG recorded RMB 50.3 billion of total revenue (including revenue from property investment and “others”), up 63% from a year earlier. Gross profit and net profit for 2019 were RMB 15.0 billion and RMB 5.2 billion, translating to a gross profit margin and net profit margin of 29.9% and 10.4% respectively.
However, net cash from operating activities declined from RMB 8.6 billion in 2018 to -RMB1.8 billion in 2019. At the same time, cash outflow for the purchases of property, plant and equipment increased to RMB 1.3 billion (2018: RMB 453m), while investments in joint ventures and associates collectively reached RMB 2.4 billion last year.
The group has a manageable liquidity profile with RMB 58.0 billion of unrestricted cash and RMB 42.1 billion of short-term borrowings (includes senior notes, lease liabilities and bank loans). CAPG’s current ratio, measured as the value of current assets over current liabilities, was 1.3x at the end of December 2019, down from 1.4x in 2018. The cash collection ratio was decent as CAPG managed to collect RMB 92.1 billion or 78% of the RMB 118.1 billion of contracted sales in 2019.
According to the developer, its net gearing ratio was 74.9% in 2019, defined as net borrowings (total amount of bank and other borrowings, senior notes and corporate bonds net of cash and cash equivalents, structured deposits and restricted bank deposits) over total equity. In addition, the group has contingent liabilities relating to guarantees in respect of mortgage facilities provided by banks to purchasers and banking facilities granted to joint ventures, amounting to nearly RMB 85.7 billion (2018: RMB 53.6 billion).
The group’s interest-servicing ability, or EBIT over finance cost, was somewhat low among peers, at 1.5x in 2019. Our numerator defines EBIT as earnings before interest and taxes and excludes other income, changes in fair value of properties and recognition of change in fair value upon transfers.
Bond valuation
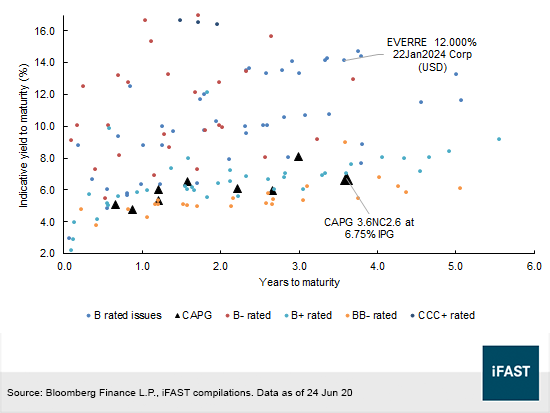
With an IPG of 6.75%, we think that the pricing is fair given that it falls along the B+ and B-rated curves (Figure 3). The issuer has access to ample liquidity and healthy credit metrics. However, we think the new CAPG note is less attractive compared to the EVERRE 12.000% 22Jan2024 Corp (USD).
Figure 3: Relative valuation among Chinese developer credits
China Evergrande Group (“EVERRE”; or “Evergrande”) is one of the top three developers in China with a vast land bank and much bigger operating scale. Among single-B issuers, Evergrande has a considerable advantage in terms of scale, and we are optimistic about its credit prospects. EVERRE had been actively tapping the bond market before the pandemic, and that helped to provide liquidity to the group. Early this year, there were RMB 46.5 billion worth of issuances that came from the real estate giant, which narrowed the gap between its cash position and short-term debt to less than RMB 100 billion.
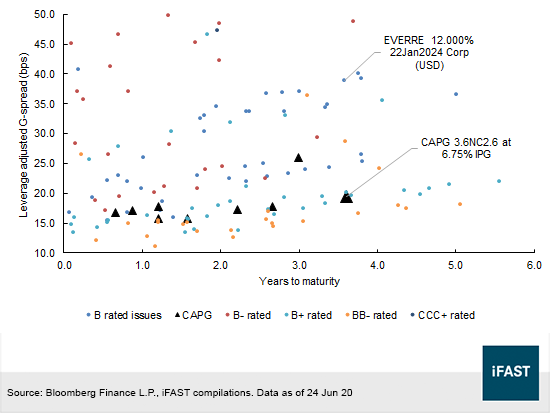
From the perspective of leverage-adjusted G-spreads (credit spreads divided by the issuers’ debt-to-asset ratio), we also prefer the EVERRE 12% ‘24s over CAPG’s new note as they offer a more attractive valuation (Figure 4).
Figure 4: Relative valuation using adjusted credit spreads
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a principal position in EVERRE 8.250% 23Mar2022 Corp (USD) and EVERRE 7.500% 28Jun2023 Corp (USD). The analyst who produced this report hold a NIL position in the abovementioned securities.