PT Ciputra Development Tbk (“Ciputra”), one of Indonesia’s largest diversified property developers, is inviting noteholders of the CTRAIJ 4.85% 21’s to tender their notes and approve a call option for the issuer to redeem the bonds before maturity.
Additionally, the company has announced its intention to issue new bonds to finance the payment of consent fees and redemption of existing notes. These new bonds may include a negative pledge clause and financial covenants including (1) keeping a consolidated tangible net worth of more than IDR 8 trillion; (2) ensuring that consolidated total debt over total equity does not exceed 1x; and (3) keeping a consolidated secured debt-to-total asset ratio of less than 0.5 to 1. In certain situations, there may be restrictions on the disposal of the issuer’s assets to meet debt obligations.
About the extraordinary resolution
Noteholders have been asked to approve the inclusion of a new clause in the Conditions of the Notes, so as to allow the issuer to redeem the SGD bond at 100 before 20 Sep 21. Further to this, the issuer has asked for approvals to authorize the Trustee to make changes to the trust deed in facilitating the passing of the resolution, as well as to discharge the Trustee from liability in matters related to this proposal.
A meeting will be held on 10 Feb 21, 2.30pm to decide the passing of the extraordinary resolution. Noteholders have to submit their voting instruction and tender forms to the company by 8 Feb 21, 2.30pm (“Expiration Deadline”). However, individuals who vote in favor of the extraordinary resolution and submit their tender forms to sell their notes on or before 27 Jan 21, 5pm (“Early Consent Deadline”) will receive an early consent fee of 0.1%. Eligible noteholders who vote in favor of the resolution after the Early Consent Deadline and before the Expiration Deadline will receive a consent fee of 0.05%.
Note that these consent fees will be paid upon the satisfaction and/or waiver of a few conditions, which includes the issuer receiving the net proceeds from the potential new note offering.
At the meeting on 10 Feb 21, the chairman will decide if the resolution is passed - that is, if at least 75 percent of the votes cast, representing not less than 75 percent of the outstanding principal of the notes vote in favor of the resolution.
Bondholders may appoint proxies to attend the meeting on their behalf. Noteholders or proxies who wish to attend the 10 Feb 21 meeting must pre-register by 8 Feb 21, 2.30pm by indicating their interest and providing their identification details to Tricor Singapore Pte. Ltd at 80 Robinson Road, #11-02, Singapore 068898. The meeting will be held via the Zoom electronic platform. Instructions to access the meeting will be sent via email.
About PT Ciputra Development Tbk
The bond issuer is a listed company on the Indonesian stock exchange, and is recognized as one of the leading property developers in the country. Established in 1981, the group has developed more than 70 real estate projects.
As of 5 Jan 21, there are 78 projects in the portfolio made up of residential properties, commercial offices, retail malls, theme parks and golf courses. Ciputra has a 2,341 hectares of gross land bank that is mainly located in Greater Jakarta and Greater Surabaya. The company has rights to an additional 4,304 hectares of land bank through joint operations.
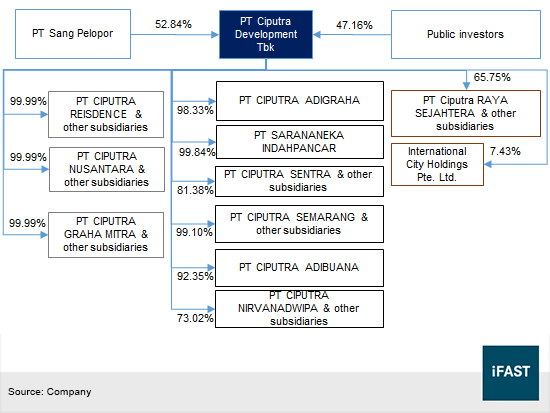
PT Sang Pelopor, a holding company wholly owned by the Ciputra family is a 52.84% shareholder of the company (Figure 1). As at 21 Jan 21, the market capitalization of the company was IDR 19.92 trillion (~USD 1.42 billion)
Figure 1: Corporate structure
Recent group performance and credit highlights
Total revenue declined 8.9% YoY to IDR 4.24 trillion in the nine-month period ended 30 Sep 20 (“9M20”), weighed on by lower contributions from shopping malls, hotels and apartment sales. Operating activities were disrupted because of COVID-19.
Hotel occupancies plunged and RevPARs (revenue per available room) declined by as much as 67% YoY. Average hotel occupancy rates dropped from 64.4% for the nine month period ended 30 Sep 19 to 34.0% for the nine month period ended 30 Sep 20.
As a result of lockdown measures by the authorities, many of the non-essential services at the shopping malls were forced to close, which led to lower rental collections. In spite of lower total revenue in 9M20, Ciputra registered a 13.2% rise in property development revenue to IDR 2.73 trillion.
In April 2020, the company withdrew its 2020 sales target of IDR 6.7 trillion and lowered it to IDR 4.5 trillion in July. However, the group achieved IDR 5.5 trillion of sales by the end of December and exceeded its 2020 target. Looking ahead to this year, the number of coronavirus cases in Indonesia is surging and this could lead to lower sales in 2021 as the full financial impact of the pandemic is not certain.
Gross profit margins from property developments and assets with recurring incomes remained high at 45.0% and 44.0% respectively. Overall, Ciputra made a net profit of IDR 248.07 billion during 9M20, down from IDR 469.89 billion in 9M19.
Net cash from operating activities remained healthy at IDR 632.48 billion in 9M20 (9M19: IDR 657.90 billion). We estimated that free cash flow, which takes into account cash outflows from land acquisitions, fixed assets investments and expenditures on investment properties, improved from negative IDR 264.22 billion in 9M19 to negative IDR 208.10 billion in 9M20.
Ciputra has sufficient liquidity to cover its current borrowings. Cash and cash equivalents of IDR 4.38 trillion exceeded the value of the group’s current borrowings of IDR 2.8 trillion – consisting of short-term bank loans, bonds payable and notes payable.
Ciputra’s total debt increased from IDR 9.18 trillion in 4Q19 to IDR 9.65 trillion in 9M20. The group’s borrowings were mostly pegged to IDR floating rates, and 20% of debt are denominated in SGD and 1% denominated in USD.
The company’s credit metrics are at a reasonably comfortable level. EBIT over finance costs was down from ~1.7x in 9M19 to ~1.4x in 9M20. Gearing, defined as net debt over total equity, remained manageable at 0.31x. Ciputra’s current ratio was still on an upward trend from 1.4x in 2013 to 1.9x in September 2020.
Our recommendation
We recommend bondholders to vote in favor of the extraordinary resolution and subscribe to the potential upcoming bond offering as this would likely give them a higher overall return. A new bond issuance, if launched, is likely to be priced above 4.85%.
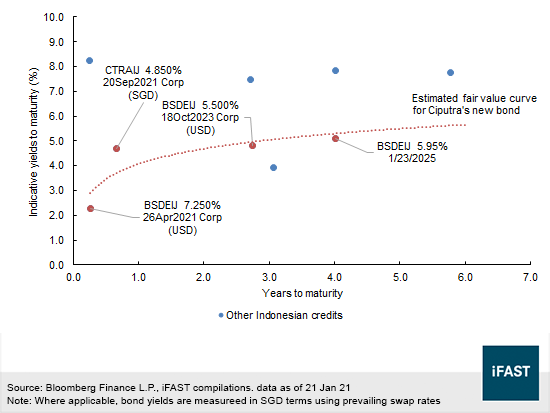
As at 21 Jan 21, comparable Indonesian real estate credits such as the CTRAIJ 4.850% 20Sep2021 Corp (SGD), BSDEIJ 5.500% 18Oct2023 Corp (USD) and BSDEIJ 5.95% 2025’s are trading at indicative yields to maturity of 4.67%, 4.82% (USD: 4.90%) and 5.11% (USD: 5.28%) respectively (Figure 2).
BSDEIJ or Global Prime Capital Pte Ltd is a subsidiary of PT Bumi Serpong Damai Tbk (“Bumi Serpong”) and Sinarmas Land Limited. Sinarmas Land owned 49.08% of Bumi Serpong as at 31 Dec 19. In the 9M20 period, Bumi Serpong is estimated to have a net debt to total equity of ~0.21x (Ciputra: 0.31x) and EBIT/interest multiple of ~1.2x (Ciputra: 1.4x).
Bumi Serpong’s land bank is among the largest in Indonesia. As at 30 Sep 19, the company has rights to 10,223.8 hectares of land under the Cooperation Agreement with its shareholders. Its 4,634.2 hectares land bank includes 3,619.3 hectares in Greater Jakarta.
Fitch Ratings has assigned a ‘BB-‘ rating to the BSDEIJ 5.5% 2023’s and a ‘B+’ rating to the Ciputra’s proposed notes. Considering the two issuer profiles and lower credit rating of Ciputra’s new note, we think that a new three-or four-year bond offering from Ciputra would be fairly priced at a yield above 4.82% (which is the current yield to maturity of the BSDEIJ 5.5% 2023’s).
Figure 2: Relative valuation among Indonesian property developer bonds
If the extraordinary resolution is not passed, we still recommend investors to subscribe to Ciputra’s new bond offering. The pandemic situation in Indonesia will improve and the property developer has an adequate amount of liquidity to cover its current borrowings. If required, it may divest part of its IDR 12.76 trillion of inventories for capital.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities.