Note: This is an edited version of an article published earlier on fundsupermart.com.hk on 29 Apr 20.
Highlights:
- Country Garden’s sales performance hit a record-high last year. The Group also continued to maintain a strong cash collection capability.
- The Group's revenue and earnings increased significantly in 2019, with profit margins temporarily unaffected. The overall repayment risks are manageable thanks to its rich land bank and healthy level of leverage.
- Country Garden’s bonds, which are borderline investment-grade were previously under sell-off pressure. The bond yields are now at an attractive level for investors.
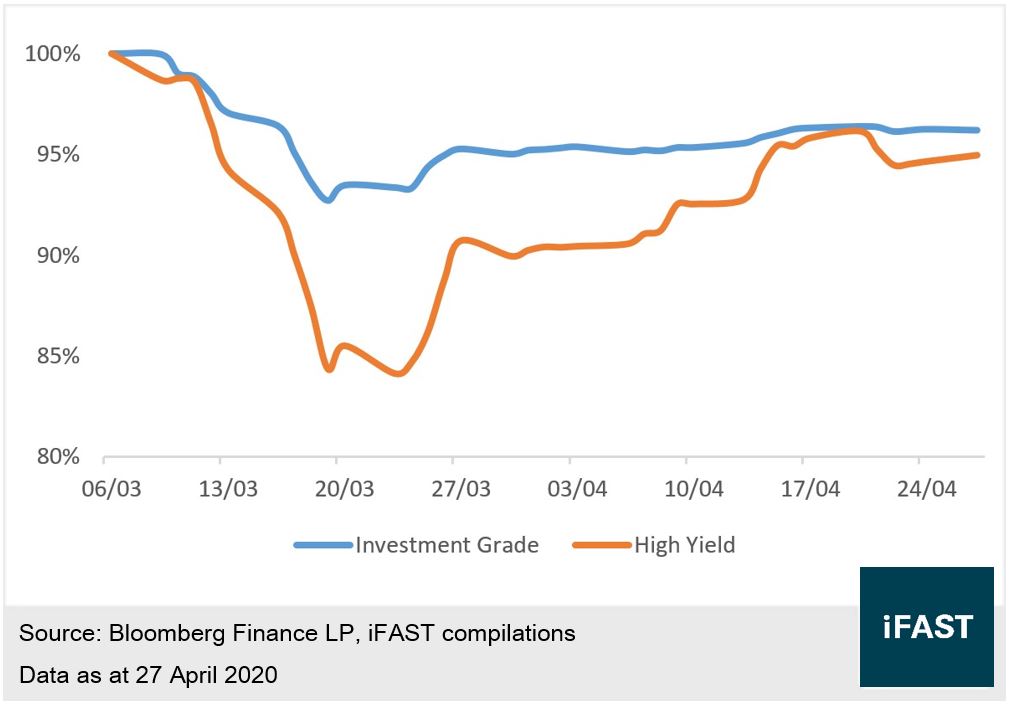
With the recent bond market turmoil, the total return of Chinese real estate investment-grade USD bonds declined over 7% at one point. High yield bonds suffered a greater impact, with the total return hitting a bottom that was down 16% from the previous high (see Chart 1).
Chart 1: Total Return of Chinese Real Estate USD bonds (since 6 March)
Although the prices have stabilised
recently, there are still many opportunities in the market in terms of
investment returns.
Country Garden’s bonds, with a credit rating of BB+/ BBB- (S&P/ Fitch), are currently yielding close to 6% (as at 14 Apr 2020), much higher than the previous 3.6% yield before the crash.
Let’s delve into the credit profile of Country Garden and determine if it is the right time to invest into the Group’s USD bonds.
Company Update
Strong Sales Growth; Dominating the Market Together with Evergrande
In the first half of 2019, Country Garden successfully dominated the sales rankings. However, it was overtaken in the second half of the year when its main rival, China Evergrande, began to accelerate its sales, leaving Country Garden in second place.
Nonetheless, the Group still recorded RMB 552.2 billion (same currency below, unless otherwise specified) of attributable contracted sales in 2019, hitting record high and was up 10% YoY. Their sales also exceeded Vanke’s (the third largest developer in China) by 135 billion. The Group’s sales cash collection amount was as high as 589.9 billion, reflecting their superior cash collection capability.
Significant Increase in Revenue and Earnings while Profit Margins Remain Unaffected
In 2019, Country Garden recorded a revenue and core net profit attributable to shareholders of 485.9 billion and 40.1 billion respectively, up 28.2% and 17.6% YoY, an impressive growth overall.
The Group has a sub-par gross margin because of its strategy to target medium- to low-end residential units in third and fourth-tier cities. However, since the average selling price of properties delivered in 2019 was similar to that in 2018, the Group still maintained a gross margin of 26.1% (2018: 27.0%).
Despite the pressure from the pandemic, Country Garden took on a different strategy from Evergrande and refrained from offering huge discounts. We expect the demand recovery in third and fourth-tier cities to be slower, short term housing prices to remain under pressure and gross margins potentially declining.
In response, we see that the Group is actively reducing expenditures such as overhead expenses. The number of full-time employees at the end of 2019 was approximately 101,784, down 22.5% YoY. We believe that this part will contribute to the Group's core net profit margin, which can alleviate the negative impact of the pandemic.
Rich Land Reserves and Stable Cash Flows
According to the China Index Academy, Country Garden spent 130.3 billion on land acquisition in 2019. Despite ranking second in the industry, such a strategy is not considered very aggressive as this only made up 22.1% of the 590 billion sales cash collection over the same period.
With reference to CRIC statistics, although the total construction area of land bank fell slightly from 2018, the value of saleable resources increased by 30 billion to a total of 1.66 trillion. This huge amount of land will continue to support the Group’s sales in the upcoming three to four years.
Country Garden has recorded positive cash flows from operating activities for four consecutive years, displaying its stable operating conditions. Steady cash flows will be crucial in maintaining the Group’s credit status.
Healthy Credit Profile
At the end of 2019, Country Garden’s net gearing was 55.6%, far below the industry average and even better than the median of BBB-graded issuers in June last year (63%). The overall leverage level is healthy (see Table 1).
The cash and cash equivalents held by the Group increased by 9.0% YoY to 249 billion, while the size of short term debt was reduced to 116.5 billion (end-2018: 126.1 billion). Thus, the cash to short term debt ratio increased to 2.14x, reflecting a strong liquidity position. In addition, from January to March this year, the Group issued several MYD and USD bonds. The two USD bonds with large issuing sizes have maturity dates of seven and ten years respectively, further improving the overall debt structure.
The high asset to liability ratio of about 88.5% has been a concern for many investors. While contracted liabilities (houses sold but not yet delivered) accounted for a large portion, investors should note that such liabilities will not incur cash outflows. Given its 1.5x adjusted current ratio, the Group has sufficient capacity to meet its non-debt expenses.
Amidst the pandemic, we believe that large size developers will remain dominant. As Country Garden still has an unused bank credit facility of 316.8 billion, its liquidity and credit status will be strong enough to withstand the impact brought by the pandemic.
Table 1: Country Garden’s Key Credit Metrics
|
2019 |
2018 |
|
|
Cash and Cash Equivalents (in billion RMB) |
249.0 |
228.3 |
|
Net Gearing (%) |
55.6% |
57.7% |
|
Cash to Short Term Debt (times) |
2.14x |
1.81x |
|
Net Debt / EBITDA (times) |
1.29x |
1.28x |
|
EBITDA / Cash Interest Expense (times) |
3.85x |
4.08x |
|
Source: Annual Results, iFAST Compilations Data as at 31 December 2019 |
||
Bond Yield Becomes More Attractive
With the recent sell-off, Country Garden’s USD bond yields have risen lately. The table below lists some of the bonds available on Bondsupermart (see Table 2).
Table 2: Country Garden’s Bonds
|
Bond Name |
Years to Maturity |
YTM |
|
2.24 |
5.54% |
|
|
2.72 |
5.44% |
|
|
3.42 |
5.56% |
|
|
3.75 |
6.16% |
|
|
4.72 |
6.10% |
|
|
6.63 |
5.61% (Puttable in 2021) |
|
|
Source: BSM Data as at 28 April 2020 |
||
Although the yields are gradually recovering, the investment returns remain attractive. Some investors may worry that a large-scale wave of credit downgrade has yet to come, which will result in the sell-off from index-tracking funds and a fluctuation of short term bond prices. However, we believe that the price volatility is temporary, and issuers’ solvency should be the most crucial in bond investment. Hence, investors should focus on yield to maturity instead.
With the belief that Country Garden’s debt repayment risk is manageable, we think that investors can choose the bonds due in different years to suit their investment horizons and required returns.
Other Risks
For investors who wish to capture short term price gains, it is important to note that a downgrade in Country Garden’s credit will affect its short term bond prices.
Although the regulating policies of different cities have loosened recently, the overall policy direction still points to “stabilizing the housing market”. The limited upside in housing prices may affect Country Garden due to its generally low gross margin.
Declaration:
For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a principal position in COGARD 6.600% 23Feb2023 Corp (MYR). The analyst who produced this report hold a NIL position in the abovementioned securities.