Country Garden Progresses in Restructuring
On 9 January 2025, Country Garden disclosed the latest developments in its offshore debt restructuring and business operations. The Group reached a consensus with the co-ordination committee (comprising seven banks controlling 48% outstanding principal amount of three syndicated loans) on key terms of the restructuring plan. The Group anticipates that the restructuring plan will reduce its offshore debt by up to USD 11.6 billion, equivalent to 70% of the total offshore debt (approximately USD 10.3 billion in bonds, USD 3.6 billion in syndicated loans, USD 1.1 billion in shareholder loans, and around USD 1.4 billion in other offshore debt).
The restructuring options and key terms are as follows (refer to Table 1):
Table 1: Restructuring Options
Option | Instrument | Key Terms |
Option One | Cash | Minimum 90% principal haircut |
Option Two | Mandatory Convertible Bonds | 100% principal converted into mandatory convertible bonds with a tenure of 3.5 years |
Option Three | Mandatory Convertible Bonds and New Debt Instruments | 67% principal converted into mandatory convertible bonds with a tenor of 7.5 years |
Option Four | New Debt Instruments | 35% principal haircut, new debt instruments with a tenor of 9.5 years |
Option Five | New Debt Instruments | No principal haircut, new debt instruments with a tenor of 11.5 years |
Source: Company’s Announcement, iFAST compilations | ||
- The restructuring covers existing offshore bonds, syndicated loans and other financing.
- Most new debt instruments have early redemption schedules, with tenors ranging from 7.5 to 11.5 years.
- Investors can receive new debt instruments in the form of bonds or loans.
- Options with equity conversion and principal haircuts (Options Three and Four) are expected to have shorter weighted average maturities compared to new debt instruments without principal haircut (Option Five).
- New debt instruments include payment in kind, with the new debt instruments of Options Three and Four having higher coupon rates than Option Five.
- The credit support package applies to all new debt instruments, including subsidiary guarantees and pledges over shares of subsidiaries, cash sweep of specific assets, and other potential credit enhancement.
Country Garden estimates that over the next 15 years, the Group can generate net cash surplus of approximately RMB 20-25 billion from onshore projects and non-core assets, levered free cash flow of approximately USD 2.6-3.0 billion from offshore projects and raise approximately USD 600-800 million from the sales of offshore financial investments. Additionally, the Group plans to deposit around USD 140 million (which are the proceeds from offshore minority financial investments) for the sake of providing funds for the restructuring plan.
Based on the above cash flow assumptions, Country Garden proposed the above restructuring options and key terms. However, it is important to note that the co-ordination committee only represents a portion of offshore creditors. According to Bloomberg news, this restructuring plan is not yet approved by the ad-hoc Group of USD bondholders, which currently holds more than USD 3 billion in principal amount of bonds. This indicates that it still needs time to formally implement and execute the plan.
Operational Update
On 1 April, 2024, Country Garden failed to announce its 2023 year result on time. Its stock (Stock Code: 2007.HK) suspended ever since. However, on 14 January, 2025, the Group successfully released the results, including the 2023 annual result and the 2024 interim result. It signals that the resumption of stock trading should be imminent, potentially accelerating the progress of the restructuring.
As of the end of 2023, Country Garden held over 3,000 real estate projects (including 29 offshore projects) with a saleable area of 90-92 million square meters and around 1.3-1.4 million carpark units available for sale.
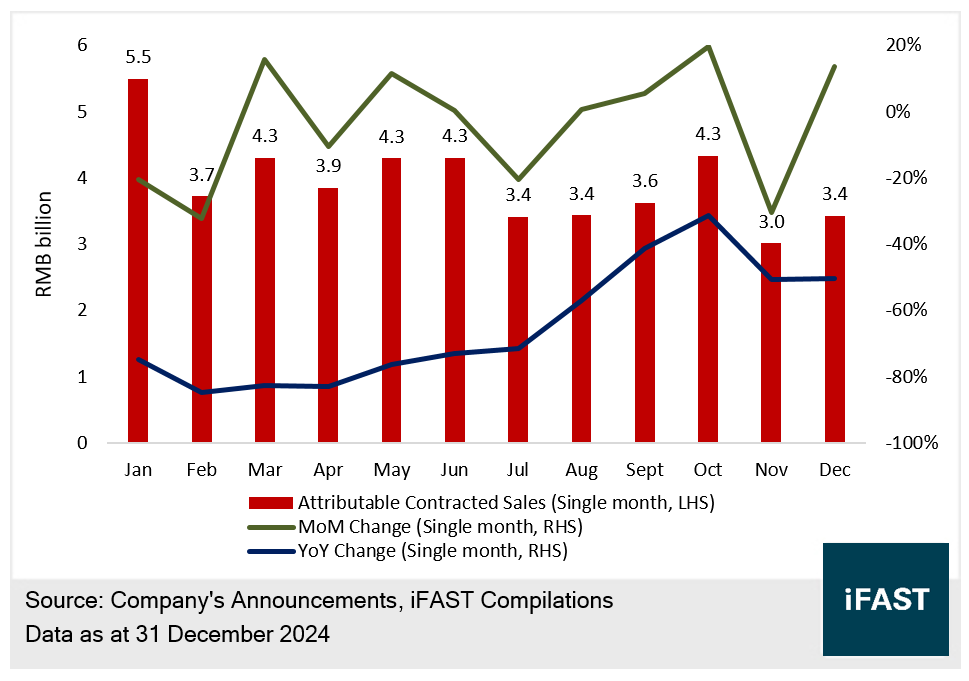
In 2024, Country Garden's attributable contracted sales amounted to RMB 47.2 billion, a significant YoY decline of 73%. The Group's recent monthly sales were only RMB 3 to RMB 4.3 billion (see Chart 1), a stark contrast to the monthly sales of at least RMB 20 billion before the Group’s default.
Chart 1: Country Garden's Monthly Attributable Contracted Sales in 2024
Country Garden generated a net loss to shareholders of RMB 178.4 billion and RMB 12.8 billion in 2023 and the first half of 2024 respectively. As of the end of June 2024, its total debt and total equity were around RMB 205.4 billion and around RMB 74.1 billion. Its adjusted liability to asset ratio and net gearing ratio were 91% and 277% respectively, indicating it has not reached the stage of insolvency.
Given that the quality of Country Garden's balance sheet before default is superior to many peers’, the recovery value of offshore bonds is expected to be better than many peers if the group successfully completes the offshore debt restructuring.
Subsequent Developments Remain Highly Uncertain
Currently, Country Garden still faces several challenges, including its oversized scale (with total assets amounting to RMB 1.2 trillion and few peers being capable of acquiring the sizable assets), a large number of creditors (whose interests may not align, leading to taking more time in negotiation of restructuring), weak sales (only one-tenth of pre-default levels), and the threat of winding-up petition, indicating that subsequent developments remain highly uncertain.
It was reported that Country Garden's controlling shareholder (Mr. Yeung Kwok Keung family) intends to convert their USD 1.1 billion shareholder loan into Country Garden’s stocks and equity stake in the Forest City project. They propose converting half of the shareholder loan into Country Garden stocks and the other half into a 60% stake in the Forest City project currently held by the Group. If these reports are accurate, it suggests that the offshore restructuring plan might not be unanimously beneficial to all creditors and could potentially harm the interests of other creditors.
However, this indicates that the controlling shareholder has a higher incentive to push forward with the restructuring and further restore operational and sales abilities, as successful completion of the restructuring would allow them to obtain equity stake in the Forest City project, and the improving operating performances would allow them to have benefits in potential stock rebounds. Therefore, we believe Country Garden will swiftly launch the restructuring plan, seek the support of creditors to avoid liquidation order and look for continuous operations.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds positions in COGARD 6.500% 08Apr2024 Corp (USD) and the analyst who produced this report hold a NIL position in the abovementioned securities.