


Company overview
DRB-Hicom is one of Malaysia’s largest and most diversified conglomerates, with core businesses spanning the Automotive, Aerospace & Defence, Banking, Postal Services and Properties sectors. The Group’s Automotive segment is one of the most comprehensive automotive businesses in Malaysia, with operations covering vehicle manufacturing, assembly and distribution, including motorcycles. It also remains the Group’s largest contributor to revenue and earnings.
The Group’s most prominent local and international brand is Proton, Malaysia’s national car marque, in which it holds a 50.1% stake, with the remaining 49.9% held by China’s Geely. Additionally, DRB-Hicom holds a 70.0% stake in Bank Muamalat Malaysia Bhd and a 53.5% stake in Pos Malaysia Bhd, providing the Group with diversified earnings streams across the automotive, financial services and postal sectors.
As at 06 Oct 2026, the three largest shareholders were:
Etika Strategi Sdn Bhd: 55.92%. This is the controlling shareholder, in which Tan Sri Syed Mokhtar Shah bin Syed Nor holds a deemed interest.
Employees Provident Fund Board: 8.48%, per the register of substantial shareholders.
Lembaga Tabung Haji: 3.67%.
Industry Outlook
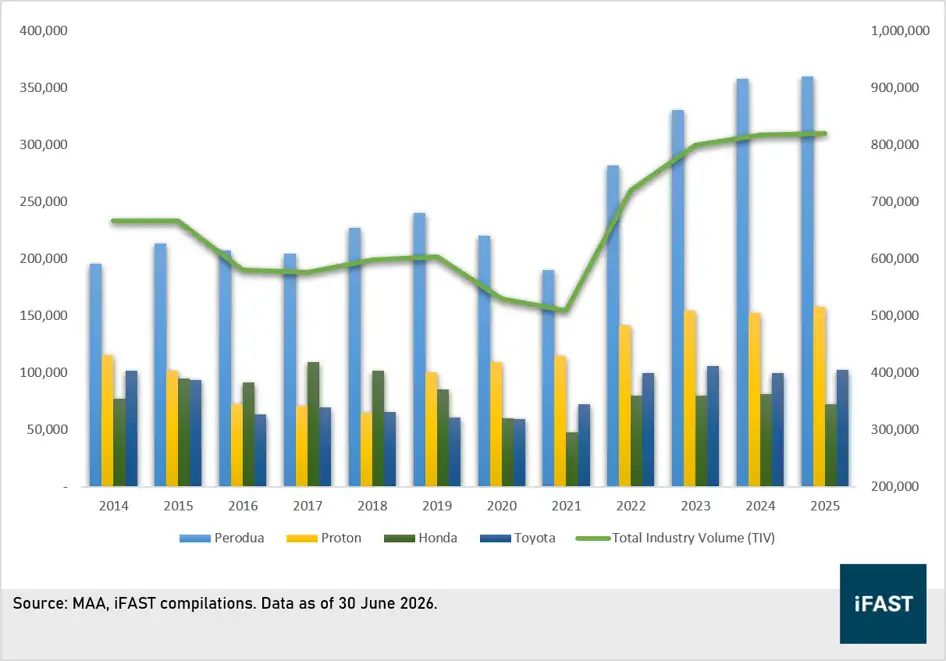
The Malaysian automotive market achieved a record-high Total Industry Volume (TIV) of 820,752 units in 2025, representing a 0.5% YoY increase from 2024. Growth was primarily supported by resilient domestic demand and favourable financing conditions, following the interest rate cut to 2.75% in July 2025.
In 1H2026, the automotive industry maintained its positive momentum, with TIV increasing by 3.0% YoY to 385,353 units. In view of the continued resilience in the automotive market, the Malaysia Automotive Association (MAA) subsequently revised its full-year 2026 TIV forecast upwards to 800,000 units, from its previous forecast of 790,000 units. The upward revision was mainly underpinned by relatively stable economic conditions, including healthy employment, household income and domestic demand, despite the uncertainties arising from geopolitical developments in the Middle East.
As shown in the chart below, domestic marques continue to dominate the Malaysian automotive market, with Perodua accounting for approximately 41% of total TIV, followed by Proton at around 25%.
Looking ahead, we expect the revised policy on completely built-up (CBU) electric vehicles (EVs), effective 1 July 2026, to reshape competitive dynamics in Malaysia’s automotive industry. The policy requires imported CBU EVs to meet a minimum cost, insurance and freight (CIF) value of RM200,000 and a minimum motor output of 180kW, effectively excluding imports from the mass-market segment. This should favour incumbents with established local assembly capacity, such as Proton and Perodua, while encouraging foreign EV marques to set up local assembly operations in Malaysia
Nevertheless, we expect domestic marques to maintain their strong market position, supported by relatively affordable pricing and increasingly competitive model offerings. Proton, in particular, has continued to expand its product portfolio with the launch of several new models in 2026. For instance, the Proton S70 NA reportedly garnered more than 10,000 bookings within just two weeks of the order books opening on 7 September 2026, highlighting strong consumer interest and continued demand for Proton’s latest offerings.
Chart 1: Malaysia Total Industry Volume (TIV)
Not Limited to Proton, DRB-Hicom Has Captured a Significant Share of Malaysia’s Automotive Market
Beyond the ownership of Proton, DRB-HICOM is holding stakes in other renowned automotive marques as well, including Honda Malaysia, Isuzu Malaysia, Mitsubishi Motors Malaysia and more. The group maintains a significant presence in the industry with 35.2% of TIV Malaysia as of 30 June 2026. Among its brands, Proton and Honda have delivered strong performances in Malaysia, while Isuzu and Mitsubishi seem lackluster.
Financial Performance
In 1HFY26, DRB-Hicom recorded solid revenue growth, with revenue increasing 24.4% YoY to RM10.26 billion, mainly driven by improved contributions across most of the Group’s segments, with the exception of the Properties segment. Mobility remained the key growth driver, contributing RM1.96 billion to the overall increase as segment revenue grew 32.5% YoY to RM7.99 billion. Proton sold 100,346 units in 1HFY26, representing a 39.1% YoY increase and its strongest first-half performance in 15 years, significantly outperforming the industry’s 3.1% growth. The Group also benefited from higher aerospace revenue following the acquisition of CTRM AeroSystems in December 2025, as well as improved automotive distribution performance.
Cost of sales and operating expenses increased by 23.3% YoY to RM9.94 billion, slightly below the pace of revenue growth. Consequently, the operating profit margin improved modestly to 4.7%, from 4.1% in 1HFY2025, supported by stronger sales and improved cost management. Earnings were also aided by several positive operating and non-recurring factors, including a 6.7% decline in depreciation expenses to RM304.9 million and a RM28.2 million net mark-to-market gain on derivatives, compared with a RM35.3 million loss in the previous corresponding period.
Overall, profit before tax increased by 57.8% YoY, primarily driven by stronger contributions from the Mobility and Postal segments. Looking ahead, we remain cautiously optimistic about DRB-Hicom’s outlook, supported by Proton’s continued rollout of new models, strong order intake and favourable sales momentum. These factors should continue to support the Group’s operating performance, although competitive pressures in the domestic automotive market remain a key consideration.
Table 1: Profitability indicators (RM’ million)
|
1HFY2025 |
1HFY2026 |
Change in % |
|
|
Revenue |
8,250 |
10,264 |
24.4% |
|
Profit before tax |
216 |
341 |
57.8% |
|
Operating profit margin (%) |
4.1% |
4.7% |
Source: Company Reports, iFAST Compilations. Data as of 30 June 2026.
Table 2: Revenue by segments (RM’ million)
|
1HFY2025 |
1HFY2026 |
Change in % |
|
|
Mobility |
6,025 |
7,986 |
32.5% |
|
Postal |
890 |
965 |
8.3% |
|
Banking |
1,090 |
1,183 |
8.6% |
|
Services |
103 |
106 |
2.8% |
|
Properties |
141 |
24 |
(82.8%) |
Source: Company Reports, iFAST Compilations. Data as of 30 June 2026.
Credit profile
From a credit perspective, DRB-Hicom’s borrowings remained relatively stable at approximately RM8.4 billion in 1HFY2026, broadly in line with FY2025. This follows an increase of around RM1.0 billion in borrowings during FY2025, comprising a combination of bank borrowings and sukuk issuance, primarily to fund the acquisition of Spirit AeroSystems by its subsidiary, CTRM, as well as capital expenditure for the development of the manufacturing ecosystem in Tanjong Malim.
Nevertheless, the Group’s net debt-to-equity ratio improved to 0.39x in 1HFY2026, supported by higher cash and cash equivalents. This indicates that the Group’s net leverage remains well managed despite the increase in borrowings over the previous financial year.
From a liquidity perspective, we believe the Group remains in a strong position, with cash covering approximately 2.0x of its short-term debt and an interest coverage ratio of 4.35x. These metrics indicate that the Group has a comfortable liquidity buffer and strong debt-servicing capacity at this juncture, suggesting that near-term credit risk remains manageable.
Table 3: Credit metrics (RM’ million)
|
RM million |
2022 |
2023 |
2024 |
2025 |
1HFY2026 |
|
Cash and cash equivalents |
2,187.9 |
2,024.5 |
2,133.9 |
2,739.1 |
3,811.4 |
|
Operating cash flow |
245.4 |
4,063.7 |
1,401.3 |
2,500.9 |
940.7 |
|
Short-term borrowings |
1,812.7 |
1,436.9 |
1,068.7 |
1,636.1 |
1,879.4 |
|
Long-term borrowings |
6,134.4 |
5,762.7 |
6,211.1 |
6,713.2 |
6,521.0 |
|
Net debt-to-equity ratio (x) |
0.59 |
0.49 |
0.50 |
0.52 |
0.39 |
|
Cash to short-term debt (x) |
1.21x |
1.41x |
2.00x |
1.67x |
2.03x |
|
Interest coverage ratio (x) |
2.97x |
3.15x |
3.27x |
4.18x |
4.35x |
Source: Company Reports, iFAST Compilations. Data as of 30 June 2026.
For the banking segment, Bank Muamalat’s credit profile remains solid despite a decline of 26.4% YoY in profit after zakat and tax (PAZT) to RM88.8 million, while top-line revenue rose slightly by 6.9% YoY to RM1,203 million. The bank’s CET1 ratio improved to 12.02% (30 June 2025: 11.14%), well-above the minimum regulatory requirements of 4.5%
Key Risk
iIntense Competition within the Auto Industry
DRB-HICOM will continue to face intense competition in the automotive market from established players such as Perodua, Toyota, as well as emerging electric vehicle brands such as BYD. These brands offer competitively priced vehicles with increasingly advanced technology and features, which could intensify competitive pressures in the domestic automotive market.
Nonetheless, we remain relatively positive on Proton and DRB-Hicom at this juncture, given Proton’s active rollout of new models featuring competitive technology at affordable price points. For instance, the new Proton S70, a C-segment sedan, is priced at around RM60,000, offering consumers a combination of affordability and modern features.
Our view
To summarise, DRB-Hicom’s business operations remain healthy at this juncture, despite the lower contribution from the Properties segment, which is not significant at the Group level.
Looking ahead, the Automotive segment is expected to remain the Group’s key revenue contributor, accounting for approximately 78% of revenue in 1HFY2026. We maintain a positive view of the segment, given its continued launch of new models to remain competitive, coupled with DRB-Hicom’s strong order intake for its newly launched models.
Considering the Group’s resilient operating performance and healthy liquidity position, investors may consider continuing to hold DRB-Hicom’s issuances.
For investors interested in DRB-Hicom issuances, we favour DRBHMK 5.570% 26Apr2030 Corp (MYR) and DRBHMK 5.100% 12Dec2029 Corp (MYR), offering yields of 4.37% and 4.33% respectively. (availability subject to market conditions)
Table 4: Recommended Bonds***
|
Bond |
Years to call / maturity |
Yield to next call / maturity |
Min / Sub |
|
- / 1Y10M |
- / 4.03% |
MYR 5,000 / 5,000 |
|
|
- / 3Y2M |
- / 4.33% |
MYR 1,000 / 1,000 |
|
|
- / 3Y6M |
- / 4.37% |
MYR 5,000 / 5,000 |
|
|
1Y10M / - |
4.59% / - |
MYR 250,000 / 250,000 |
Source: BSM, iFAST Compilations. Data as of 12 Oct 2026.
***Liquidity subject to market conditions
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in DRBHMK 5.100% 12Dec2029 Corp (MYR) and DRBHMK 4.850% 04Aug2028 Corp (MYR) and the analyst who produced this report hold a NIL position in the abovementioned securities.