Every year, Azalea Asset Management conducts an Investor Day to reach out to bondholders. This year, the Investor Day was held online and Azalea provided an update about the performance of the various Astrea private equity bonds. Investors who missed the event webcast may view it at their website here.
Azalea is a wholly-owned subsidiary of Seviora Holdings Pte. Ltd., and indirectly owned by Temasek Holdings (Private) Limited. Set up in 2015, Azalea has its own board and management team independent of Temasek. The company is focused on the development and creation of investment products to provide investors a wider access to private equity.
Last year, Azalea Asset Management grew its AuM from USD 6b to approximately USD 9b. In March 2021, Azalea launched Astrea VI and issued USD 643m of bonds. At the end of 2021, Azalea also closed Altrium II, its second fund of funds flagship product and raised USD 805m.
Private equity performance in 2021
Private equity returns recovered sharply last year after falling in 2020. According to Hamilton Lane, fund raising activity in private markets accelerated early last year, and is expected to make a new annual record in 2021. Following Preqin estimates, private equity assets under management surged to USD 7.6t in June 2021, which translates to an annualised growth rate of 12.8% since 2000.
With such strong interest from investors, the amount of dry powder available to PE fund managers grew to approximately USD 1.2t in 2021. Buyout valuations have maintained at a high level due to the large amount of available dry powder. For instance, EV/EBITDA multiples for US buyouts stayed around 12.8x in 2021, similar to the level in 2020 and slightly higher than 12.4x in 2018.
Astrea III update
Astrea III fully redeemed its Class C bonds on its eleventh distribution date on 8 January 2022. Having said that, all classes of the Astrea III bonds have been redeemed. The portfolio recorded USD 38m of fair value gains and ended with a NAV of USD 378m. There were USD 2m of capital calls and USD 105m of distributions were made.
Astrea IV update
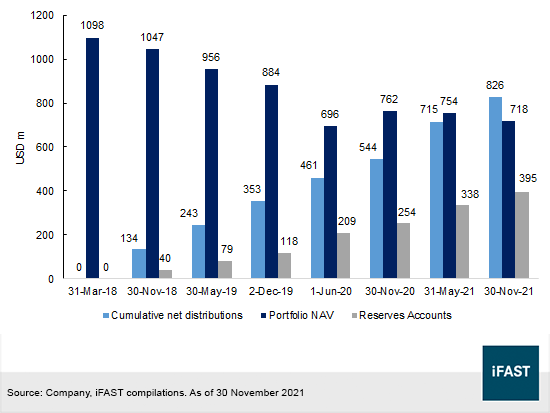
During the seventh distribution period from 15 June 2021 to 14 December 2021, the Astrea IV portfolio paid out USD 115m of distributions. After accounting for USD 4m of capital calls, USD 111m were applied to the priority of payments. The performance threshold was met in the sixth distribution period, which meant that the sponsor was entitled to additional cash flows under Clause 14iii and Clause 14iv of the priority of payments.
Out of the USD 111m, USD 24m was directed to the reserves accounts. As a result, the total value of the reserves accounts increased to USD 395m. With USD 395m in the accounts, there is sufficient capital to pay down the Class A-1 (outstanding amount: SGD 242m) and Class A-2 bonds (USD 210m) on their scheduled call date on 14 June 2023.
As of 27 January 2022, the Class A-1 bonds, ASTLC 4.350% 14Jun2028 Corp (SGD) - Class A-1 – Retail, are trading at a yield-to-worst (“YTW”) of 0.44%. Class A-1 bondholders will be paid an extra 0.5% upon redemption because the performance threshold was met.
Class A-2, or ASTLC 5.500% 14Jun2028 Corp (USD) - Class A-2 are trading at an indicative yield-to-worst of 0.82%. In the meantime, Class B, ASTLC 6.750% 14Jun2028 Corp (USD) - Class B have an indicative yield-to-worst of 2.02%.
Figure 1: Astrea IV portfolio NAV and reserves accounts
Astrea V update
Astrea V portfolio NAV increased from USD 1,324m in March 2019 to USD 1,479m in December 2021. During this period, the portfolio recorded USD 747m of cumulative distributions. For the most recent distribution period from 21 June 2021 to 20 December 2021, a net distribution amount of USD 200m was applied to the priority of payments.
Figure 2: Astrea V portfolio NAV and reserves accounts
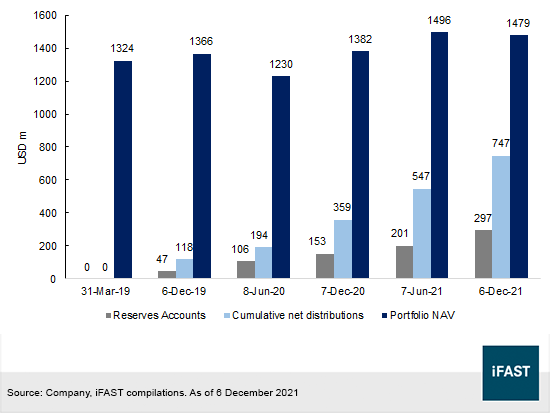
Astrea V met its USD 407m performance threshold after paying USD 38m to the sponsor. As a result, Class A-1 bondholders of the ASTLC 3.850% 20Jun2029 Corp (SGD) - Class A-1 will receive a 0.5% bonus upon its call date on 20 June 2024. With USD 297m in the reserves accounts, there is more than enough reserves to redeem the SGD 315m of Class A-1 bonds on its call date on 20 June 2024.
As of 27 January 2022, the ASTLC 3.850% 20Jun2029 Corp (SGD) - Class A-1 were trading at an indicative yield-to-worst of 2.31%. Class A-2, or the ASTLC 4.500% 20Jun2029 Corp (USD) - Class A-2 have an indicative YTW of 2.15%. Class B bonds (ASTLC 5.750% 20Jun2029 Corp (USD) - Class B) have an indicative YTW of 3.56%.
Astrea VI update
Astrea VI’s latest update was in September 2021. The Astrea VI portfolio paid out USD 309m of distributions and made USD 21m of capital calls. This resulted in a net distribution amount of USD 288m that was applied to the priority of payments.
Figure 3: Astrea VI portfolio performance
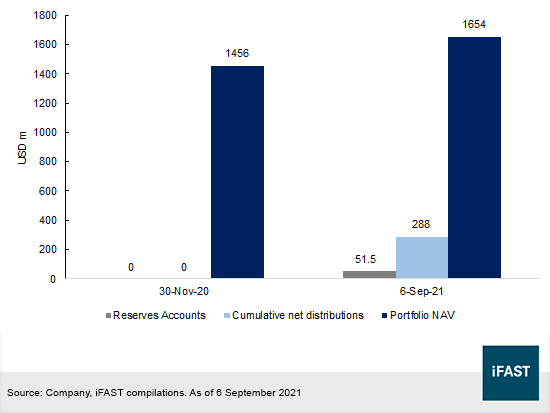
The portfolio climbed from USD 1456.2m to USD 1,654.1m in a span of 9 months. Due to its healthy performance, there was no need to draw down on its credit facility. USD 51.5m was paid to the reserves accounts. With just USD 51.5m in the accounts, the value is much smaller than the outstanding amount of SGD 382m for the Class A-1 bonds.
However, the track records of Astrea IV and Astrea V show that the likelihood of redemption is high. If not redeemed on its scheduled call date, the coupon rate for the bonds will step up by 1%.
As of 27 January 2022, Astrea VI Class A-1 bonds are trading at an indicative yield-to-worst of 2.51%. ASTLC 3.250% 18Mar2031 Corp (USD) - Class A-2, meanwhile have an indicative YTW of 3.14%. Astrea VI Class B bonds, ASTLC 4.350% 18Mar2031 Corp (USD) - Class B have an indicative YTW of 4.12%.
Astrea VII?
With the exception of 2020, Azalea has issued new PE bonds over the last few years. When asked about a potential Astrea VII issue during the Q&A, management said that the launch of new bonds this year would depend on market conditions and investor interest.
In our opinion, Astrea PE bonds are suitable for stable income seekers. The bond sponsors are indirect subsidiaries of Azalea, who is indirectly owned by Temasek Holdings. We believe that the diversified nature of the underlying private equity portfolios and structural safeguards of the bonds would help to offset the investment downside risks. As a summary, Table 1 shows the respective latest bond yields for the different Astrea PE bonds.
Table 1: Outstanding Astrea PE bonds
|
Bond |
Outstanding amount |
Indicative YTW |
|
|
Astrea IV |
ASTLC 4.350% 14Jun2028 Corp (SGD) - Class A-1 - Retail |
SGD 242m |
0.44% |
|
Astrea IV |
ASTLC 5.500% 14Jun2028 Corp (USD) - Class A-2 |
USD 210m |
0.82% |
|
Astrea IV |
ASTLC 6.750% 14Jun2028 Corp (USD) - Class B |
USD 110m |
2.02% |
|
Astrea V |
ASTLC 3.850% 20Jun2029 Corp (SGD) - Class A-1 - Retail |
SGD 315m |
2.31% |
|
Astrea V |
ASTLC 4.500% 20Jun2029 Corp (USD) - Class A-2 |
USD 230m |
2.15% |
|
Astrea V |
ASTLC 5.750% 20Jun2029 Corp (USD) - Class B |
USD 140m |
3.56% |
|
Astrea VI |
ASTLC 3.000% 18Mar2031 Corp (SGD) - Class A-1 - Retail |
SGD 382m |
2.51% |
|
Astrea VI |
ASTLC 3.250% 18Mar2031 Corp (USD) - Class A-2 |
USD 228m |
3.14% |
|
Astrea VI |
ASTLC 4.350% 18Mar2031 Corp (USD) - Class B |
USD 130m |
4.12% |
| Source: Company, Bondsupermart.com, iFAST compilations. As of 27 January 2022 | |||
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in ASTLC 3.250% 18Mar2031 Corp (USD) - Class A-2 and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!