Company Background
The Straits Trading Company Limited (“STC”) is a conglomerate-investment company with operations across various business segments such as 1) resources, 2) real estate, 3) hospitality, and 4) others. The Group reports revenue in these four operating segments.
STC operates a large property segment comprising of wholly-owned developers and investment companies such as Straits Development Pte. Ltd., STC Property Management Sdn. Bhd., Straits Real Estate Pte. Ltd., and Straits Investment Management Pte. Ltd. The Group’s resources segment comprised of its 52%-owned subsidiary, Malaysia Smelting Corporation (“MSC”), which is listed on both the Singapore Exchange and Bursa Malaysia.
STC’s hospitality segment is mainly driven by Far East Hospitality Holdings Pte Ltd (“FEHH”), which is a 30%-owned joint venture with Far East Orchard Limited. The Group’s others segment comprises Group-level corporate and treasury services as well as securities and other investments. STC has a 14% interest in the digital securities exchange, SDAX Financial.
Higher expenses weighed on profits while revenue continue to grow
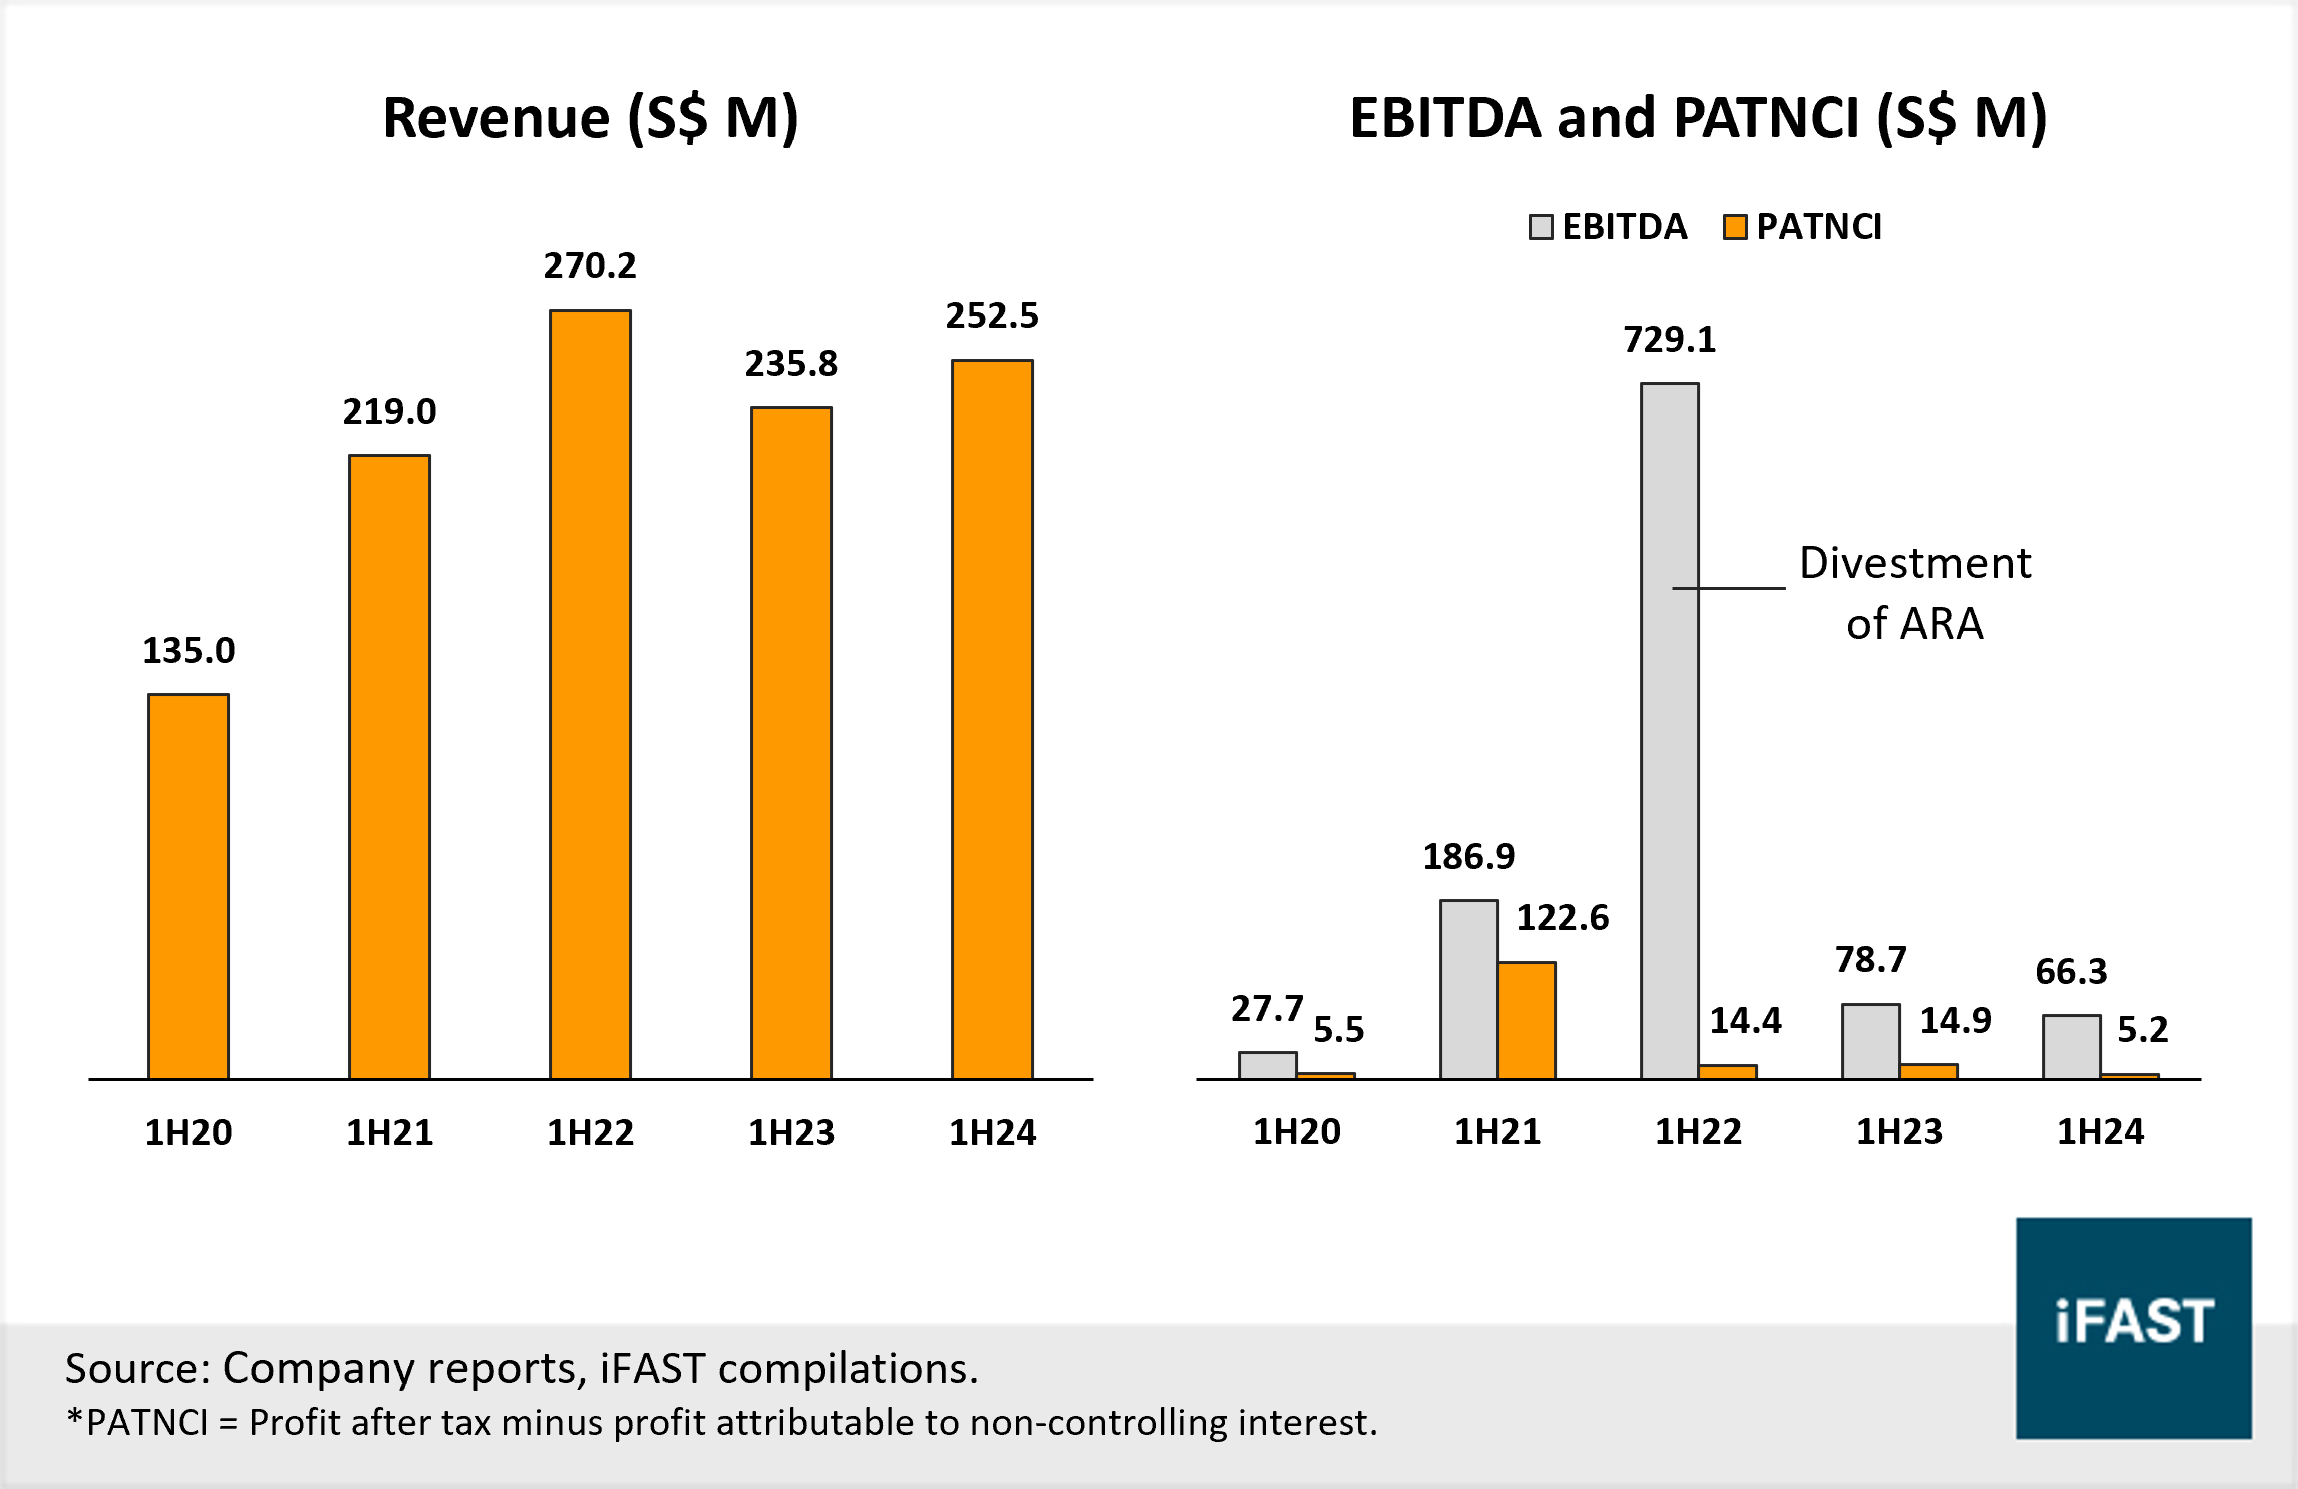
For the six months ended 30 June 2024 (“1H24”), STC reported a 7.1% year-on-year (YoY) growth in revenue to S$252.5M from S$235.8M (1H23). This was driven by stronger tin mining and smelting revenue as average tin prices rose by nearly 20% YoY. Total revenue, including fair value changes and other incomes, grew 11.8% YoY to S$312.7M from S$279.8M (1H23) due to significant gains (S$43.2M) in fair value of investment properties.
However, STC also reported a 14.6% YoY growth in total expenses, largely from higher costs of tin mining and smelting which make up the bulk of expenses. Finance costs also grew due to the issuance of a S$130.0M 4.70% fixed rate note on 24 January 2024. On balance, larger growth in expenses offset the growth in revenue, driving a 47.0% YoY drop in profit after tax and non-controlling interests (“PATNCI”) to S$14.2M in 1H24 from S$26.8M (1H23).
Chart 1: Revenue for STC has grown by 7% YoY but higher expenses have weighed on PATNCI
Real Estate segment continues to anchor earnings
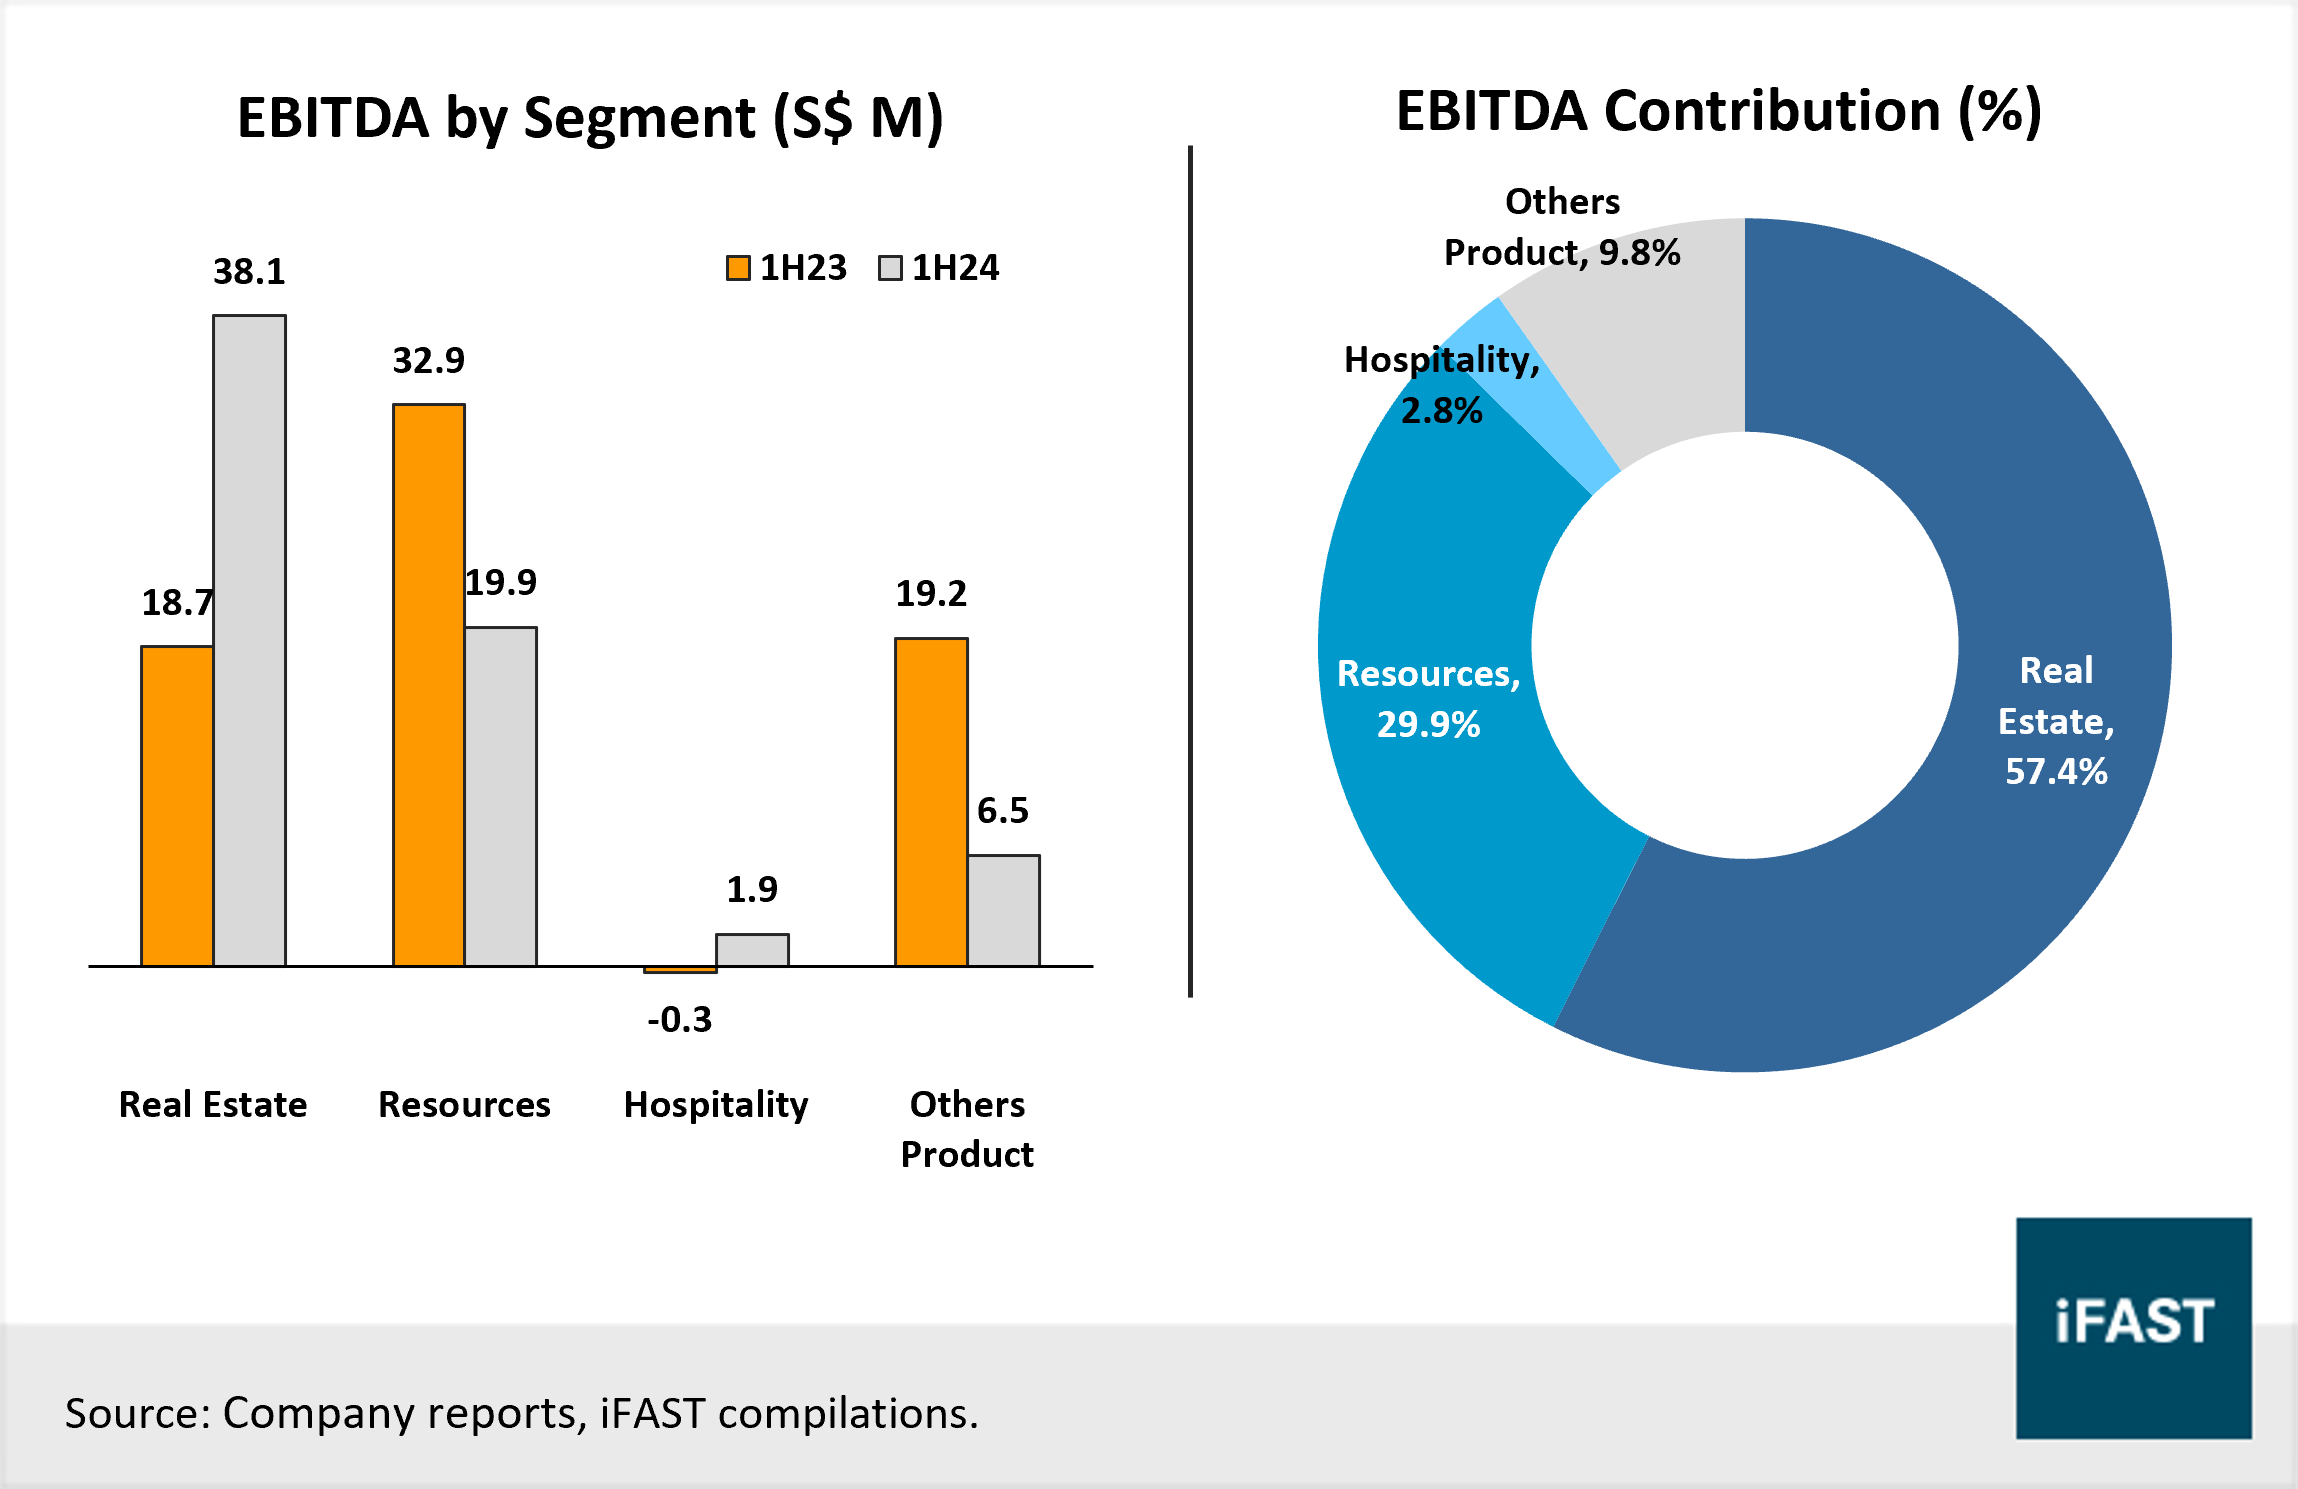
STC’s EBITDA fell -15.7% YoY to S$66.3M in 1H24 from S$78.7M (1H23). This was largely due to a -40% YoY drop in Resources EBITDA to S$19.8M, despite higher average tin prices, as refined tin production fell owing to the maintenance of the furnace interrupting refined tin production. That said, management remains cautious about the outlook for the Resources segment and remains focused on enhancing operational efficiencies and lowering costs. Already, STC has guided that operational and manpower costs are expected to fall for the Pulau Indah smelter while the full closure of Butterworth smelter in 2025 will bring about 30% of cost savings to MSC, as shared by the company’s CEO.
STC’s real estate EBITDA which has historically been the Group’s dominant earnings driver continues to demonstrate steady growth, rising 41.3% YoY to S$38.1M. The growth was largely fuelled by net fair value gains across logistics properties in South Korea and Australia and properties in Singapore. Rental income for the Group remained strong at S$32.4M in 1H24, higher than the estimated 5-year average of S$25.6M since Covid. This was underpinned by strong portfolio occupancy of 90.9% and a positive rent reversion of 8.7% (end-June 2024).
STC Property Management spearheads the development of Straits City, a project on prime land in Penang that is widely touted as a growth catalyst for the state in the Malaysian government's Vision 2030 plan. Phase 1 of this project has been completed, with the newly opened Crowne Plaza Penang hotel, and moving ahead, the Group plans to launch more office, residential, and retail development.
The Hospitality segment registered an EBITDA gain of S$1.9M in 1H24, up from a loss of -S$0.3M (1H23) as travel demand rebounded over the past year. New openings over the past year, including Vibe Melbourne Hotel and Adina Serviced Apartments in Vienna helped support segmental revenue. For the remainder of 2024, FEHH has planned for openings in tourist hotspots (Quincy House Singapore and Ever Hotel Sydney).
Chart 2: STC's real estate segment continues to grow, anchoring the Group's EBITDA
Remain optimistic on STC’s earnings outlook
We retain our positive view on the Group’s outlook since our prior update. While profits have fallen, the Group is likely to remain profitable in our view, and earnings should gradually rebound amidst a recovering macro backdrop. Looking ahead, we see room for Resources segment earnings to recover, backed by successful cost savings in 2025 and beyond, while tin production may rise after the Pulau Indah furnace’s maintenance is complete and as the plant potentially runs at a higher utilisation rate (currently estimated to run at 60 – 70%). We think elevated tin prices in the coming years will prove supportive.
We also expect STC’s real estate segment to remain the anchor for the Group’s earnings. Rental income has proven to be resilient with SRE’s high quality, diversified portfolio and a weighted average lease expiry of 4.7 years suggests stability in income beyond 2028. We also expect rising contributions from the Straits City project with more property launches in the coming years.
Available liquidity alleviates credit risk in the near term
Total borrowings rose slightly by 6.3% HoH to S$1.7B in 1H24 due to the 4.70% fixed rate note issuance which drove long-term borrowings higher to S$1.5B. However, cash from this issuance has also contributed to the Group’s overall cash balance and partially helped repay existing bank loans.
As at the end of June 2024, STC has an estimated available liquidity of S$857.7M, comprised of an unrestricted cash balance of S$463.5M and S$394.2M from other liquid assets, including its 4% stake in ESR Group. With the available liquidity adequately covering the near-term debt of S$225.0M, we see little near-term liquidity hurdle for STC.
Capital structure remains decent
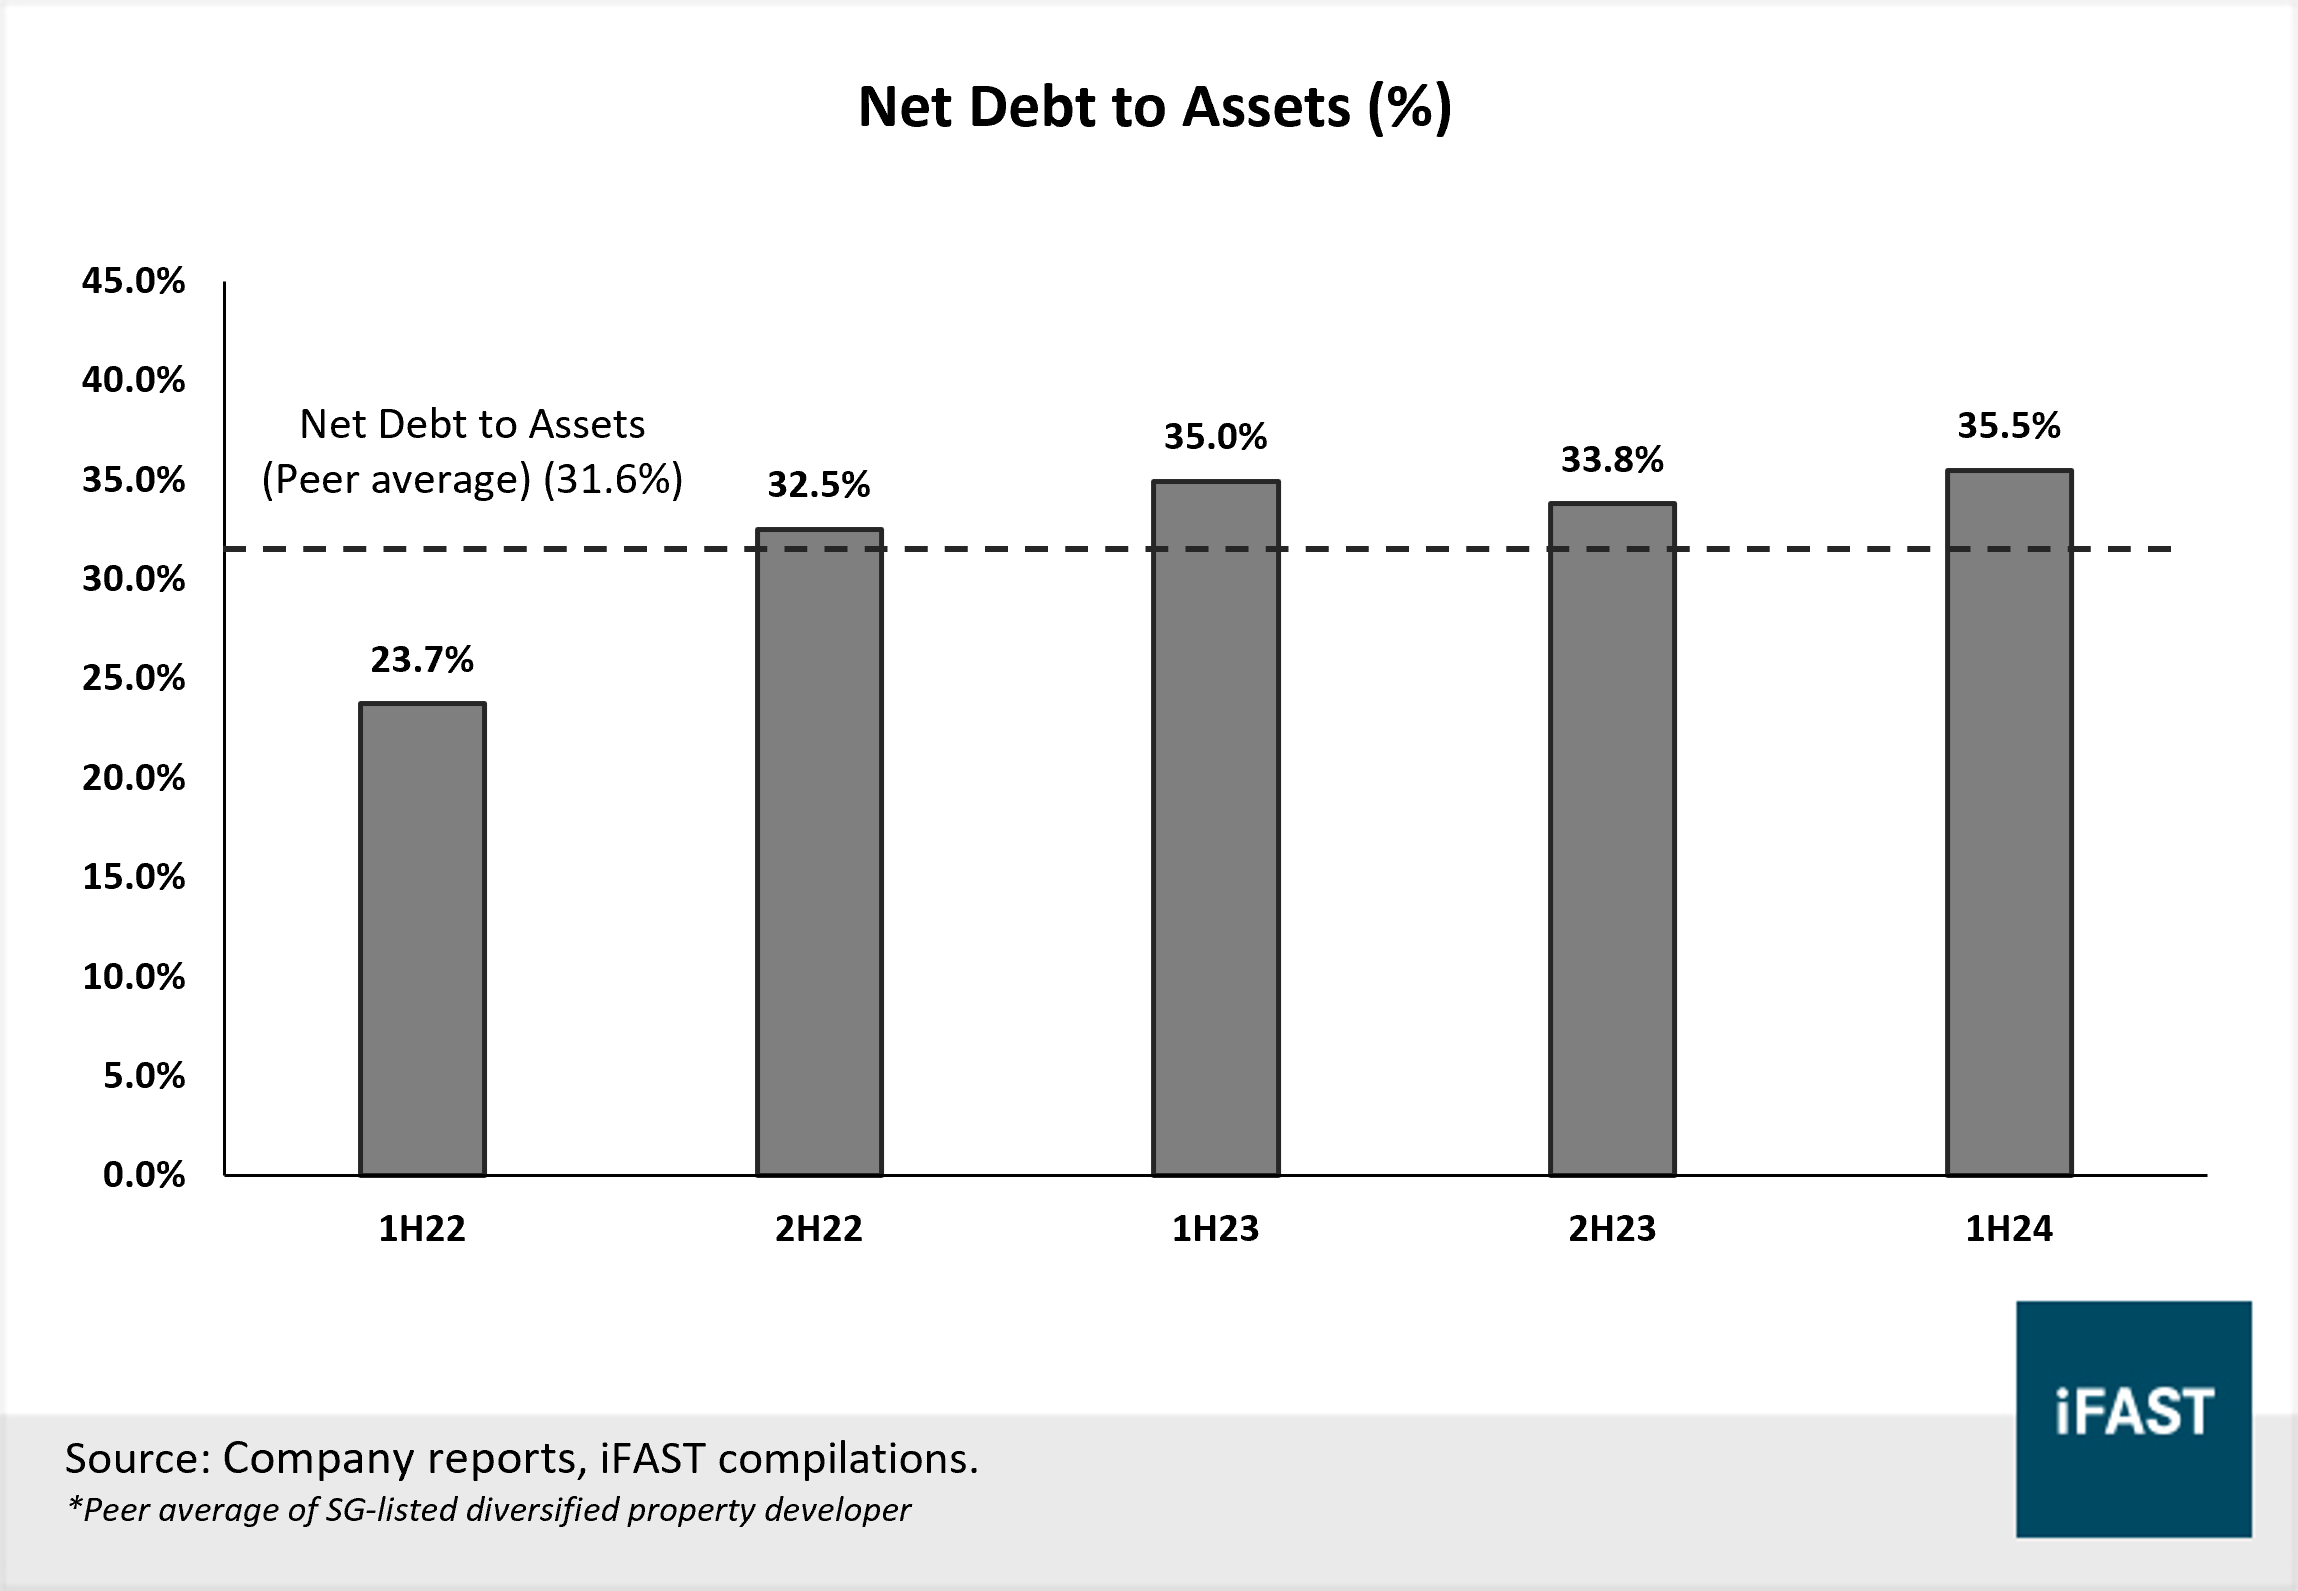
Despite higher borrowings, we think the capital structure for STC remains decent and the Group is not aggressively leveraged. While credit metrics have moderated, they are not far from the peer average and are around levels seen in recent years, suggesting some prudency from management.
The Group’s estimated net debt to total asset ratio held steady at around 35.5% (2H23: 33.8%). While this is higher than the peer (SG-listed diversified real estate developers) average of 31.6%, this ratio has remained relatively steady in recent years. Its net gearing ratio was estimated at 79.9% in 1H24, increasing from 72.8% in 2H23, and slightly below the peer average of 80.9%. STC’s management attributed the rise in gearing to the holding of assets in an elevated interest rate environment.
Chart 3: While net gearing has risen, it remains around the peer average
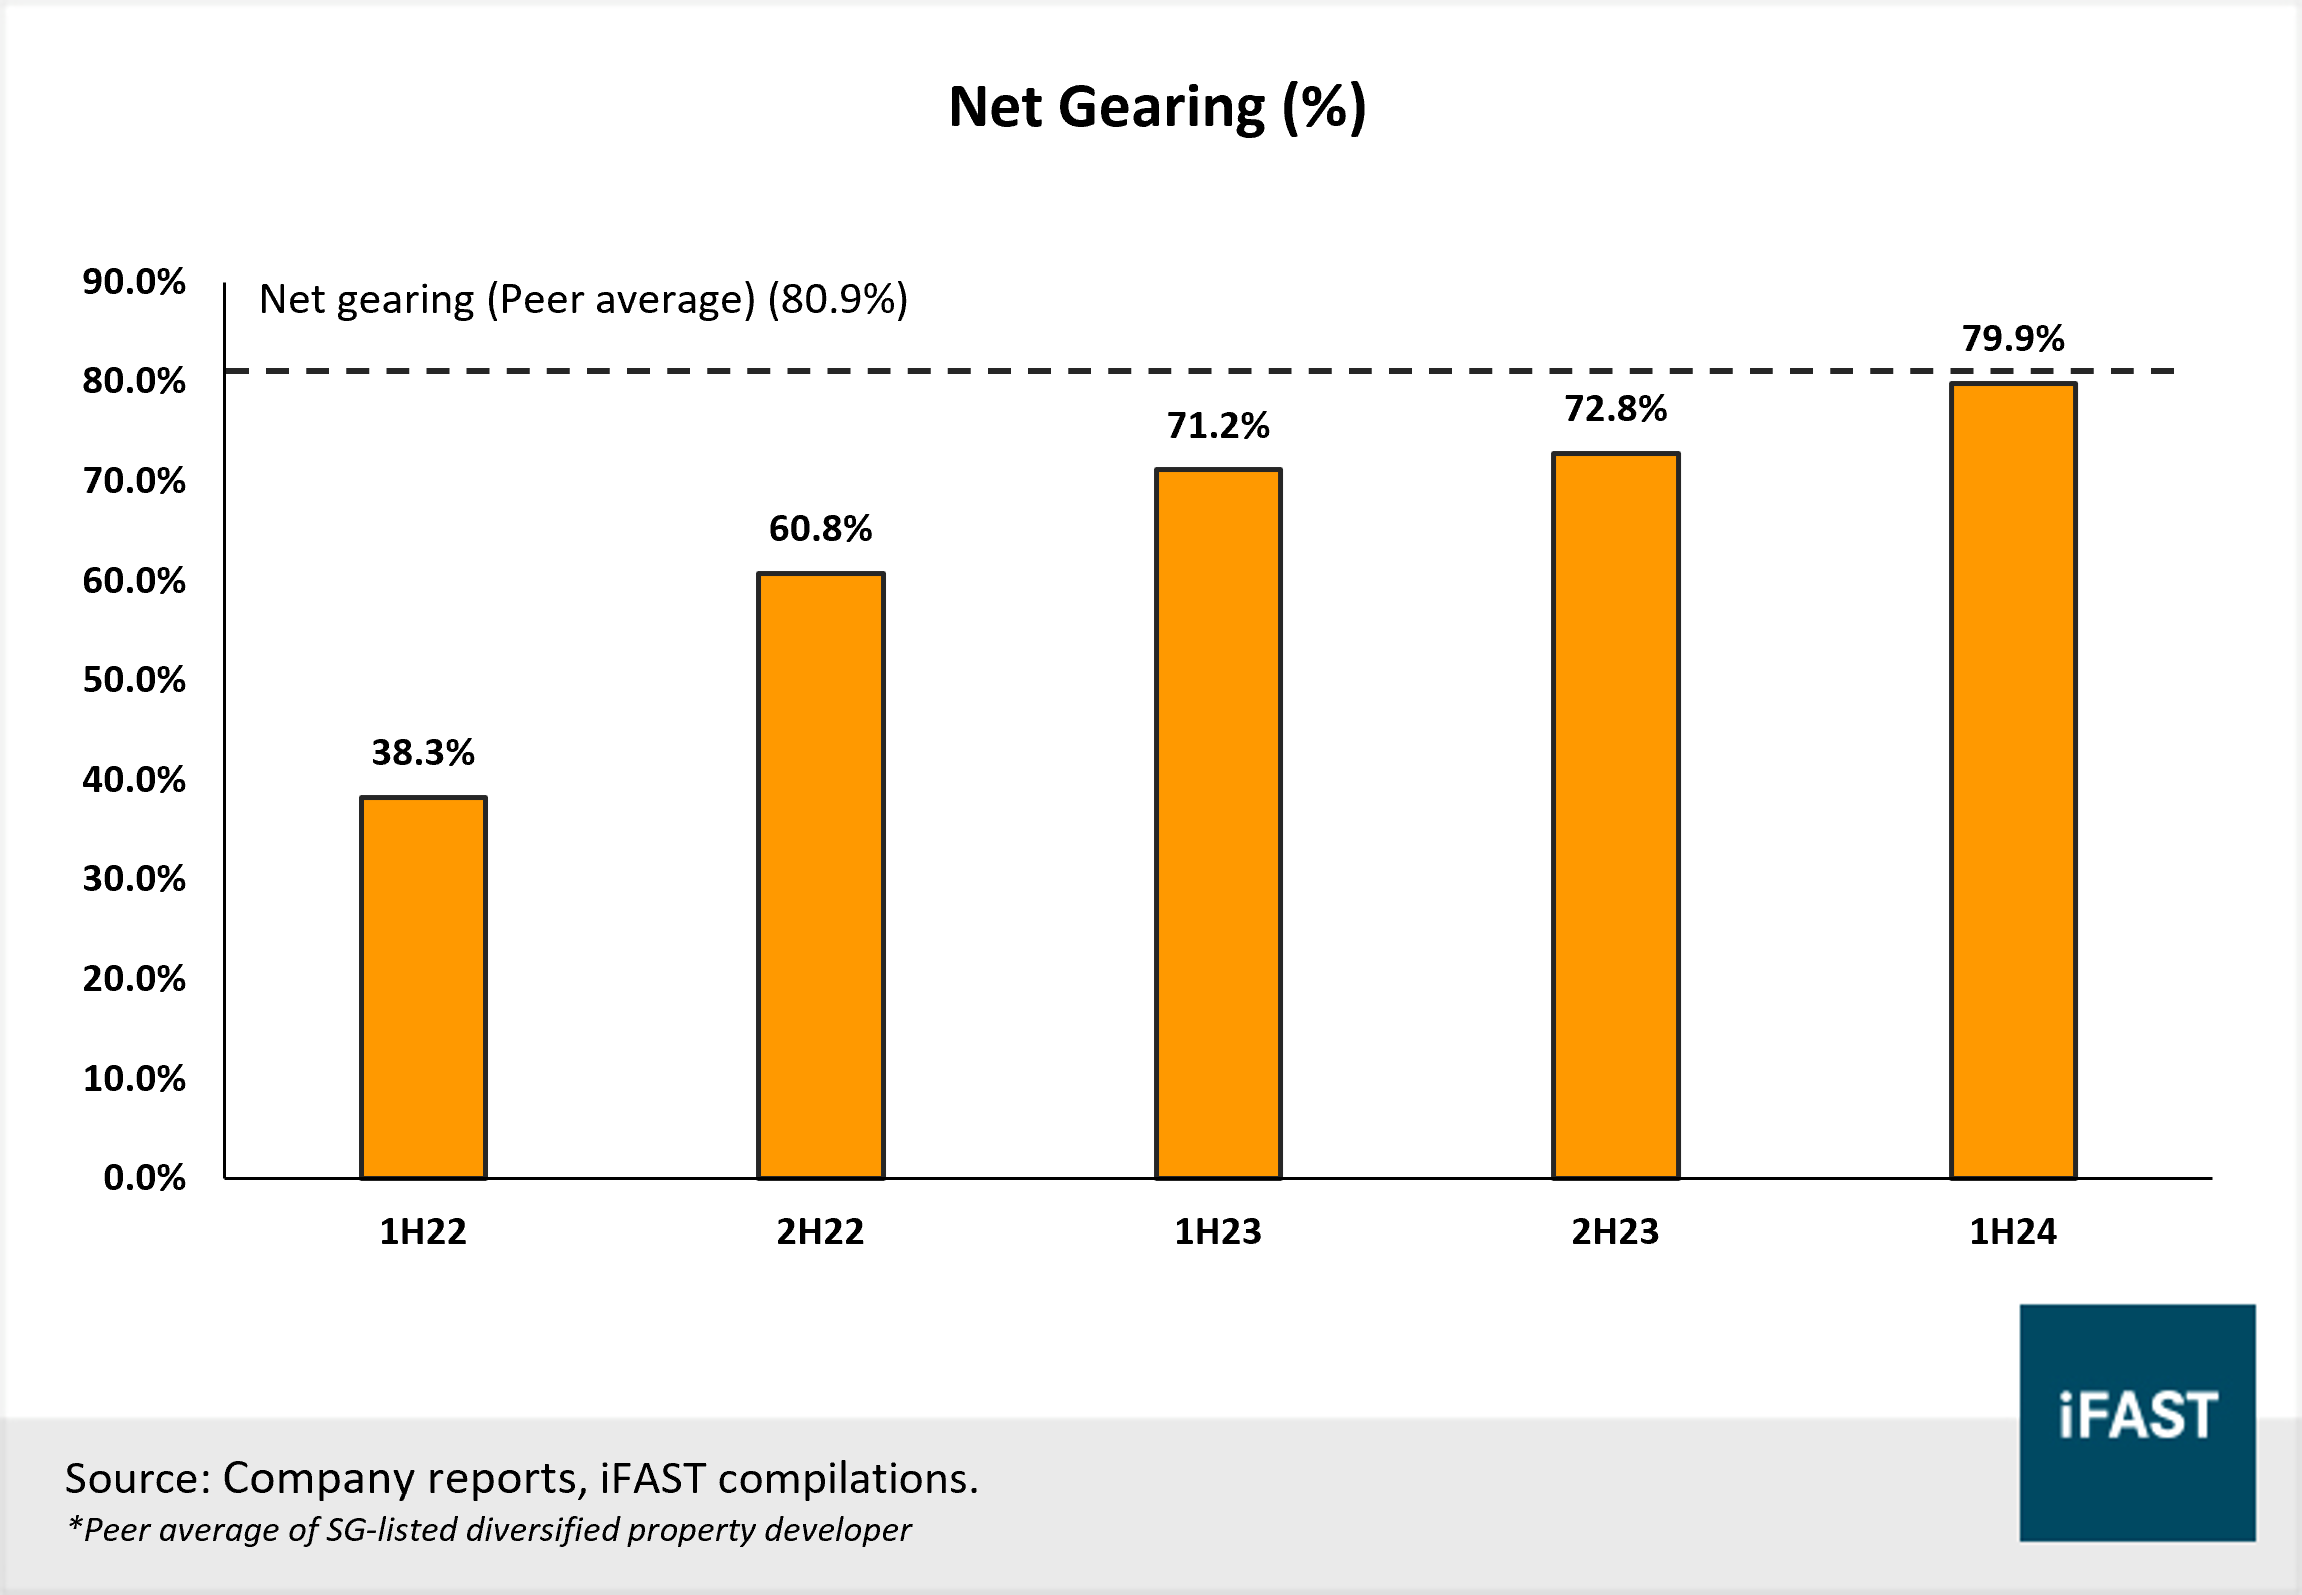
Chart 4: Net debt to asset ratio has ticked up but is not much higher than the peer average
Operating cashflow fell but not a red flag
Operating cashflow before working capital changes for the Group fell slightly by S$29.5M (1H23: S$32.4M) due to lower profits. Operating cashflow for STC can be slightly volatile due to the nature of the Group’s Resources business but we are not concerned for several reasons. First, we expect a gradual recovery in earnings to support cashflow. Second, STC also has other recurring sources of cashflow such as dividends from investment securities and interests to stabilise the group’s overall cashflow. Last, we believe further cash buffer could come from Straits Real Estate’s (“SRE”) asset disposal, as part of its ongoing capital recycling strategy. Over the past decade, SRS has a track record of asset disposal amounting to an estimated S$153M per annum.
Credit metrics have broadly moderated in 1H24
Besides a moderation in STC’s net debt to total asset and net gearing ratios, EBITDA coverage declined to an estimated 1.5x in 1H24, from 1.9x in 1H23. Similarly, the Group’s operating cashflow coverage has also declined to an estimated 0.7x in the same period, from 0.8x in 1H23.
Both ratios fell due to softer profits while finance costs grew due to high benchmark rates and the issuance of fixed-rate notes. We think the deterioration of credit metrics is worth monitoring as it highlights a moderation in STC’s credit profile. That said, we expect many of these metrics to improve as the Group’s profitability gradually improves.
Table 1: Several credit metrics have broadly moderated over the past year
Metrics | 1H23 | 2H23 | 1H24 |
Total Borrowings | S$ 1,602.2M | S$ 1,621.5M | S$ 1,723.1M |
ST borrowings / (% of total borrowings) | S$ 181.3M (11%) | S$ 292.5M (18%) | S$ 225.0M (13%) |
Net debt/ Total Asset | 35.0% | 33.8% | 35.5% |
Net Gearing | 71.2% | 72.8% | 79.9% |
EBITDA/ Finance Cost | 1.9x | 0.02x | 1.5x |
Operating Cashflow/ Finance Cost | 0.8x | 1.2x | 0.7x |
Sources: Bloomberg Finance, iFAST Estimates. Data as of 21 October 2024. | |||
Recommendations
Table 2: Unrated fixed rate issuances from Straits Trading and comparable peers
Bond | Issuer | Price | Remaining Years to Maturity (years) | Ask YTM (%) |
The Straits Trading Company | 99.80 | 1.02 | 4.00 | |
The Straits Trading Company | 99.80 | 1.53 | 4.27 | |
City Developments | 98.90 | 1.42 | 3.11 | |
OUE Treasury | 99.72 | 1.92 | 3.65 | |
Wing Tai Holdings | 101.03 | 2.59 | 3.68 | |
Keppel Land | 97.94 | 1.60 | 3.34 | |
Sources: Bondsupermart, iFAST Compilations. Data as of 21 October 2024. | ||||
We believe the credit profile for STC has moderated as compared to 1H23. That said, the credit profile remains decent in our view, supported by strong liquidity. A gradually improving profitability should also improve credit metrics over time.
Amongst STC’s fixed rate issuances, we prefer the STRTR 4.100% 04May2026 Corp (SGD) and STRTR 3.750% 29Oct2025 Corp (SGD) (Table 2) which screen as attractive short-term SGD options for investors given the higher yields as compared to its peers with similar years to maturity. These two bonds also have one of the highest yields amongst diversified real estate developers (both are also traded on Bond Express).
In general, we see little risk for STC’s 2025 and 2026 notes given the available liquidity of nearly S$ 860M, which should cover the interest payments and S$ 370M principal for both bonds. While we prefer the 2025 and 2026 notes, we think STRTR 4.700% 24Jan2029 Corp (SGD) – trading at an indicative yield-to-maturity of 4.50% - remains a decent option for investors looking for longer-term bonds from a stable issuer.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds positions in STRTR 3.750% 29Oct2025 Corp (SGD), STRTR 4.100% 04May2026 Corp (SGD), and the analyst who produced this report holds a NIL position in the abovementioned securities.