- Bond prices of Trafigura dipped to as low as 93 cents on the dollar as volatile oil prices caused commodity traders to cover their short hedge positions.
- Among its bonds, TRAFIG 5.250% 19Mar2023 Corp (USD) has the shortest time to maturity of 0.92 years with an indicative yield to maturity of 9.92%.
- We remain positive for Trafigura to navigate through this period of volatile commodity prices given Trafigura’s ample liquidity and risk management.
- While we expect Trafigura’s margins to be impacted slightly by the backwardation of oil prices, we also see strong trading volumes from energy and metal markets that may cushion the impact of lower margins.
Commodity prices were sent into frenzy when Russia invaded Ukraine, resulting in oil hitting more than USD 100 per barrel and a short squeeze on Nickle that resulted in Nickle being suspended for over a week on the London Metal Exchange.
Bond prices of Trafigura dipped to as low as 93 cents on the dollar as volatile oil prices caused commodity traders to cover their short hedge positions. Currently, the TRAFIG 5.250% 19Mar2023 Corp (USD) are trading at attractive yields of over 9%. We believe Trafigura Group Pte. Ltd. will be able to navigate through the volatile commodity prices and highlight some recommendations for its bonds.
About Trafigura Group Pte. Ltd.
Trafigura Group Pte. Ltd. was established in 1993 and is one of the largest physical commodities trading and logistics groups in the world. Their main business segments are Energy and, Metals and Minerals segments. The Energy segment is engaged in oil and petroleum products which include sourcing, provision and storage of oil. The Metals and Minerals segment trades copper, lead, zinc, aluminium, iron ore and coal in all forms. In FY21, the Energy segment contributed to 61% of the group’s revenue while Metals and Minerals contributed to 39% of the group’s revenue. Being a large commodities trader, Trafigura’s operations span across the globe with majority of its revenues generated in Asia, Australia and Europe.
FY21 financial highlights
Trafigura reported USD 231.3b of revenue for the full year financial results ending 30 September 2021. Revenues increased by 57% due to higher commodity prices and increased trading volume. Trading volumes in 2021 were the highest ever recorded as Trafigura traded an average of 7m barrels of oil and petroleum products a day. Non-ferrous metals volume increased by 9% to 22.8m metric tonnes and bulk minerals by 8% to 82.7m metric tonnes. As a result, net profit reached a record high of USD 3.07b and EBITDA came in at USD 4.62b in FY21.
Backwardation to hurt margins in 2022
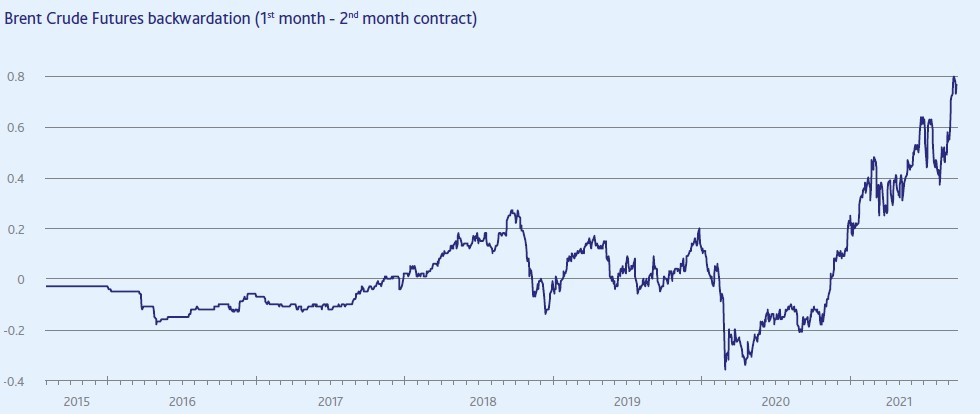
Due to supply constraints from OPEC+ as well as the Russia and Ukraine crisis, the Brent Crude futures price curve have reached historically strong backwardation (Figure 1). Backwardation occurs when spot prices are higher than future prices. This hurts commodity traders as it removes the ability for commodity traders to engage in “cash and carry arbitrage”. Cash and carry arbitrage is a strategy that involves buying a particular commodity for a low price and holding it until the expiration date of the futures contract, at which point it would be delivered against the futures contract at a higher price.
While we expect Trafigura’s margins to be impacted slightly by the backwardation of oil prices, we also see strong trading volumes from energy and metal markets that may cushion the impact of lower margins. In the non-ferrous metals space, copper and nickel are important materials for electrification and for climate goals to reach net-zero emissions. The growing demand for these metals is expected to continue to grow and bolster Trafigura’s trading volumes in these segments.
Figure 1: Brent Crude Futures backwardation
Increased need for liquidity from volatile commodity prices
As a commodities trader, Trafigura requires a large amount of liquidity and financing in order to maintain their operations. Trafigura finances its day-to-day trading activity through uncommitted trade finance facilities while corporate credit facilities are used to finance short-term liquidity requirements such as margin calls or bridge financing. As commodities prices surge, this may increase working capital needs for credit lines as traders have to cover their short positions from the hedging of commodities and also higher cost for trading. Trafigura managed to secure an additional USD 6b of bank financing in FY21, bringing total credit lines to USD 66b.
Due to volatility and higher commodity prices from the Ukraine crisis, commodity traders including Trafigura have faced margin calls to cover their hedge positions. Trafigura managed to raise 3 credit facilities amounting to ~USD 8.39b in Mar 2022. We remain positive for Trafigura to navigate through this period of volatile commodity prices given Trafigura’s ample liquidity and risk management. In terms of market risk exposure, the Value at Risk (“Var”) for Trafigura was USD 47.9m (0.45% of equity) for FY21, which was less than 1% of total group equity.
Liquidity and credit profile
At FY21, Trafigura had a total debt of USD 45.2b of which USD 34.3b are short term loans and borrowings. However, in order to analyse Trafigura’s credit metrics, gross debt has to adjust for inventories and receivables securitisation debt as well as other adjustments. Receivables securitisation debt of USD 5.15b had to be excluded as they are distinct legal entities from Trafigura and were only consolidated due to the Group’s accounting rules. Inventories are usually deducted as all of Trafigura’s stock are either hedged or pre-sold. Inventories are also liquid and can be converted to cash.
Table 1: Adjustments for gross debt
|
In USD m |
FY21 |
FY20 |
|
Non-current loans and borrowings |
10,911.2 |
7,070.1 |
|
Current loans and borrowings |
34,269.8 |
25,783.5 |
|
Total debt |
45,181.0 |
32,853.6 |
|
Less: Cash and cash equivalents |
10,667.5 |
5,757.0 |
|
Deposits |
460.0 |
466.0 |
|
Inventories |
30,508.8 |
20,921.8 |
|
Receivables securitisation debt |
5,150.6 |
2,750.6 |
|
Non-recourse debt |
555.4 |
198.4 |
|
Adjusted net debt |
(2,171.3) |
2,759.8 |
|
Equity |
10,559.9 |
7,789.9 |
|
Adjusted net debt to equity (x) |
(0.21)x |
0.35x |
|
Source: Company annual report. |
||
After adjustments, Trafigura had a negative adjusted net debt position of USD 2.17b. Adjusted net debt to equity was negative 0.21x, an improvement from 0.35x in FY20. Liquidity for Trafigura remained relatively stable, its current ratio was 1.13x in FY21 compared to 1.17x in FY20 while interest coverage ratio improved to 6.24x (FY20: 5.15x) due to stronger earnings in FY21.
Recommendation
The bonds issued by TRAFIG traded lower due to concerns regarding higher volatility of commodity prices resulting in more margin calls to Trafigura. However, as mentioned previously, Trafigura managed to secure several credit lines to finance the increased cost of working capital. Additionally, Trafigura showed strong cash generating ability as operating cash flow before working capital changes was USD 6.86b in FY21. Net cash from financing activities was USD 7.88b reflecting strong access to self-liquidating short-term finance lines to match the increased working capital needs. As a result, cash and cash equivalents increased by more than 80% to USD 10.6b in FY21 (FY20: USD 5.7b).
Table 2: TRAFIG bonds
|
Bond name |
Issuer |
Currency |
Maturity / next call |
Years to maturity / next call |
Ask price |
Yield to maturity / next call (%) |
|
TRAFIG 5.250% 19Mar2023 Corp (USD) |
Trafigura Funding SA |
USD |
19 Mar 23 |
0.93 |
96.04 |
9.92 |
|
TRAFIG 7.500% Perpetual Corp (EUR) |
Trafigura Group Pte Ltd |
EUR |
31 Jul 24 |
2.30 |
99.73 |
7.62 |
|
TRAFIG 5.875% 23Sep2025 Corp (USD) |
Trafigura Funding SA |
USD |
23 Sep 25 |
3.44 |
93.51 |
8.10 |
|
TRAFIG 3.875% 02Feb2026 Corp (EUR) |
Trafigura Funding SA |
EUR |
2 Feb 26 |
3.81 |
93.06 |
5.97 |
|
Source: Bloomberg Finance L.P., iFAST compilations. Data as of 14 April 2022. |
||||||
Among its bonds, TRAFIG 5.250% 19Mar2023 Corp (USD) has the shortest time to maturity with the highest yields. It matures on 19 Mar 23 and has an indicative yield to maturity of 9.92%. The holding period return if held to maturity for 11 months would be ~9.59%. The redemption of TRAFIG 6.875% Perpetual Corp (USD) on its call date on 21 Mar 2022 provides added confidence that TRAFIG has strong capital management to redeem its bonds even during periods of volatile commodity prices.
Business related risks
Sudden price changes to commodities may result in more margin calls to Trafigura. The Russia and Ukraine war restricted the supply of commodities from both countries, resulting in a sudden price surge in energy prices. As Trafigura will take short positions to hedge against price fluctuations, a sudden surge in prices may lead to margin calls which could lead to large losses incurred by the company. An escalation in the war may lead to another spike in commodity prices which would be negative to the company. In order to meet liquidity risks resulting from extreme volatility, the company keeps available cash on hand of more than USD 500m (higher in cases of extreme volatility).
Conclusion
2021 was a record year for Trafigura as the company reported stellar results for its net profit and volumes traded. Concerns over volatile commodity prices lead to bonds issued by TRAFIG to fall. However, we remain positive on Trafigura’s cash generating ability and access to credit lines to fund higher cost of working capital. We recommend the TRAFIG 5.250% 19Mar2023 Corp (USD) at an indicative yield to maturity of 9.92% with about 11 months to maturity.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a NIL position and the analyst who produced this report hold a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!