- AAREIT experienced strong growth in its revenues and net property income
- Supply for industrial spaces remain tight which led to higher rental growth
- 80.4% of AAREIT’s gross rental income is made up of defensive and resilient industries
- Refinancing risk for the REIT is low as there are no short-term debt obligations due until FY23/24
- AAREIT 3.600% 12Nov2024 Corp (SGD) is attractive with an indicative YTM of 4.97% with 1.9 years to maturity
AIMS APAC REIT (“AAREIT”) is an industrial REIT with properties in Singapore and Australia. As of 15 November 2021, AAREIT has 29 properties in its portfolio, 26 in Singapore and 3 in Australia. AIMS Financial Group (“AIMS”) is the sole sponsor of AA REIT and is a diversified financial service and investment group headquartered in Sydney, Australia.
The sponsor, AIMS has vast experience in funds management and property investment, previously turning around distressed MacarthurCook during the Global Financial Crisis (“GFC”) in 2009. AIMS successfully turned around the MacarthurCook Industrial REIT (now known as AIMS APAC REIT) when it was in distress during the GFC as the REIT entered into an acquisition without first securing finance. AIMS grew the REIT from a market capitalisation of SGD 60.2m in 2009 to SGD 1,030m in 2021.
1H22/23 Financial Highlights
For its first half financial results ending 30 September 2022 (“1H22/23”), gross revenue increased by 27.5% to SGD 83.2m while net property income grew 28.2% to SGD 61.1m. The increase in property income was due to contributions from their new acquisition of Woolworths HQ (completed in Nov 2021) and higher rental income and recoveries from its Singapore properties.
For 1H22/23, AAREIT executed 21 new leases and renewed 26 leases and kept a high tenant retention rate of 85.4%. Rental reversion also saw strong growth of 8.1%, with logistics & warehouse tenants saw the highest increase of 14.1%. Singapore continues to see strong demand from logistics & warehouse tenants while supply for industrial spaces remains tight. The food industry, third-party logistics and electronics sector continues to drive demand for these spaces, leading to higher rental growth.
Resilient tenant base
Being an industrial REIT, AAREIT’s tenants are in resilient and defensive industries like supermarkets and telecommunications. As we head into 2023, we expect a global economic slowdown as companies grapple with higher inflation and interest rates. Defensive industries like supermarkets are able to withstand the slowdown due to their demand being relatively inelastic as their goods are essential to our daily lives. This provides more resilient and predictable cash flows for tenants within this industry. As of 1H22/23, 80.4% of AAREIT’s gross rental income is made up of defensive and resilient industries. This allows for AAREIT to generate resilient rental income from its tenants even during a recession or an economic slowdown.
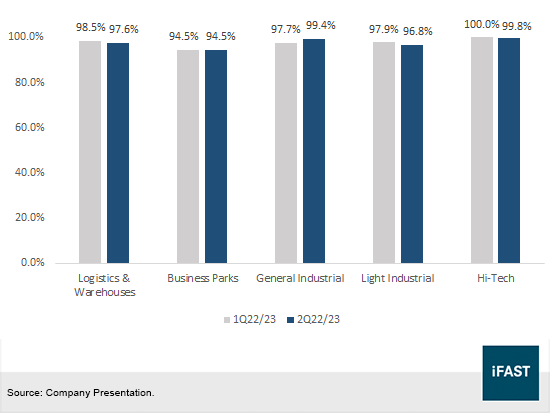
Occupancy rate for AAREIT also remained relatively stable with an overall portfolio occupancy rate of 97.5%. This is driven by high demand for its industrial spaces. AAREIT has a portfolio weighted average lease expiry (“WALE”) of 4.8 years. 7.4% of its portfolio is set to expire in FY22/23 with a large majority being its logistics & warehouse tenants. As supply for these spaces remains tight, AAREIT is able to capture higher rental growth from the renewal of these leases.
Chart 1: 80.4% of rental income contributed by defensive industries
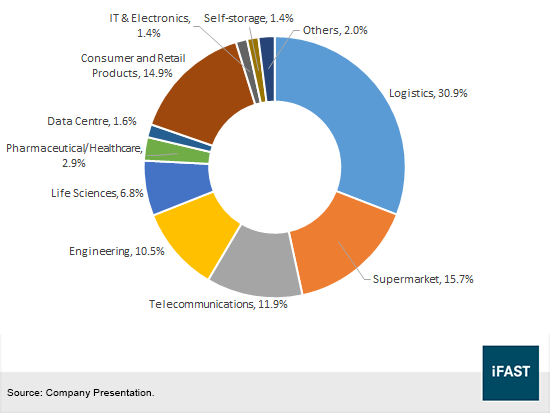
Chart 2: Overall occupancy rate remains stable at 97.5%
Credit Profile
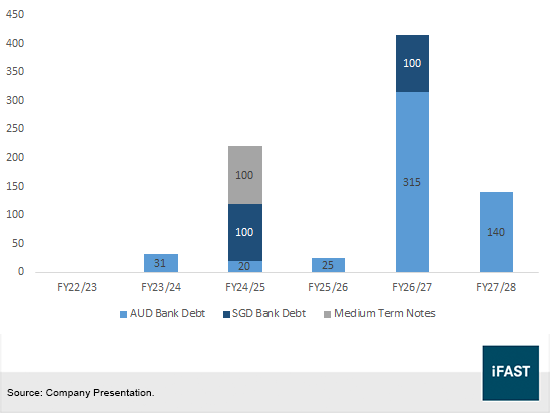
As of 1H22/23, AAREIT had SGD 15.7m of cash and cash equivalents while total borrowings amounted to SGD 807.5m. Additionally, the REIT has undrawn committed facilities of SGD 205.3m to tap on. AAREIT has refinanced all of its maturing debt and has no debt obligations until FY24/25, of which only makes up 3.7% of total debt. AAREIT has a prudent credit profile as gearing for AAREIT was 36.5% while interest coverage ratio (“ICR”) was 4.6x (when adjusted for perpetual notes, ICR = 2.5x).
Rising interest rates will have a negative impact to a REIT’s DPU due to higher interest on its interest bearing loans. AAREIT estimated that for every 25 basis points increase in interest rate, it will translate to approximately 0.08 cents impact on DPU. Currently, 23% of AAREIT’s borrowings are hedged while 65% of its borrowings are fixed rate basis. Approximately 88% of its borrowings are protected from rising interest rates and should be able to mitigate the costs of rising interest rates.
Overall, we find AAREIT’s credit profile to be decent and protected from rising interest rates. Refinancing risk for the REIT is low as there are no short-term debt obligations due until FY23/24. Gearing for the REIT remains well below MAS’ regulatory requirements with interest coverage adequate at 4.6x.
Chart 3: No debt maturing in FY23/24
Recommendation
Among the bonds offered by AAREIT, we think the AAREIT 3.600% 12Nov2024 Corp (SGD) is attractive. It has an indicative yield to maturity (“YTM”) of 4.97% with 1.9 years to maturity. Comparing to other industrial REITs such as Mapletree Industrial Trust (“MINTSP”), we find the AAREIT 3.6% 2024s to be more attractive.
From Table 2, we compared various metrics between AAREIT and MINTSP. We think both REITs offer similar credit profiles with comparable gearing and occupancy rates. We prefer AAREIT over MINTSP due to its debt maturity profile. Currently, AAREIT do not have any refinancing obligations until FY23/24 which helps to mitigate any refinancing risk in an environment of higher interest rates. Additionally, the AAREIT 3.600% 12Nov2024 Corp (SGD) provides some yield pick up over MINTSP 3.160% 28Mar2024 Corp (SGD) with its YTM of 4.97% with a slightly longer time to maturity.
Table 1: Recommendation
|
Bond |
Issuer |
Bond Price |
Maturity Date |
Years to Maturity |
Yield to Maturity (%) |
|
AAREIT 3.600% 12Nov2024 Corp (SGD) |
AIMS APAC REIT |
97.57 |
12 Nov 2024 |
1.88 |
4.97 |
|
MINTSP 3.160% 28Mar2024 Corp (SGD) |
Mapletree Industrial Trust Treasury Co Pte Ltd |
98.81 |
28 Mar 2024 |
1.25 |
4.15 |
|
Source: Bloomberg Finance L.P., iFAST compilations. Data as of 28 Dec 2022. |
|||||
Table 2: Ratios between AAREIT and MINTSP
|
As of 30 Sep 22 |
AAREIT |
MINTSP |
|
Gearing (%) |
36.5 |
37.8 |
|
Interest Coverage Ratio (x) |
4.6 |
5.8 |
|
% of Fixed Debt of total debt |
88 |
74.2 |
|
WALE |
4.8 years |
6 years |
|
Weighted Average Debt Expiry |
3.5 years |
3.5 years |
|
Occupancy rate (%) |
97.5 |
95.6 |
|
Source: Bloomberg Finance L.P., iFAST compilations. Data as of 28 Dec 2022. |
||
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in AAREIT 5.375% Perpetual Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!