- The partial divestment of OUE Bayfront helped to improve its financial flexibility and reduce its borrowings while retaining its exposure in the premium commercial asset. Occupancy rates at its retail and office properties remain strong in FY21.
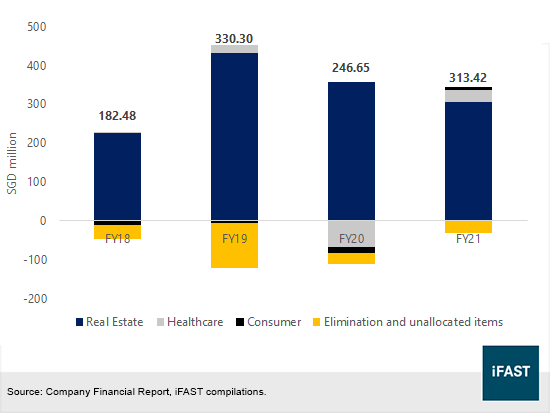
- FY21 PBIT improved notably by 27.1% underpinned by its resilient Healthcare and Consumer segments, while its Hospitality segment is expected to improve further following the rebranding of Mandarin Orchard Singapore and travel recovery.
- OUE’s credit profile is well-supported by its healthy liquidity and leverage ratio, and the Group’s portfolio also provides sufficient unencumbered asset coverage against its debt.
- The OUESP 3.500% 2026 Corp (SGD) offers a yield to maturity of ~3.88% with 4.3 years left to maturity, which provides investors with higher yields compared to most of its peers.
- For more information, investors may refer to the bond factsheet here.
OUE Limited (“OUE”) is a leading real estate development, investment and management company in Singapore, with diversified assets across different sectors such as commercial, healthcare, hospitality, retail and residential. It is also the manager of OUE Commercial REIT (“OUE C-REIT”) and First REIT with a combined funds under management of SGD 7.8b as of 31 December 2021.
Table 1: OUE Limited Investment Properties as of 31 December 2021
|
Investment Property |
Type |
Country |
Tenure |
Valuation |
|
OUE Bayfront |
Office, Retail |
Singapore |
Leasehold |
SGD 1,270m |
|
OUE Downtown |
Office, Retail |
Singapore |
Leasehold |
SGD 1,118m |
|
One Raffles Place |
Office, Retail |
Singapore |
Leasehold |
SGD 1,868m |
|
Mandarin Gallery |
Retail |
Singapore |
Leasehold |
SGD 454m |
|
Lippo Plaza |
Office, Retail |
China |
Leasehold |
SGD 575m |
|
OUE Twin Peaks |
Residential |
Singapore |
Leasehold |
SGD 93m |
|
Hikari Heights Varus Kotoni |
Nursing Home |
Japan |
Freehold |
SGD 75m |
|
Hikari Heights Varus Makomanai-Koen |
Nursing Home |
Japan |
Freehold |
SGD 54m |
|
Elysion Mamigaoka & Elysion Mamigaoka Annex |
Nursing Home |
Japan |
Freehold |
SGD 29m |
|
Varus Cuore Sapporo-Kita/Varus Cuore Sapporo-Kita Annex |
Nursing Home |
Japan |
Freehold |
SGD 34m |
|
Hikari Heights Varus Fujino |
Nursing Home |
Japan |
Freehold |
SGD 19m |
|
Elysion Gakuenmae |
Nursing Home |
Japan |
Freehold |
SGD 19m |
|
Orchard Kaichi North |
Nursing Home |
Japan |
Freehold |
SGD 16m |
|
Varus Cuore Yamanote |
Nursing Home |
Japan |
Freehold |
SGD 12m |
|
Orchard Amanohashidate |
Nursing Home |
Japan |
Freehold |
SGD 11m |
|
Hikari Heights Varus Ishiyama |
Nursing Home |
Japan |
Freehold |
SGD 10m |
|
Hikari Heights Varus Tsukisamu-Koen |
Nursing Home |
Japan |
Freehold |
SGD 8m |
|
Orchard Kaichi West |
Nursing Home |
Japan |
Freehold |
SGD 5m |
|
5 Indonesia shophouses |
Commercial |
Indonesia |
Freehold |
SGD 4m |
|
Source: Company Financial Reports, iFAST compilations |
||||
The Group mainly operates through 3 segments: 1) Real Estate 2) Healthcare and 3) Consumer. Its Real Estate segment comprises of investment properties, hospitality and development properties. For the year ended 31 December 2021, its Real Estate segment contributed to ~85% of total revenues, mainly driven by its investment properties (65%) and hospitality (19%) segments. Notably, most of its major investment properties such as OUE Bayfront, OUE Downtown and One Raffles Place continued to achieve high committed occupancy rates for the past year.
Besides real estate, OUE has also ventured into the healthcare and consumer sectors back in 2017. The Group is the controlling shareholder with 70.4% interest in OUE Lippo Healthcare Limited, which is a pan-Asian healthcare group that invests and operates in healthcare businesses and has a market cap of ~SGD 144m as of 1 June 2022. OUELH is also the sponsor and unitholder of First REIT, where it owns 40% in the manager, First REIT Management Limited. The remaining 60% is owned by OUE Limited.
Meanwhile, its Consumer segment consists of OUE Restaurants such as Chatterbox, VUE Bar and Grill, and Shisen Hanten located at Hilton Singapore Orchard and OUE Bayfront. Besides that, the Group owns 32% stake in PT Matahari Department Store Tbk through its joint venture, which is the largest omni-channel retailer in Indonesia, as well as 17.2% equity stake in PT Multipolar Tbk, which is a consumer and technology investment company that has a wide portfolio of businesses including retail and consumer services. As of 31 December 2021, its Healthcare and Consumer segments contributed to 10% and 5% of FY21 revenues respectively.
Financial Highlights
For the full year ended 31 December 2021 (“FY21”), total revenue decreased by 43.3% year-on-year to SGD 300.8m, mainly due to lower contributions from its Real Estate segment as a result of the partial disposal of OUE Bayfront and divestment of the US Bank Tower. Its Hospitality segment posted a 32.7% decline in revenue to SGD 57.6m because of lower contributions from Mandarin Orchard Singapore following major asset enhancement works made to rebrand the hotel.
On the other hand, its Healthcare and Consumer segment helped to cushion the decline in revenues for FY21. OUE’s Healthcare segment recorded a slight increase in revenue from SGD 29.4m in 2020 to SGD 31.2m in 2021, while its Consumer segment saw a notable improvement of 40.5% in revenue from a year ago as new dining concepts were launched in the previous year to attract more customers.
Figure 1: Breakdown of total profit before interest and taxes
Business Outlook
Rebranded Hospitality segment well-positioned to capitalize on travel recovery
Back in 2020, OUE Limited decided to rebrand Mandarin Orchard Singapore to Hilton Singapore Orchard during the weak hospitality operating environment by implementing major asset enhancement works and refurbishment. Towards the end of February 2022, Hilton Singapore Orchard debuted as Hilton’s flagship hotel in Singapore, and it is the largest Hilton hotel within the APAC region.
The rebranding and reopening of the hotel came at a timely moment, where most countries have started to ease travel restrictions and visitor arrivals in Singapore have improved significantly since the start of this year following the implementation of Vaccinated Travel Lanes. The addition of new income-generating spaces and facilities, coupled with Hilton’s strong brand recognition and distribution network, will help OUE Limited to capture the recovery of Singapore’s hospitality sector and drive future growth going forward.
Asset divestments at attractive valuations help to unlock capital for future acquisitions
OUE C-REIT divested 50% of OUE Bayfront back in March 2021 for a total consideration of SGD 1.27b. The agreed value represented a 26.1% premium over its purchase consideration back in 2014, which was a good opportunity for the Group to realize the value appreciation, improve its capital structure and shore up its liquidity position. The net divestment proceeds of SGD 262.6m provided greater financial flexibility for the Group as it managed to reduce its outstanding borrowings and convertible perpetual preferred units.
Notably, despite selling 50% interest in OUE Bayfront, the manager still retains full operational control over the property, and it continues to provide the Group with significant exposure to the Singapore office market. The divestment also offers the Group with more opportunities to redeploy its capital and invest in more accretive properties in the future to unlock value. On top of that, its investment properties have maintained a high committed occupancy of at least 86% across all of its major office and retail properties in Singapore and China, with only 13.3% of office and 3.4% of retail leases by gross rental income are due for renewal this year. As such, we believe that its Real Estate segment will remain resilient with strong earnings stability underpinned by its high-quality Grade A commercial assets.
Credit Discussion
|
Company |
Current Ratio |
Net Gearing |
LTM EBITDA Coverage |
Total Debt/Total Asset |
Net Debt/LTM EBITDA |
|
OUE Ltd |
1.21 |
0.40 |
3.60 |
31.28% |
6.24 |
|
Straits Trading Company |
0.93 |
0.47 |
12.49 |
32.81% |
2.26 |
|
City Developments Limited |
1.49 |
0.99 |
2.90 |
47.81% |
17.49 |
|
Guocoland |
4.55 |
0.91 |
2.70 |
48.41% |
18.11 |
|
Wing Tai Holdings |
4.92 |
-0.04 |
3.22 |
13.27% |
-1.60 |
|
Source: Company Financial Reports, iFAST estimates |
|||||
Following the divestment of OUE Bayfront and US Bank Tower, the Group managed to pare down its borrowings from SGD 3.5b to SGD 2.8b, and consequently lower its interest expenses from SGD 122.9m in FY20 to SGD 97.4m in FY21. As a result, net gearing ratio improved from 0.52x in FY20 to 0.40x in FY21. We also note that both OUE C-REIT and First REIT were actively deleveraging in the past year so as to pursue future growth strategies within the commercial and healthcare sectors. Aggregate leverage of OUE C-REIT fell by 2.5 percentage points YoY to 38.7% in FY21, while the gearing ratio of First REIT improved from 49.0% in FY20 to 33.6% as at the end of last year.
Notably, ~57% of its borrowings are secured against its assets such as investment properties, bank deposits and property, plant and equipment. Excluding ~SGD 3.66b of pledged assets, we estimate OUE’s total unencumbered assets to be approximately SGD 5.37b, which brings its unencumbered asset coverage ratio (unencumbered assets/unsecured net debt) to be ~7.60x. As such, we think that its asset portfolio provides ample coverage against its debt in the event if the Group is unable to meet its borrowings. Nonetheless, looking at its healthy net gearing ratio of 0.40x and EBITDA coverage of 3.6x, we think that there is no need for the Group to monetise its unpledged assets to pay off its debt obligations and finance expenses in the near future.
In terms of its liquidity, cash and cash equivalents as of 31 December 2021 stood at SGD 518.9m, of which SGD 31.0m relates to pledged deposits against its credit facilities. Nonetheless, its unrestricted cash and cash equivalents of SGD 487.9m are more than sufficient to cover its short-term borrowings of SGD 418.8m. During the year, the Group also issued SGD 200m 3.5% notes due in 2026 so as to repay its SGD 200m 3.75% bond that matured in April 2022. As such, OUE Limited has been actively refinancing its short-term debt obligations to ensure that its liquidity position remains healthy.
Relative Valuation
Table 3: Relative valuation of comparable bonds
|
Bond |
Issue Date |
Maturity Date |
Remaining Years to Maturity |
Ask YTM |
|
CITSP 2.300% 23Mar2026 Corp (SGD) |
23Mar2021 |
23Mar2026 |
3.81 |
3.35% |
|
STRTR 4.100% 04May2026 Corp (SGD) |
04May2022 |
04May2026 |
3.92 |
3.73% |
|
CITSP 3.480% 15Jun2026 Corp (SGD) |
15Jun2016 |
15Jun2026 |
4.04 |
3.50% |
|
OUESP 3.500% 21Sep2026 Corp (SGD) |
21Sep2021 |
21Sep2026 |
4.30 |
3.88% |
|
GUOLSP 3.200% 26Oct2026 Corp (SGD) |
26Oct2021 |
26Oct2026 |
4.40 |
3.43% |
|
Source: Bloomberg Finance L.P., iFAST compilations. Figures as at 2 June 2022 |
||||
Previously, we have written an article on Straits Trading Company (“STC”), recommending the STRTR 4.100% 04May2026 Corp (SGD). Since then, the yield to maturity of STC’s 2026 bond has fallen ~18 basis points (“bps”) due to higher buying interest, and it is currently trading at an ask price of ~101.35 with a YTM of 3.73%. As such, we think that the OUESP 3.500% 21Sep2026 Corp (SGD) offers an attractive alternative to STC with comparable credit metrics (Table 2), given that STC’s 2026 bond yield has fallen below OUE’s 2026 bond. Investors who might have missed out on the opportunity to invest in STC’s 2026 bond previously may now consider the OUESP 3.500% 21Sep2026 Corp (SGD) as an alternative.
Referring to Table 3, we see that the OUESP 3.500% 21Sep2026 Corp (SGD) offers the highest yield at 3.88% compared to other comparable bonds with similar years to maturity. Notably, OUE’s yield curve is the highest relative to other comparable property developers like City Developments Limited and Guocoland Ltd, as its bonds are trading at wider credit spreads across the curve. Therefore, we think that the OUE 2026 bond offers a good risk-return trade-off, given that investors can earn a decent yield pickup over its peers despite having a lower leverage and stronger interest servicing ability than some of them as seen from Table 2.
Conclusion
In conclusion, we think that OUE’s diversified asset portfolio across different sectors such as commercial, retail, hospitality, healthcare and consumer segments will help to drive long-term sustainable growth and preserve earnings stability through the high office and retail occupancy rates. Its Hospitality segment will likely improve following the rebranding of Mandarin Orchard Singapore and travel recovery, and the Group still remains proactive in seizing new opportunities through capital recycling. Its credit profile is well supported by a stable liquidity and leverage position, while its asset portfolio also provides sufficient coverage against its debt obligations. We think that the OUESP 3.500% 21Sep2026 Corp (SGD) offers an attractive return of ~3.88% for investors who are looking for a well-diversified property developer.
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds positions in OUECT 3.950% 02Jun2026 Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!