Keppel Corporation Limited (“Keppel”) announced on 7 September 2021 that the company is launching NC3 perpetual notes at an initial price guidance (“IPG”) of 3%. The notes will be direct, unsecured and subordinated.
About the Perpetual Notes
The perpetual notes will be unsecured and subordinated and will be non-callable for 3 years at an IPG of 3%. The notes will be first callable on September 2024 and on each distribution payment date thereafter. The first reset date will be on September 2026 and if not redeemed the notes will reset on September 2026 and every 5 years thereafter to the sum of the 5-year Singapore Overnight Rate Average-Overnight Indexed Swaps (SORA-OIS) plus initial credit spread plus the step-up margin. From year 5, the note bears a coupon step up of 100 basis points (“bps”).
The perpetual notes bear an issuer call which the issuer may redeem the notes early in the case of a Relevant Event. Relevant Event includes when (i) Keppel ceases to be listed or admitted to trade on the SGX-ST; (ii) when there is a suspension or material limitation in the trading of the Shares of Keppel on the SGX-ST and such suspension or material limitation occurs for a period of 10 consecutive trading days.
The use of proceeds of the notes will be used for general corporate purposes such as financing general working capital and financing of existing debts.
1H21 Financial highlights
For its half year (“1H21”) results for the financial year ending 30 June 2021, the company improved significantly and reported 15.5% year-over-year (“YoY”) growth from 1H20. Revenues grew to SGD 3,677m in 1H21 as compared to SGD 3,182m in 1H20. Most business segments were profitable with the company improving net profits to SGD 297m in 1H21 as compared to a net loss of SGD 536m for 1H20. The management made several efforts in terms of cost management and have improved operational performance for the company especially in the Energy & Environment segment. Performance for 1H21 topped that of pre-pandemic results of 1H19. When excluding revaluations, impairments and divestments (“RID”) and COVID-19 related government grants, Keppel achieved a net profit of SGD 280m in 1H21, compared to a net profit of SGD 149m in 1H19.
Figure 1: Net Profits of Keppel
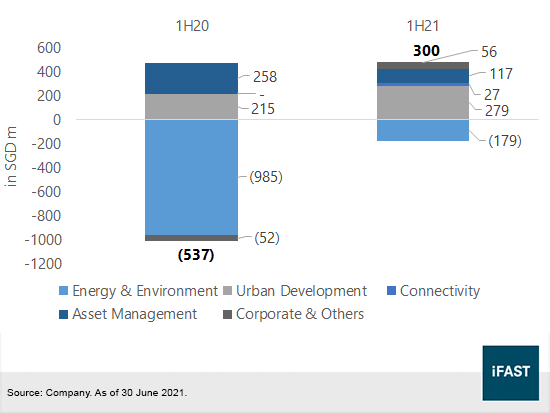
For the Energy & Environment segment, revenues grew to SGD 2,104m, a 4% growth from the prior year. The segment recorded net loss of SGD 179m in 1H21 showing improvement as compared to a net loss of SGD 958m in 1H20. The net loss was largely due to impairments of SGD 318m due to the liquidation of KrisEnergy.
Keppel Offshore and Marine (“Keppel O&M”) recorded a net profit of SGD 107m in 1H21 as compared to a net loss of SGD 959m in 1H20. EBITDA (earnings before interest, depreciation and amortization) for Keppel O&M was positive for the half and has shown improved performance due to cost management efforts by the management.
On 24 June 2021, Keppel O&M and Sembcorp Marine announced a non-binding Memoranda of Understanding (“MOU”) to combine both Keppel O&M and Sembcorp Marine into a single entity. Investors may read our views on the proposed combination here. Keppel has done well in reducing cost for this segment, reducing over SGD 525m per year from its cost structure.
Keppel Infrastructure (“KI”) recorded net profits of SGD 60m in 1H21. KI will shift its focus into renewable sources and zero-carbon electricity import in view of the global energy transition. On 28 July 2021, KI was selected for a Front End Engineering Design study to co-develop a Natural Gas Liquids Extraction Project on Jurong Island.
The Urban Development segment improved their revenue in 1H21 due to stronger earnings from Keppel Land. Keppel Land contributed SGD 252m in revenue, up 25% from 1H20. The growth in revenue was largely due to higher contribution from China and Vietnam property trading projects. In the first half of 2021, Keppel Land doubled their home sales to 2,650 homes – 440 in Singapore, 1,550 in China, 330 in Vietnam, 160 in Indonesia and 170 in India.
In the Connectivity segment, revenues remained relatively flat as revenues were SGD 588.5m in 1H21 as compared to SGD 588.9m in 1H20. Although revenues were stable, net profits for the connectivity segment grew to SGD 27.7m. Net loss for Keppel Data Centres also shrunk from SGD 12m in 1H20 to SGD 2m in 1H21. Designs for Bifrost Cable System are close to being finalised and is expected to start manufacturing in 2022. M1 continues to be impacted by the pandemic, with a lower net profit of SGD 21m as COVID-19 continues to impact roaming and prepaid revenue.
Lastly, in the Asset Management segment, net profit was S$117 million for 1H 2021, compared to S$258 million for 1H 2020. 1H 2020 had benefitted from S$177 million in gains from the reclassification of KIT and sale of Keppel DC REIT units. Keppel Capital’s net profit of S$64 million grew 23% year-on-year, mainly due to stronger operating results as well as gains from mark-to-market of investments.
Credit profile of Keppel Corporation
As of 30 June 2021, Keppel has cash and cash equivalents of SGD 2,400m and total borrowings for the company amounted to SG 12,208m and of which SGD 4,557m were repayable within one year. Total borrowings included current lease liabilities of SGD 82.4m and non-current lease liabilities of SGD 504.6m. Certain subsidiaries of the Company pledged their assets in order to obtain loans from financial institutions. The company has mortgaged certain properties and assets of up to SGD 2,322m to banks for loan facilities.
Table 1: Credit profile of Keppel
|
in SGD m |
1H21 |
1H20 |
|
|
Total Equity |
11,529 |
11,156 |
|
|
Net Debt |
9,808 |
10,123 |
|
|
Net Gearing Ratio |
0.85x |
0.91x |
|
| Source: Company, As of 30 June 2021 | |||
For 1H21, Keppel’s net gearing ratio (net debt/total equity) was 0.85x, a decrease from 0.91x in 1H20. Although net gearing ratio is high, we find Keppel’s credit profile to be adequate and we expect Keppel to continue to deleverage through its asset monetisation plan in its Vision 2030 plan to unlock SGD 2b to 5b in monetisable assets in the next 3-5 years.
Pricing comments
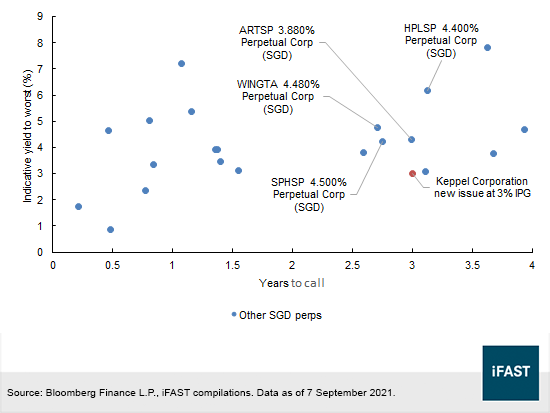
Keppel Corp’s new perpetual notes are fairly priced at an initial price guidance of 3%. The notes may not have the highest yield among other SGD perps but the lower pricing may be reflective of the conglomerate’s diversified business nature as well as Temasek shareholder interest.
Among other SGD notes and referring to Figure 2, perps issued by hospitality issuers such as the HPLSP 4.400% Perpetual Corp (SGD) and ARTSP 3.880% Perpetual Corp (SGD) are trading at a higher yield, but that is due to the cloudy outlook for the hotel industry. Tourist arrivals have remained low and it may take a while before tourism rebounds back to pre-Covid levels.
With regard to the SPHSP 4.500% Perpetual Corp (SGD), we note that the perps are trading at a premium and may be called at 100 if Singapore Press Holdings (“SPH”) is delisted from the Singapore Exchange. The corporate situation remains fluid at SPH and as such, we do not recommend taking any fresh positions in these perps until more information is provided.
Nevertheless, investors who prefer a higher yielding security may consider the WINGTA 4.480% Perpetual Corp (SGD). Wing Tai Holdings recently announced good results for FY2021 on 26 August 2021. Revenue increased from SGD 371.0m in FY2020 to SGD 461.4m in FY2021. Earnings before interest and taxes soared from SGD 100.3m to SGD 152.7m in the same period. Wing Tai has a very healthy liquidity profile with SGD 773.0m of cash and cash equivalents and SGD 150.9m of current borrowings. Its high earnings growth and strong credit profile make it a worthy investment.
Figure 2: Relative valuation among SGD perpetual notes
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) has a principle position in ARTSP 3.070% Perpetual Corp (SGD), WINGTA 4.080% Perpetual Corp (SGD), SPHSP 4.500% Perpetual Corp (SGD) and the analyst who produced this report holds a NIL position in the abovementioned securities. Keppel is seeking to acquire Singapore Press Holdings via a Scheme of Arrangement. The proposed transaction will be subjected to approval from regulators and shareholders. SPH is a substantial shareholder of iFAST Corporation Ltd (parent of IFPL), holding a 14.63% deemed interest (as at 5 March 21) through its wholly-owned subsidiary, SPH Invest Ltd.
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!