Following the release of their fourth quarter results last week, Mapletree Industrial Trust (“MINT”) is looking to raise capital through a new perpetual note offering. The notes have an initial price guidance (“IPG”) of 3.375% and are not callable within 5-years.
About the new issue
Mapletree Industrial Trust Treasury Co Pte Ltd is the issuer of the perps while Mapletree Industrial Trust is the guarantor of the new issue. With an expected credit rating of BBB- by Fitch Ratings, the subordinated notes are ranked senior only to equity. If not called on its first call date in May 2026, the distribution rate on the perps will reset to the sum of the prevailing 5-year Swap Offer Rate (“SOR”) + initial spread.
Note terms and conditions will follow that of its SGD 2 billion Euro Medium Term Securities Programme dated 5 Sep 2018. Under the dividend stopper clause, the issuer is restricted from making payments if certain note distributions are not paid. As of 12pm this afternoon, order books for this debt offering have reached over SGD 500m.
About MINT
Mapletree Industrial Trust is a real estate investment trust listed (“REIT”) that has been listed on the Singapore Exchange since 21 Oct 2010. The principal mandate of the REIT is to invest in income generative industrial real estate. Mapletree Investments Pte Ltd, a leading real estate developer, investor and manager in Singapore, is the REIT sponsor. Temasek Holdings has a deemed 30.93% interest in the trust as at 29 May 2020 through its associate companies and subsidiaries.
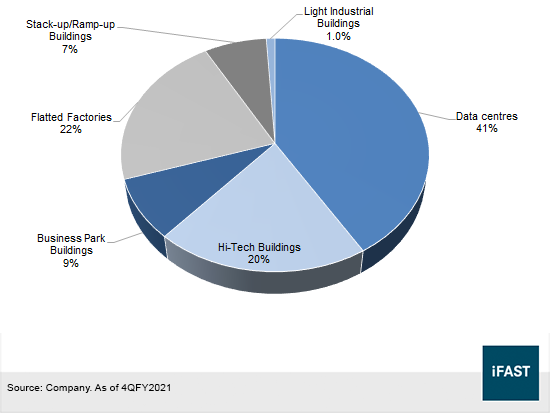
As of 31 Mar 2021, MINT’s portfolio is represented by 87 properties in Singapore as well as 28 properties in North America with total assets under management (“AuM”) of SGD 6.8 billion. Some example property types in the portfolio include data centres, hi-tech buildings, business parks, flatted factories, stack-up/ramp-up buildings and light industrial properties. A breakdown of the portfolio’s percentage composition by property type is shown in Figure 1.
Figure 1: Portfolio breakdown by property segment
MINT has a net lettable area (“NLA”) of 21.3m square feet and a weighted average lease (“WALE”) expiry 4 years. The WALE for the Singapore portfolio is 3.1 years and the WALE for the North American portfolio is 6.2 years. Valuations for its Singapore properties declined from SGD 4,447.9m in March 2020 to SGD 4,392.1m in March 2021. On the other hand, valuations for MINT’s interest in its North American properties increased from SGD 1,446.7m to USD 1.768.6m.
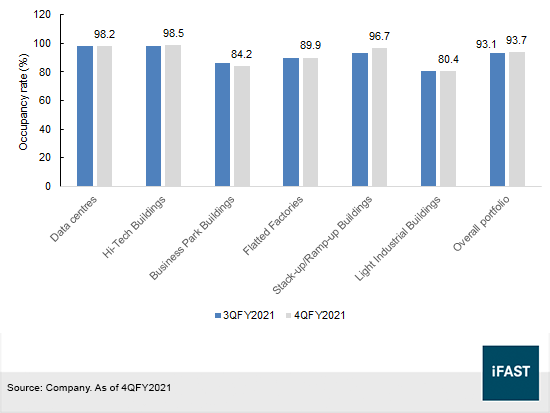
Overall portfolio occupancy improved to 93.7% in the fourth quarter ended 31 Mar 2021 (“4QFY2021”) from 93.1% in the preceding third quarter (“3QFY2021”). During this time, occupancies at stack-up buildings, Hi-Tech Buildings and Flatted Factories registered gains while occupancies at business parks declined (Figure 2).
Figure 2: Portfolio occupancy rates across property segment
Recent financial performance
Following JTC’s recent announcement, prices of industrial real estate increased by 0.9% QoQ during the quarter ended 31 Mar 2021. Due to the pandemic and the interruption of construction activities, only 131,000 square meters of industrial real estate were completed in the first quarter and this is far lower than the original projection of 1m square meters
Moving forward, JTC expect industrial prices and rentals to remain around this level in 2021 underpinned by an economic recovery in Singapore. However, the outlook for Singapore’s industrial sector is less appealing compared to the growth prospects of data centres in the United States. CBRE expects investments in US data centres to soar this year due to high sector revenue projections with hyperscale and cloud service providers driving demand.
MINT recorded an 18.9% jump in its quarterly top-line from SGD 101.8m in 4QFY2020 to SGD 121.1m in 4QFY2021. Net property income increased 17.3% to SGD 91.8m in this period. This was due to the consolidation of revenue from 14 US data centres, the grant of rental reliefs to selected tenants and the redevelopment of Kolam Ayer 2. The REIT guided that rental arrears improved or dropped from 1.4% at 3QFY2021 to 1.2% in 4QFY2021.
After accounting for SGD 14.8m of borrowing costs, SGD 12.2m of trust expenses, SGD 87.1m of net fair value losses on investment properties, SGD 9.2m of joint venture results and SGD 32.7m of income tax expenses, MINT recorded a net loss of SGD 45.8m in 4QFY2021 (4QFY2020: SGD 170.7m)
REIT earnings before interest and taxes (“EBIT”) fell from to ~SGD 60.3m in 4QFY2020 to ~SGD 80.6m in 4QFY2021, but this is more than enough to cover its SGD 14.3m of borrowing expenses, leaving the trust with a healthy ~5.7x EBIT/interest multiple (4QFY2020: ~6.3x). Interest coverage ratio for the quarter, according to the trust’s guidance, was 6.0x as at 31 Mar 2021.
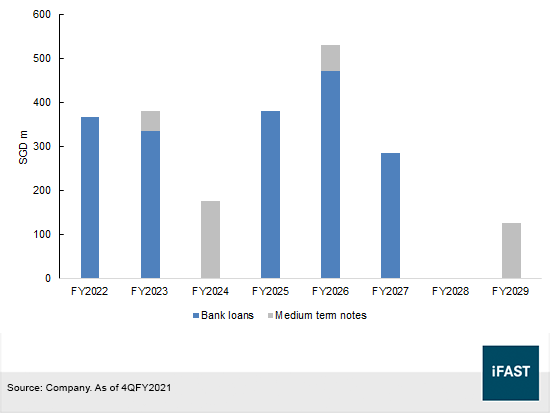
Gearing is within regulatory limits and residing at a comfortable level. The aggregate leverage ratio for the trust increased to 40.3% in 4QFY2021 from 37.3% in 3QFY2021 on the back of higher borrowings. However, its entire loan portfolio is unencumbered and this gives the trust a good amount of headroom to raise more debt if required. MINT also has access to more than SGD 600m of committed facilities, which may be used to pay down short term borrowings.
Figure 3: Debt maturity profile
Pricing comments
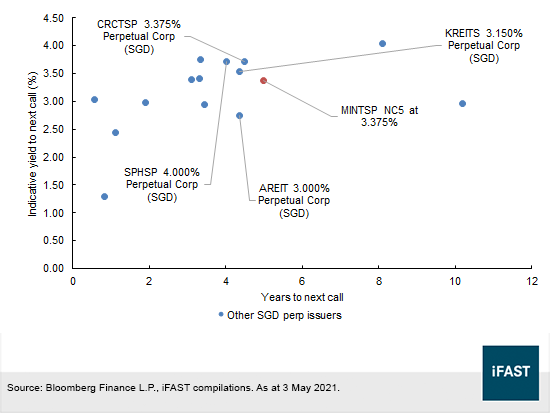
We think that the 3.375% IPG from Mapletree Industrial Trust Treasury Co Pte Ltd (“MINTSP”) is fairly priced compared to the AREIT 3.000% Perpetual Corp (SGD) for a 63 basis point pickup and a 0.5 year difference in tenor.
The AREIT 3.000% Perpetual Corp (SGD) traded at a yield to call of 2.74% on 4 May 2021. AREIT, or Ascendas Real Estate Investment Trust is Singapore’s largest business and industrial REIT with 209 properties and SGD 15.1 billion of investment properties. It has a larger operating scale than MINT and has an A3 issuer rating by Moody’s Investors Service.
Although they are not directly comparable due to their different business profiles, we think investors may also consider the CRCTSP 3.375% Perpetual Corp (SGD), SPHSP 4.000% Perpetual Corp (SGD) or KREITS 3.150% Perpetual Corp (SGD) for their higher yields to call of 3.72%, 3.72% and 3.53% respectively.
Figure 4: Relative valuation among non-bank SGD perpetual notes
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) and the analyst who produced this report hold a NIL position in the abovementioned securities
Our podcast series, Yield Hunters, is available on Spotify and iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!