


In this series of articles, we provide an overview of issuers currently on our watchlist, including the latest developments and our commentary on each issuer.
But before that, we have also provided a summary of several issuers that we are keen on:
|
Company |
Latest Developments |
Related article |
Comment |
|
SIBS Sdn Bhd |
- Production line utilisation rate fell to 30% in 2025 (2024: 80%) due to deferment of NEOM Trojena Project. This is expected to gradually ramp up to full capacity following SIBS diversification strategy. - As of October 2025, orderbook stood at approximately RM1.2 billion, with projects spanning across Sweden, UK, Australia and Greenland. - On top of that, there’s RM5.6 billion in pipeline currently under active contract terms negotiation, with the objective of converting them into confirmed orderbook entries. Identified project pipelines include new venture markets like Singapore and Malaysia. - 1H25 revenue fell starkly to RM242.6 million (1H24: RM1.5billion) due to deferment of NEOM project, which significant capacity had been allocated. Nonetheless, operating margin held well at 18.5%. As SIBS moves on from NEOM project, recovery in profit is expected to happen. - Capital expenditure planned for the years ahead (2026- 2028, less than RM20 mil a year) is expected to be minor, as SIBS put plant 3 expansion on hold. |
Swedish prefabricated housing firm to tap MYR bond market again at 5.50%-5.60% IPG |
While there is a notable deterioration in 1H25 operating profit (1H24: RM399mil, 1H25: RM45mil) and interest coverage ratio (FY24: 10 times, 1H25: 2.4 times), we opine we will see a definite turnaround in 2026 where the group moves on from the hiccups in NEOM project deferment and diversifies away, which is what we are currently witnessing in orderbooks. |
Moving on to the next segment, here are the latest updates on issuers we are closely monitoring, which is exhibiting elevated credit risk or even under financial distress. We have marked the changes from the previous update in bold.
|
Company |
Latest Developments |
Related article |
Comment |
|
Tan Chong Motor Holdings Berhad |
- In 3Q25, Tan Chong narrowed its net loss to RM60.25 million from RM90.28 million in 3Q24, supported by higher revenue and lower net foreign exchange losses, partially offset by higher impairment losses on receivables. -Liquidity has weakened, with cash declining to RM279.5 million from RM545.5 million as at Dec 2024, mainly due to repayments of financial obligations. - Following the partnership with China’s Wuling, Tan Chong has signed a Letter of Intent (LOI) with Perodua to provide ED coating and painting line services, as well as rental and use of certain designated assembly lines. - Perodua is considering buying Tan Chong’s Serendah plant for about RM500 million |
- On a brighter note, Tan Chong is divesting its non-core assets to strengthen cashflow and its balance sheet. - However, we continue to remain cautious on Tan Chong given weak sales volumes and persistent competitive pressures in the automotive industry. |
|
|
Pestec International Berhad |
- The issuer has deferred the perpetuals’ coupon payment for the period from 16 April 2025 to 16 October 2025. - As of 30 Sep 2025, Pestec’s group reported a net profit of RM20 million, driven by reversal of tax provision. Without it, the group will still be in the red. - Nonetheless, cash flow from operating activity for 6 months ended 30 Sep 2025 is still negative at RM72.5mil. Turnover remains distant. |
Nil |
- We are negative on Pestec’s ability to service coupon payments and principal redemption. - We believe that the company will involve perpetual holders in the restructuring plan, though timeline remains unknown. |
|
Tropicana |
- Tropicana narrowed its losses to RM60.95 million in 3Q25, compared with RM522.55 million in 3Q24, when results were hit by a one-off loss from the disposal of an investment property. - The group continues with its deleveraging, with gearing dropping from 58% in FY24 to 46% as of 30 September 2025. |
IOTW: Is Tropicana’s upcoming 3Y bond with indicative yield of 5.8% still worth considering |
- Despite the losses, we hold a positive stance towards Tropicana in view that the company will be supported by its sizeable landbank. |
|
YNH Property Bhd |
- YNH has decided not to redeem its perpetual securities – Tranche 1 and Tranche 2: : Tranche 1: The next call date is in August 2025, marking the third consecutive non-call since August 2024. The group will pay a stepped-up coupon rate of 9.85%. : Tranche 2: The call date is in July 2025, marking the first non-call. The group will pay a stepped-up coupon rate of 8.85%. - Based on 1QFY26 (Sep 25), revenue increased significantly from RM26.3 million in 1QFY25 (Sep 24) to RM62.6 million, mainly due to the sale of its development land in Mont Kiara and the completion of the disposal of Aeon Seri Manjung. - On 23 January 2026, YNH announced it would defer upcoming coupon payments under its Perpetual Securities Issuance Programme as part of a strategic cash conservation plan. - The deferral applies to both outstanding perpetual securities tranches: - Tranche 1 –: Coupon originally scheduled for 9 February 2026. - Tranche 2 –: Coupon originally scheduled for 30 January 2026. |
YNH Property Quick Update - Exercises Option to Defer Perpetual Securities Coupon |
-YNH is still actively disposing its assets to repay its outstanding loans and fulfil working capital requirements. Its liquidity position remains poor, with RM204 mil debt maturing in the coming year. - We are negative on this issuer from an operational perspective. |
|
Evergrande |
- Evergrande has officially entered a forced liquidation, and Alvarez & Marsal is the liquidator to handle the asset disposal. - The adjournment of the hearing, which was intended to seek directions on the appointment and composition of a committee of inspection for the winding up of the company, may affect the progress of the liquidation. -Capability of liquidator is key to max recovery value for debtholders. Liquidators have experience in Lehman Brother and Luckin Coffee. - Evergrande’s shares has been delisted from Hong Kong Stock Exchange on August 2025. - Liquidation is still ongoing, with liquidator having filed proofs of debt on behalf of creditors. |
- The liquidation process is still ongoing, and we posit that it will take a couple of years to complete due to its scale. |
|
|
Century Sunshine |
-Trading in CENSUN shares has been suspended since 1 April 2025 due to the company’s failure to release its 2024 Annual Report on time. -No dividend was declared for the second scheme year, as the proceeds from the share disposals were insufficient to cover the scheme costs. -There is still no decision on whether the Zhangzhou Land should continue to be reserved for the bridging loan or be disposed of. - The Luozhuang Government unilaterally terminated the relocation agreement on the ground that Shandong Hongri failed to carry out soil remediation. Shandong Hongri appealed the decision, arguing that the termination was unjustified because no clear remediation standards had been provided. - One of Shandong Hongri’s creditors obtained an enforcement ruling ordering the auction of part of its land-use rights. The land is to be auctioned as “industrial land,” resulting in a significantly depressed valuation. Shandong Hongri has filed objections and applied to revoke the enforcement ruling and to stay the auction proceedings. |
-Listing status may be cancelled if the suspension remains in effect until 30 Sep 2025. Given that there are no other available assets, we hope the land title conversion of the Shandong Land will be successfully completed, as it is likely to unlock higher value when the land is disposed of after the conversion. |
In the next section, we will delve into the insights of the yield curves for Malaysian Government Securities (MGS), US Treasuries (UST), Singapore Government Securities (SGS) and Australia Government Securities (AGS).
Our view on MGS:
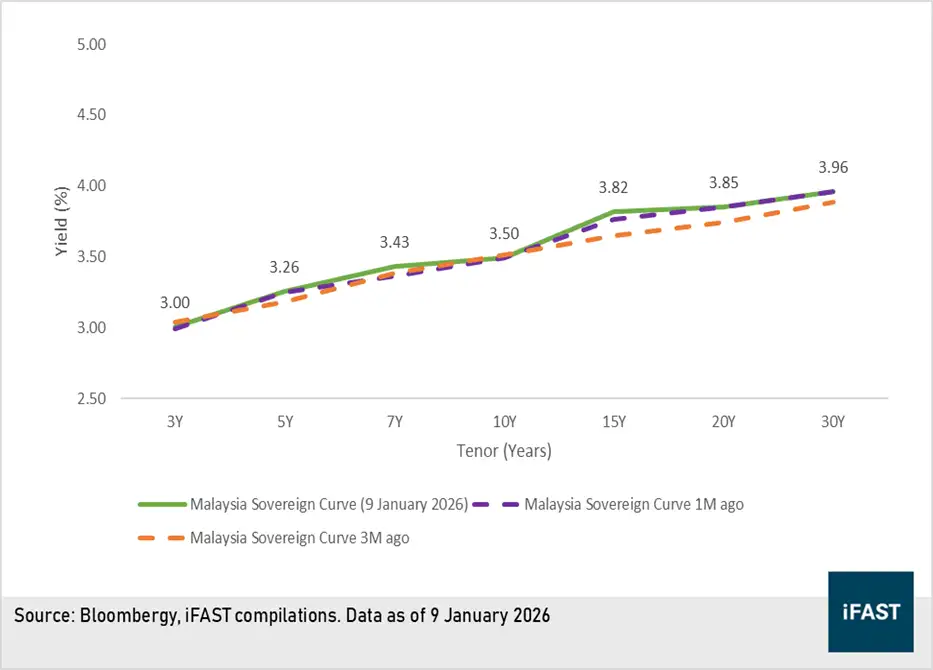
1) Malaysia’s GDP in 4Q25 (Dec 25) expanded by 6.3%, up from 4.9% in 4Q24 (Dec 24), indicating stronger-than-expected economic growth and resilient export sector performance. This diverged from our previous cautions assumption amid global trade development, highlight in Malaysia Bond Market Outlook 2026: Stability Amid Global Uncertainty. The growth is mainly supported by the government’s efforts to diversify trade partners and the increase in global trade deals, particularly with the US.
2) BNM keeps Overnight Policy Rate (OPR) steady at 2.75% in January 2026.
3) We have changed our view from a base case of a potential one rate cut to no rate cuts in 2026.
4) Continue to prefer medium-term (5-7 years)
5) Yields across the different tenors are expected to remain range-bound throughout the year
6) Yield curve remains upward sloping
Chart 1: MGS Curve
Our view on UST:
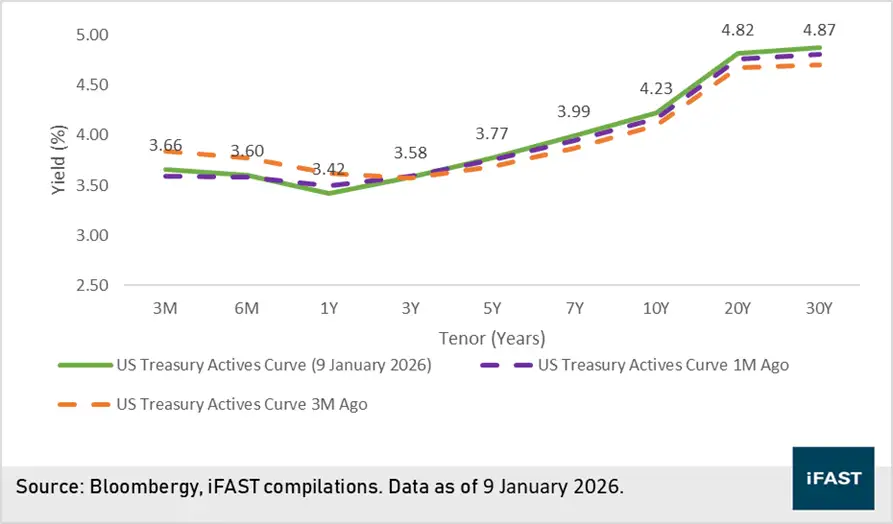
1) We anticipate a slowdown in US growth, leading to around two rate cuts in 2026
2) Yield curve is expected to normalise progressively, driven by slower US growth and persistent inflationary pressures.
3) Investors may shift towards medium-term duration, 5–10 year US Treasuries for the potential price appreciation and roll-down returns.
Chart 2: UST Yield curve
Our view on SGS:
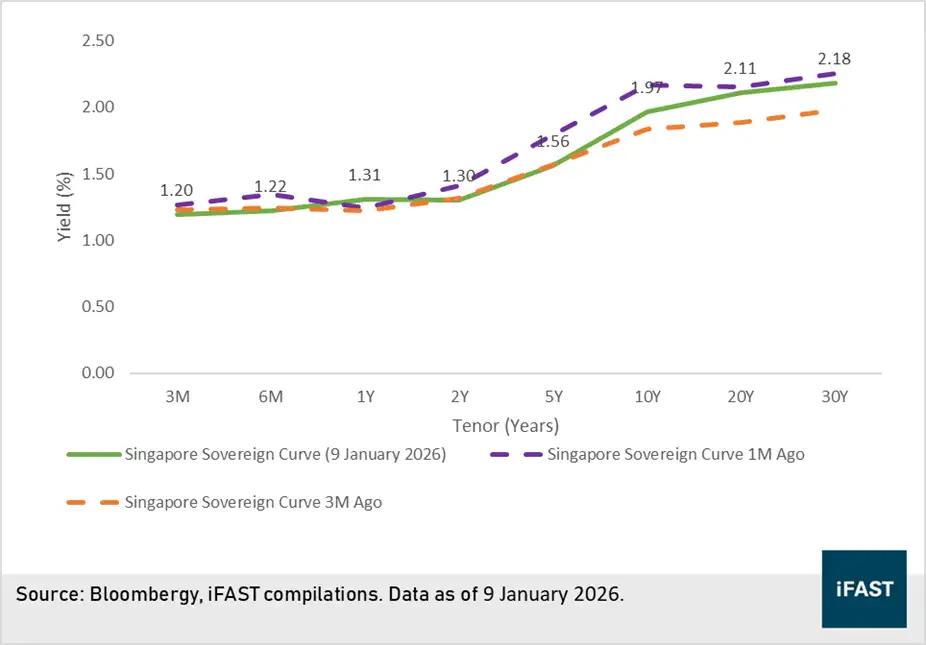
1) Sharp yield decline in 6-month T-bills this year has eroded their appeal, prompting us to step away from our prior outright preference.
2) See more value in medium term (5 to 10-year) where the yield pickup is higher.
3) See little incentive to take exposure beyond the 10-year tenor as the treasury curve is much flatter suggesting that the incremental yield pickup is unattractive
Chart 3: SGS Yield curve
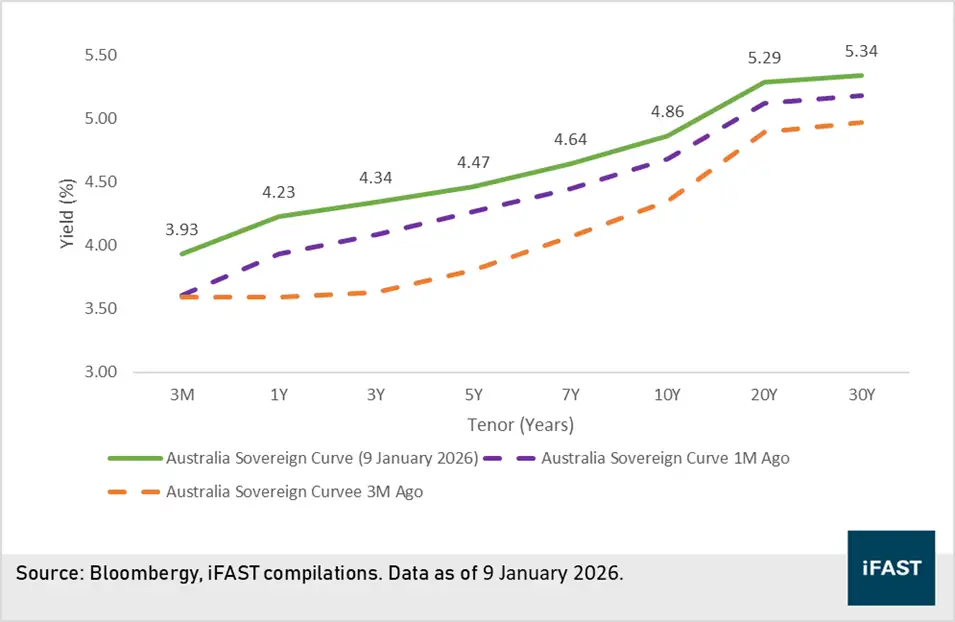
1) RBA increases cash rate to 3.85%, the first developed market to hike rates in 2026.
2) In her speech, RBA Governor Michele Bullock said that if she needs to hike interest rates further 'to slow growth in demand', she will. The board will be attentive to data, with the next monetary decision on 17 March 2026.
3) With market already expecting and pricing in for two rate hikes in 2026, we continue to advocate for longer duration play, possibly the 7 to 10 years.
Chart 4: AGS Yield curve
Some of the Credit Announcement by RAM & MARC (as of 31 January 2025)
RAM
1) Maintains positive outlook on Gamuda’s AA3 issue ratings
2) Monitoring IJM Corp following recent material developments
3) Affirms AAA(fg)/Stable rating of Hektar REIT’s RM230 mil Guaranteed Tranche(s)
4) Affirms PKNS’s AA1/P1 issue ratings
5) Upgrades YTL Corp’s ratings to AAA
6) Upgrades YTLPI’s ratings to AAA
7) Affirms Malayan Cement’s AA1/Stable/P1 sukuk
https://www.ram.com.my/news-events/?tab=list-ratingannouncement
MARC
1) Affirms ratings of MARC-1IS/AA-IS on UDA’s ICP/IMTN Programmes
2) Assigns final ratings of AAIS/A+IS to S P Setia’s Sukuk Wakalah of up to RM3.5 billion
3) Affirms Sunway Healthcare Treasury’s rating
4) Assigns final ratings to Sunway Treasury Sukuk’s ICP/IMTN (Sukuk Mudharabah) Programme of up to RM3.0 billion
5) Affirms AA+IS rating on Sime Darby Property’s Sukuk Musharakah Programme
https://www.marc.com.my/insights/rating-announcements/


